J.P. Morgan 电子元件数据手册解读:AI 服务器如何重写 MLCC 需求结构(62 页全图复刻)
逐页复刻 J.P. Morgan《Technology – Electronic Components》(2026-09-11,62 页)并附中文结构化解读:MLCC 需求结构向 AI 服务器迁移、单机架价值量 3.6 倍跃升、技术代际驱动的利润率非线性,以及基板与供给侧证据。
导读:本文逐页复刻 J.P. Morgan 亚太股票研究《Technology – Electronic Components》(2026 年 9 月 11 日,分析师 Akinori Kanemoto / Junya Ayada,62 页)的原始图表,并附本站的中文结构化解读。第一部分是原报告(52 页整页渲染,含全部图表);第二部分是我基于报告数据独立撰写的解读——MLCC 需求结构如何被 AI 服务器重写、单机架价值量的跃升、技术代际带来的利润率非线性,以及基板与供给侧的交叉验证。
收录边界(重要):原报告第 2–3 页(16 家公司的评级 / 目标价 / 估值表)与第 55–62 页(标准法务披露页)未收录;本文不含任何个股评级、目标价或投资建议,所有预测数字(CY26E–CY30E)均为 J.P. Morgan 估计而非事实。
第一部分:原报告(J.P. Morgan,2026-09-11)
以下为原报告逐页复刻。已略去:第 2–3 页(评级 / 目标价 / 估值表)与第 55–62 页(标准法务披露页)。其余 52 页全部保留,图表为原始版面整页渲染。
封面
Page 1 · 封面:报告基本信息与分析师
行业总览:股价、盈利预测与估值
这一组是整个板块的仪表盘:覆盖公司的股价表现、J.P. Morgan 的盈利预测与一致预期对比、自由现金流与资本回报指标、汇率敏感性,以及板块相对 TOPIX 的历史估值区间。
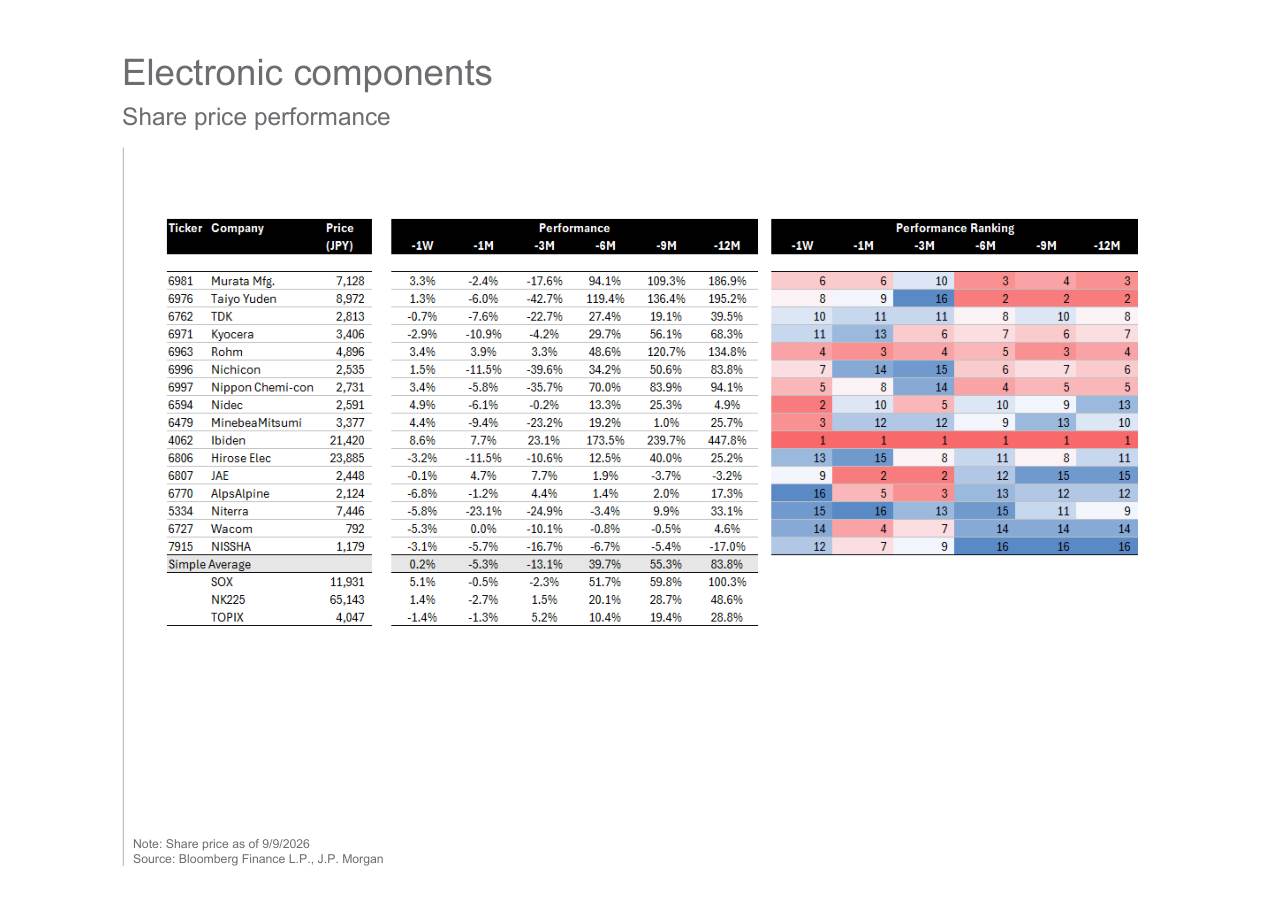
Page 4 · Electronic components:股价表现
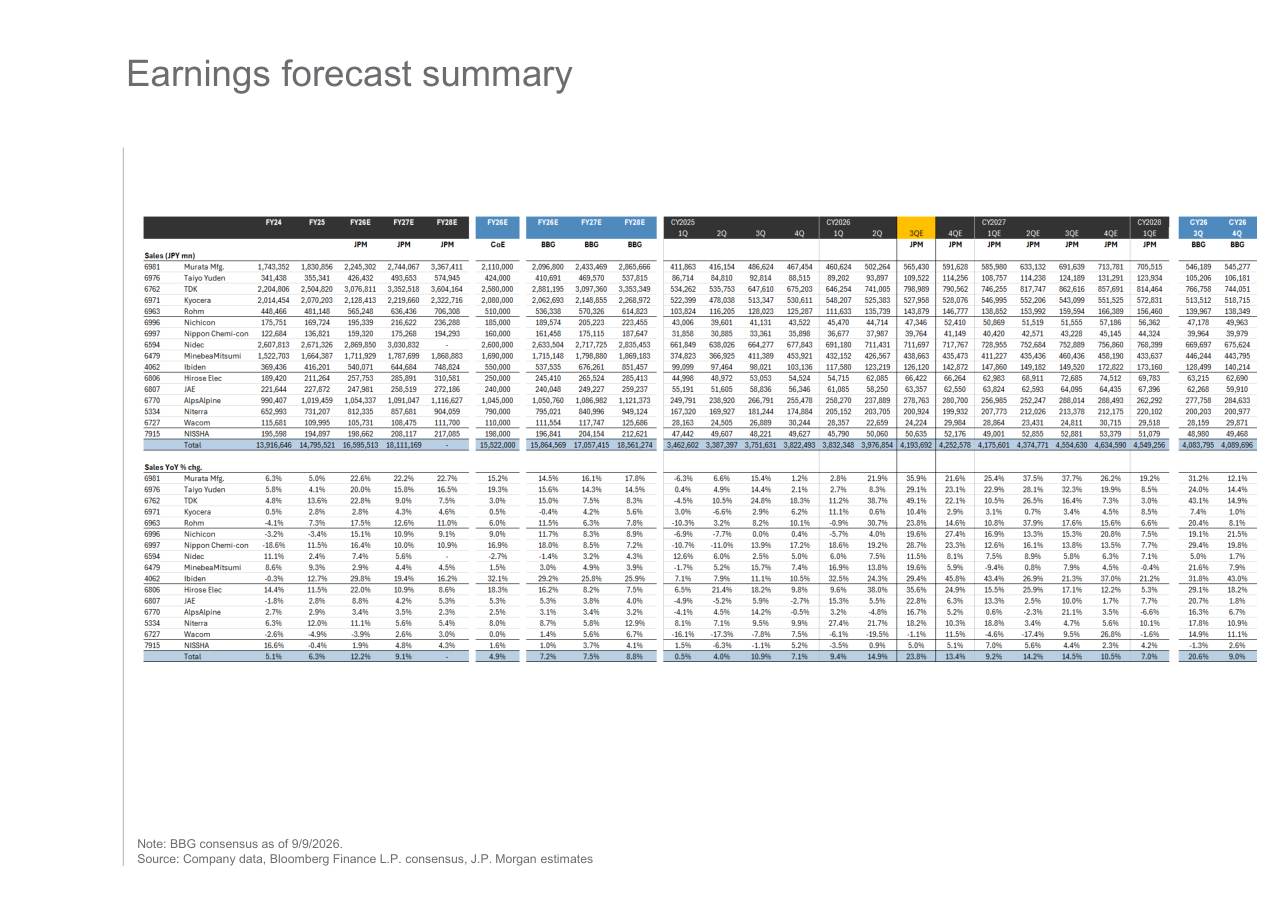
Page 5 · Earnings forecast summary(盈利预测摘要 I)
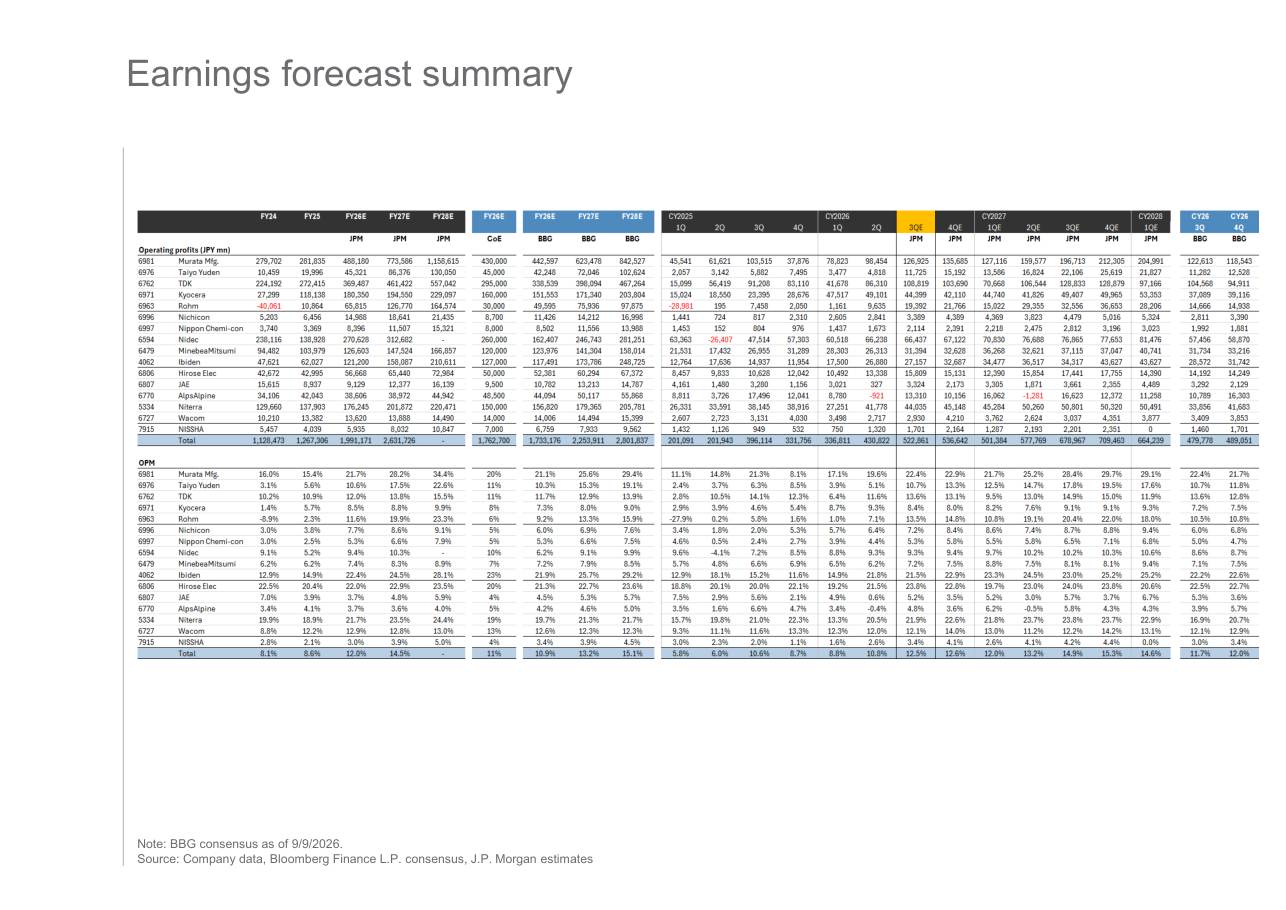
Page 6 · Earnings forecast summary(盈利预测摘要 II)
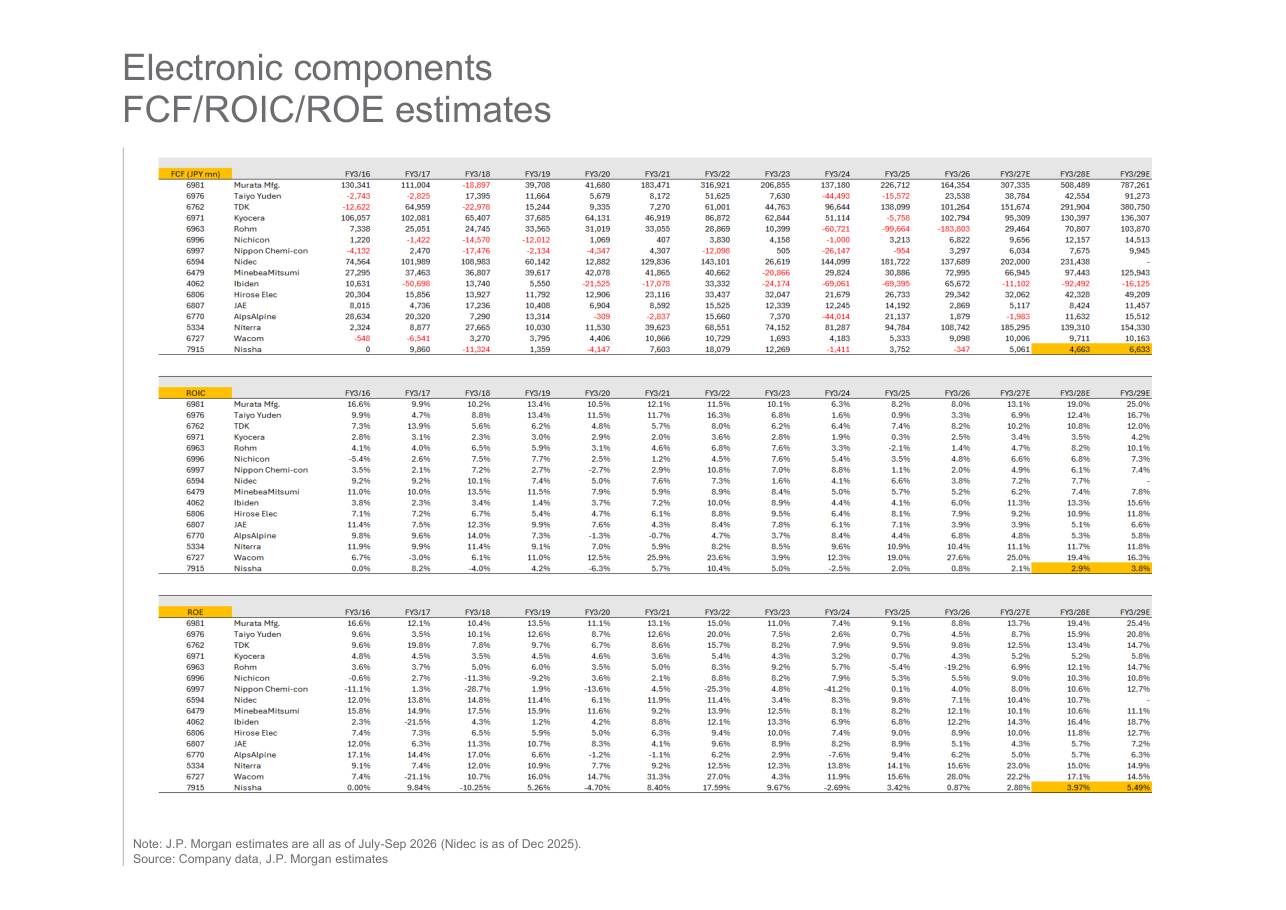
Page 7 · FCF / ROIC / ROE 估计
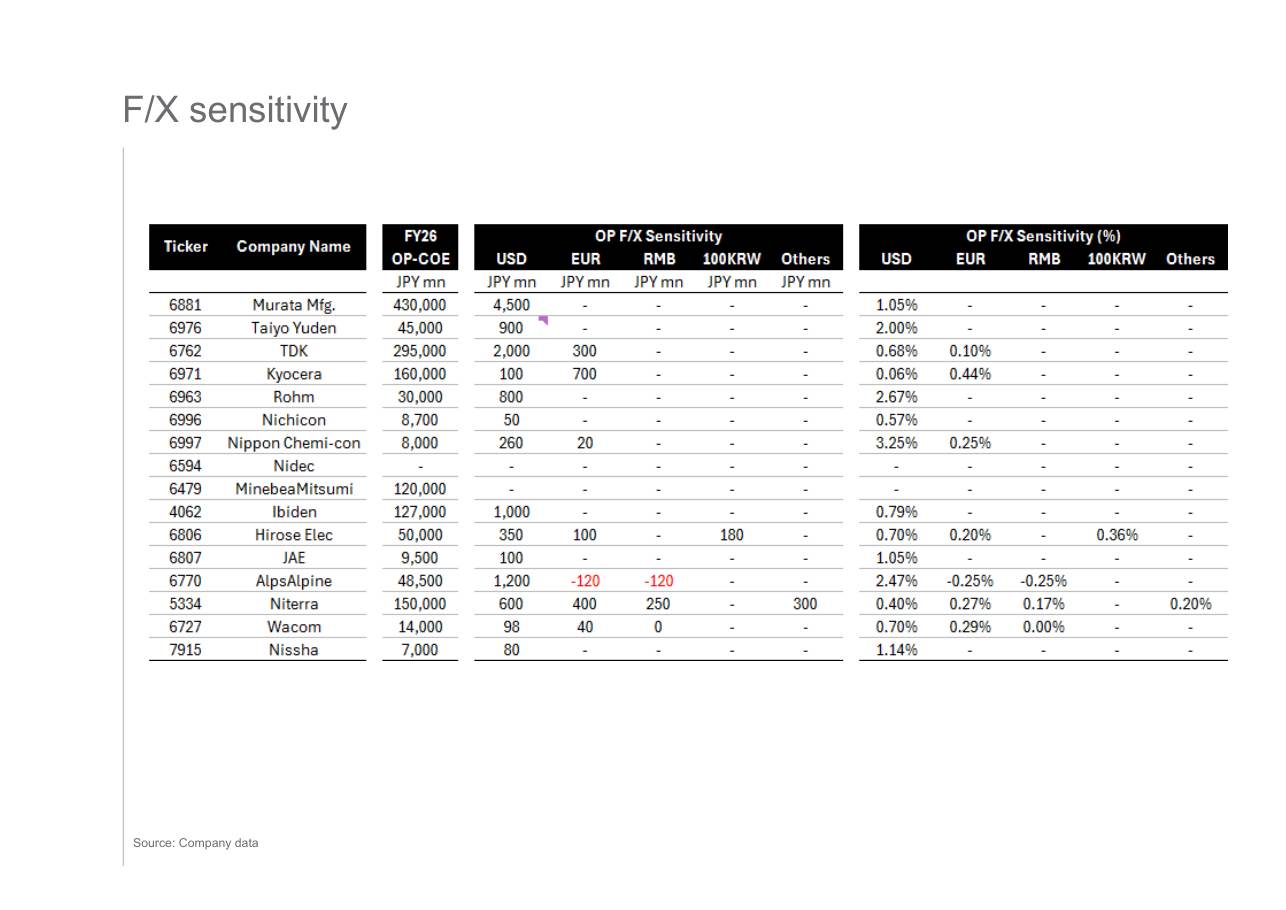
Page 8 · F/X sensitivity(汇率敏感性)
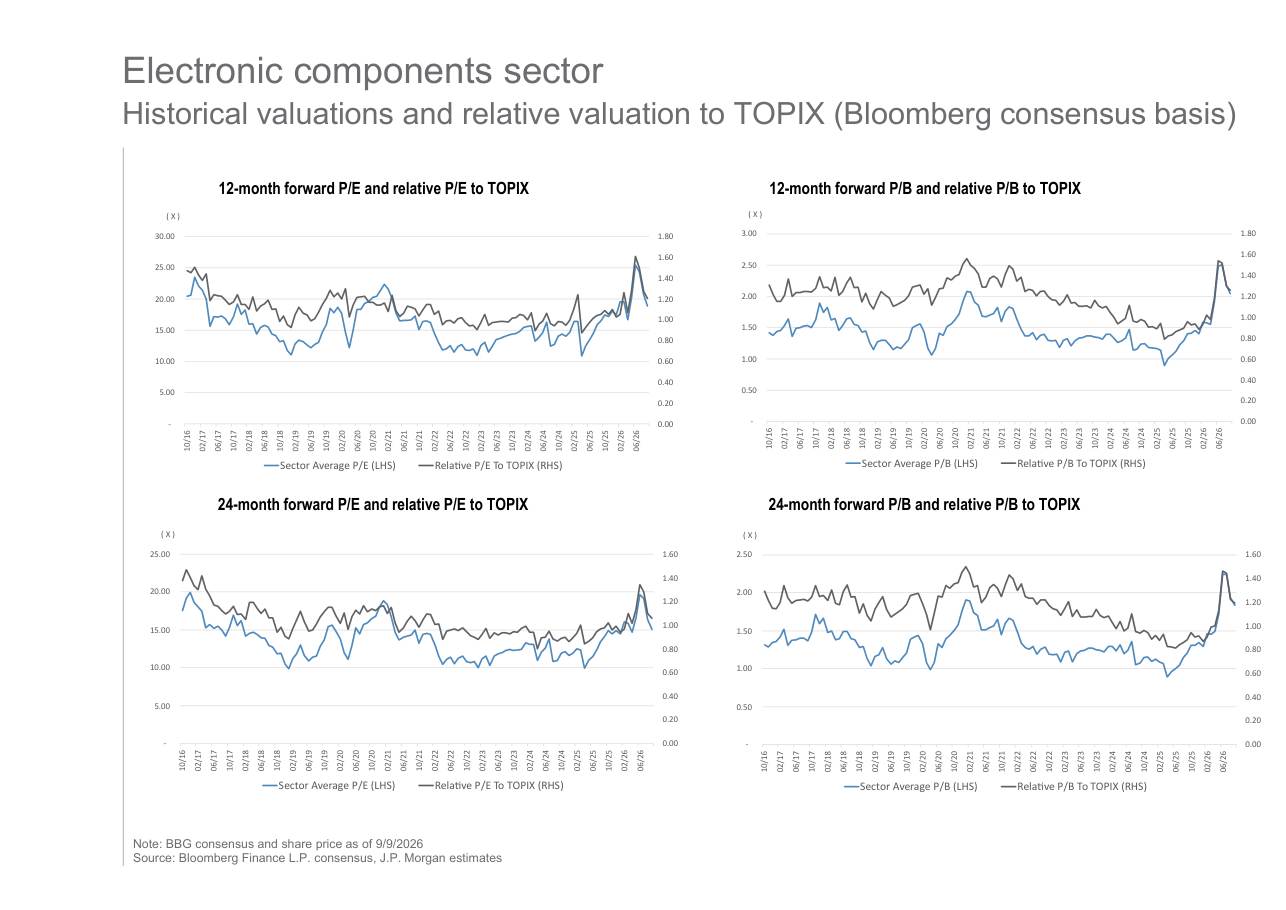
Page 9 · 板块历史估值与相对 TOPIX 估值(12/24 个月远期 P/E、P/B)
MLCC:市场结构与需求预测
MLCC 是这份手册的重心。这里回答四个问题:需求来自哪些应用、份额如何分布、单台设备贡献多少价值量、以及到 2030 年市场会变成什么形状。
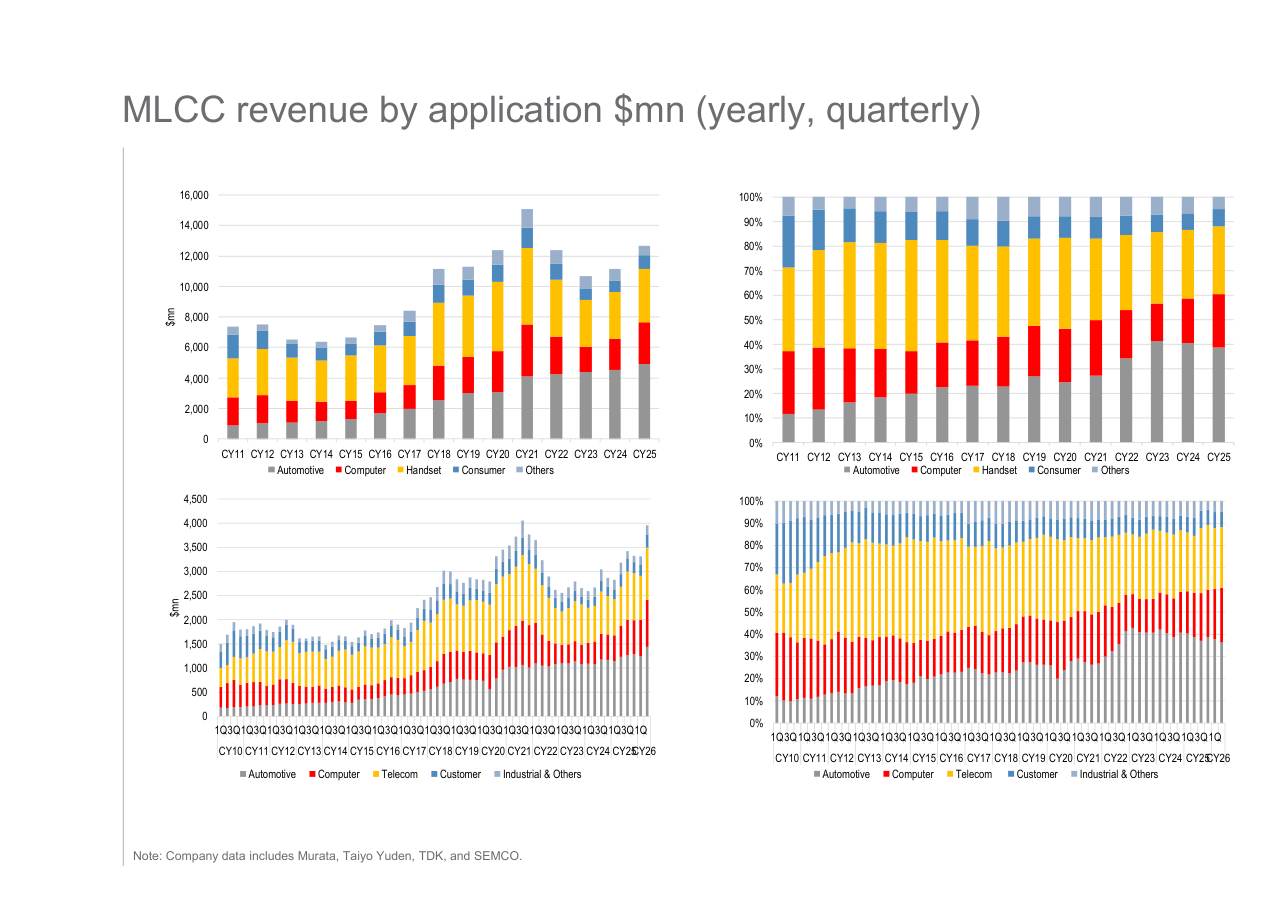
Page 10 · MLCC 收入按应用拆分(年度 / 季度)
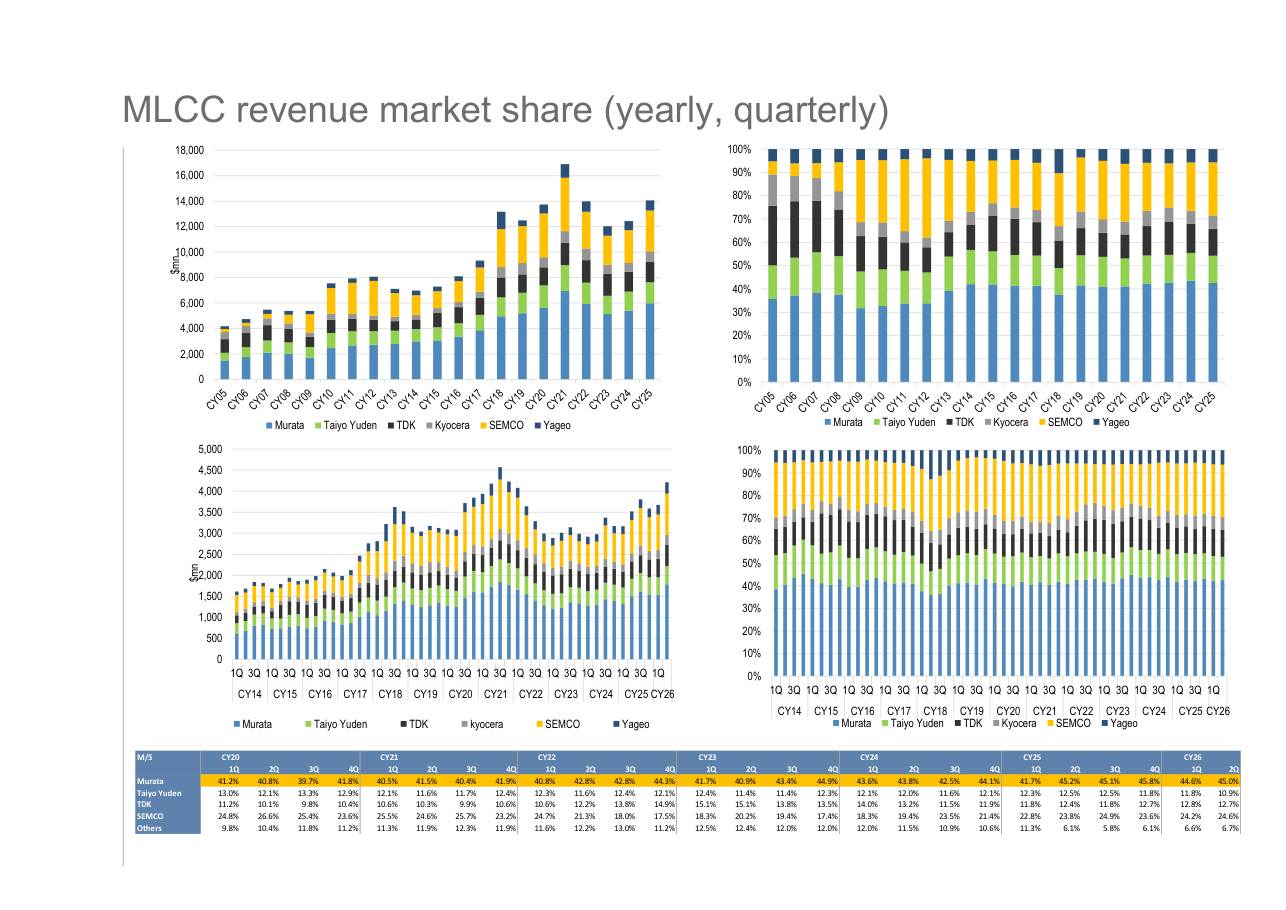
Page 11 · MLCC 收入市占率(年度 / 季度)
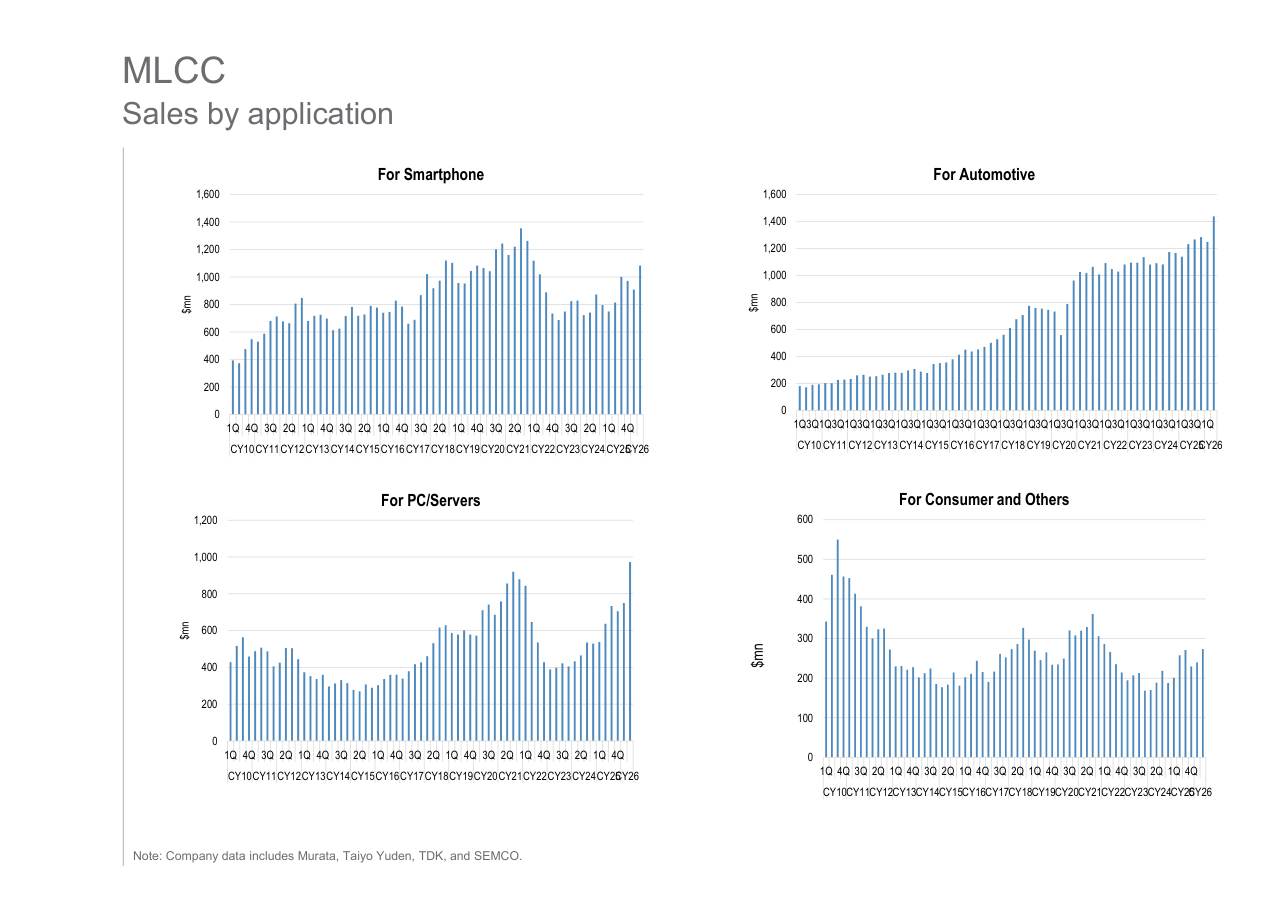
Page 12 · MLCC 按应用的销售额(手机 / 汽车 / PC 服务器 / 消费)
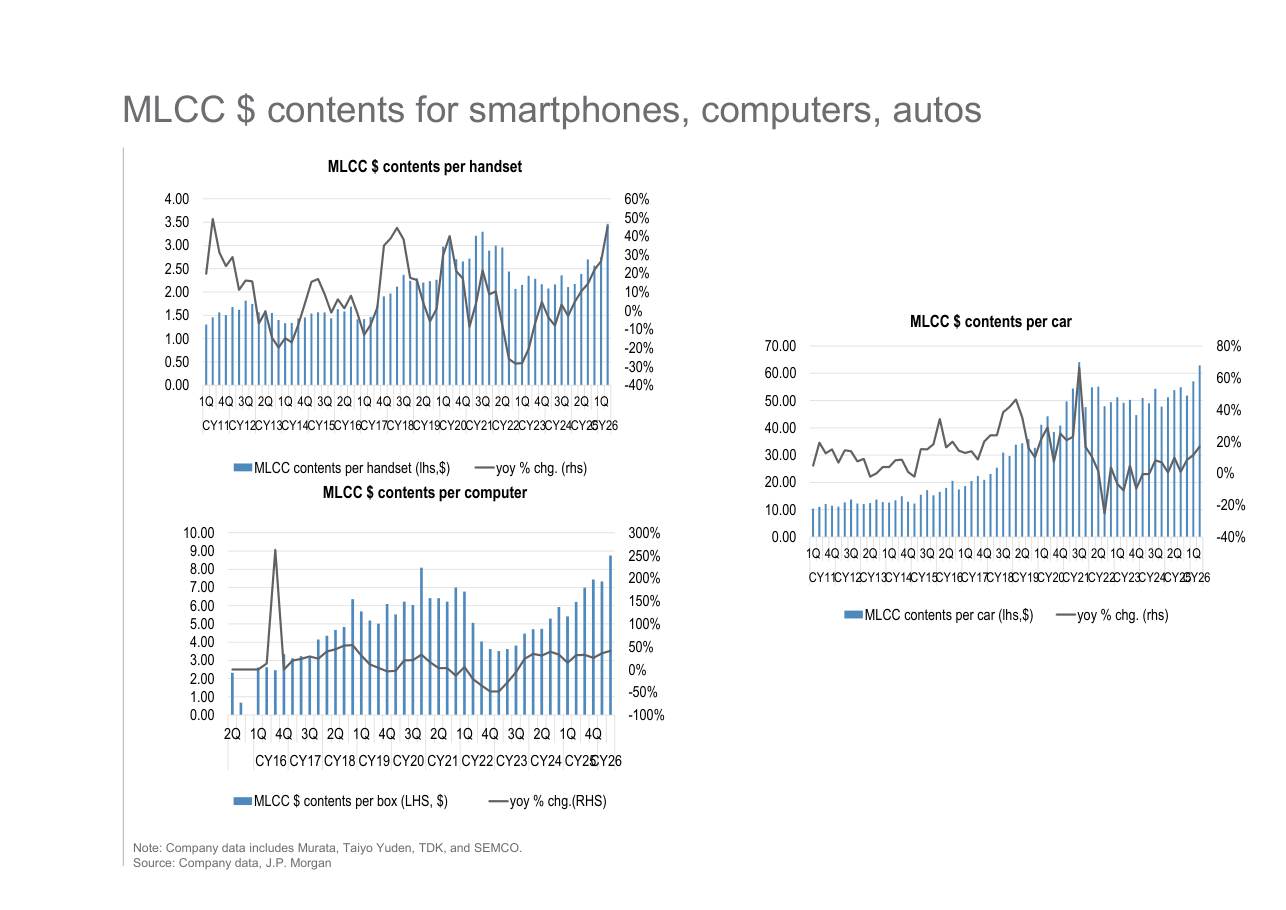
Page 13 · MLCC 单机价值量:手机 / 电脑 / 汽车
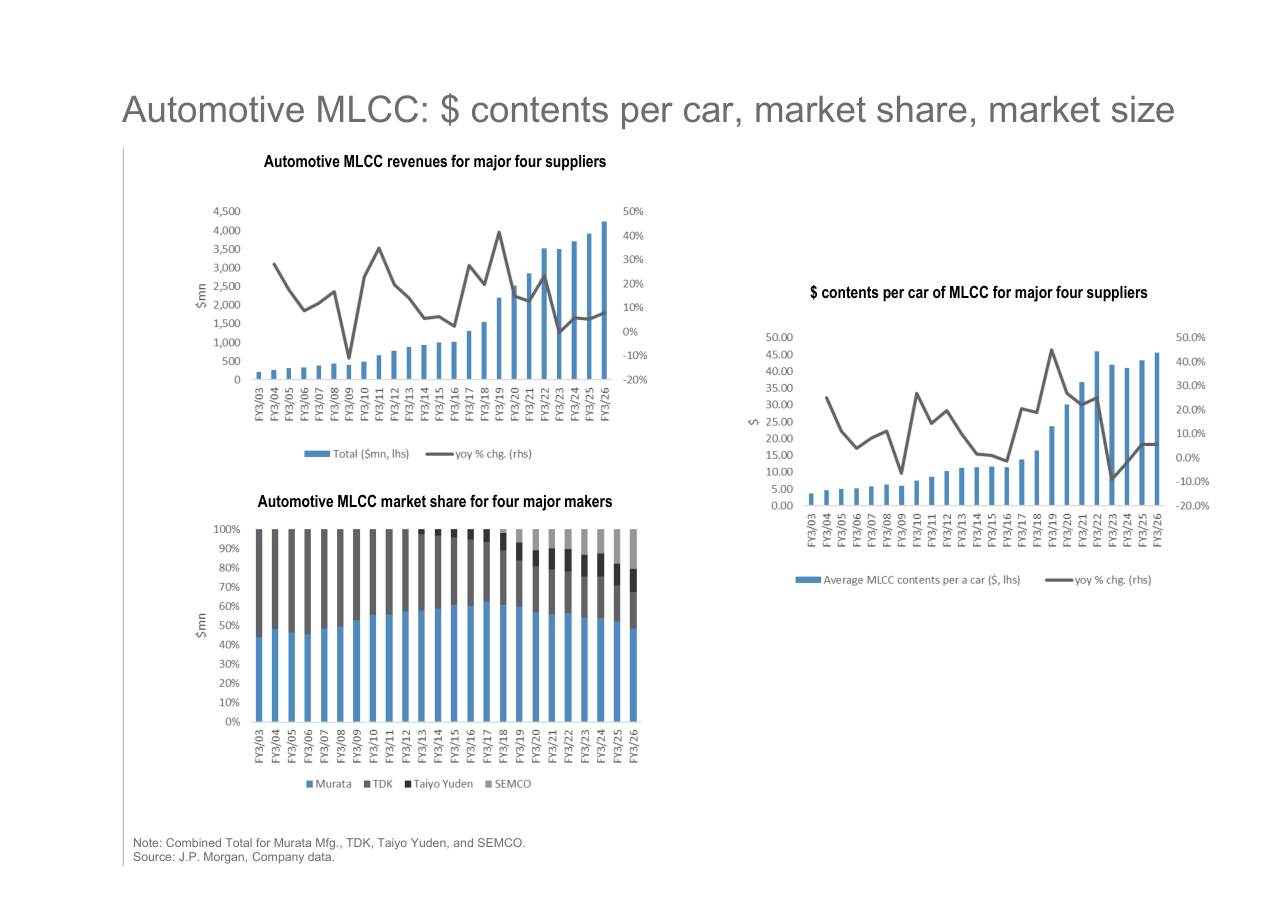
Page 14 · 车用 MLCC:单车价值量、市占率、市场规模
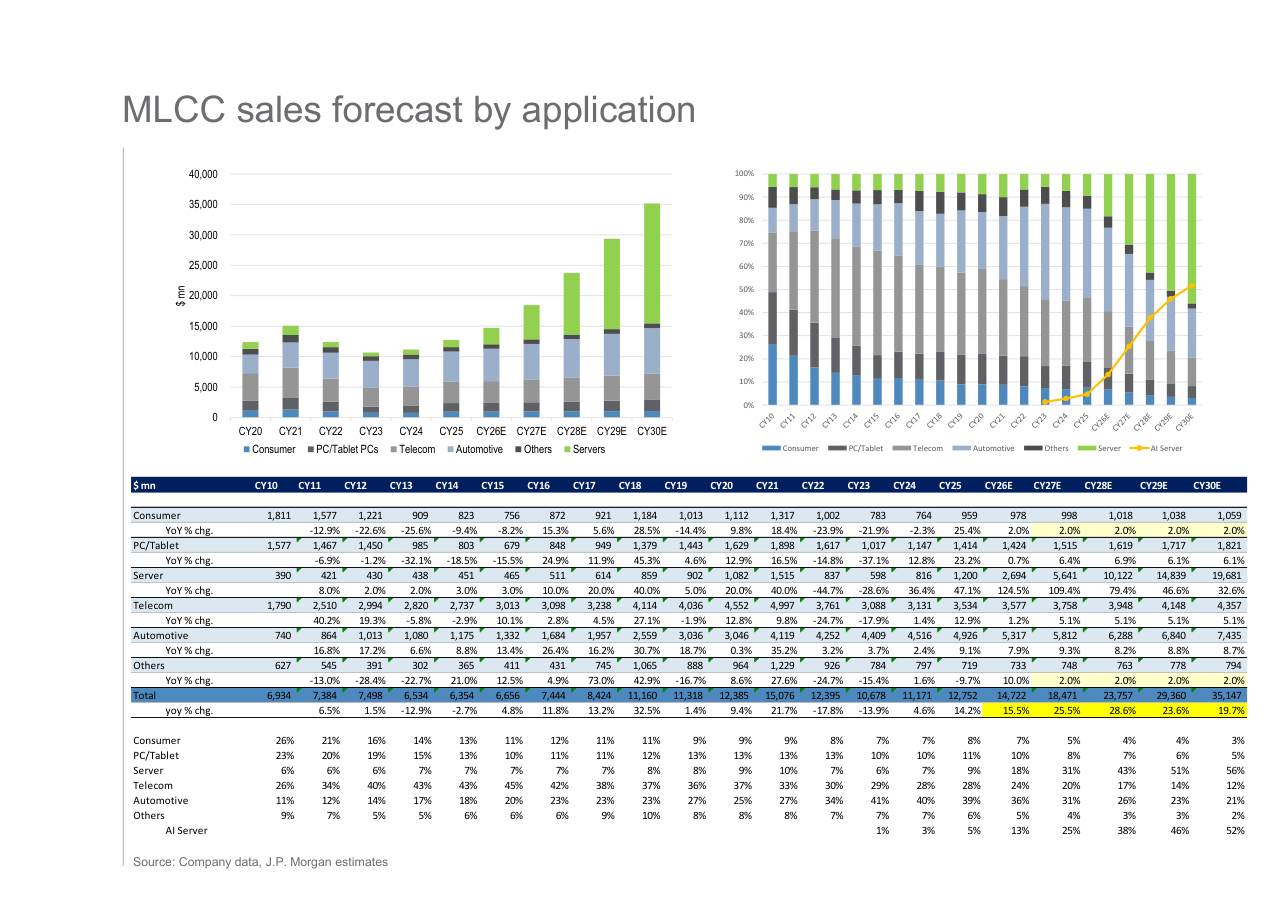
Page 15 · MLCC 销售预测(按应用,至 CY2030E)
MLCC:供给、产能与供需平衡
需求故事的另一面是供给:稼动率、月产能、扩产节奏(以 Murata 工厂建设为样本)、供需平衡模型,以及降价周期对利润的量化冲击。
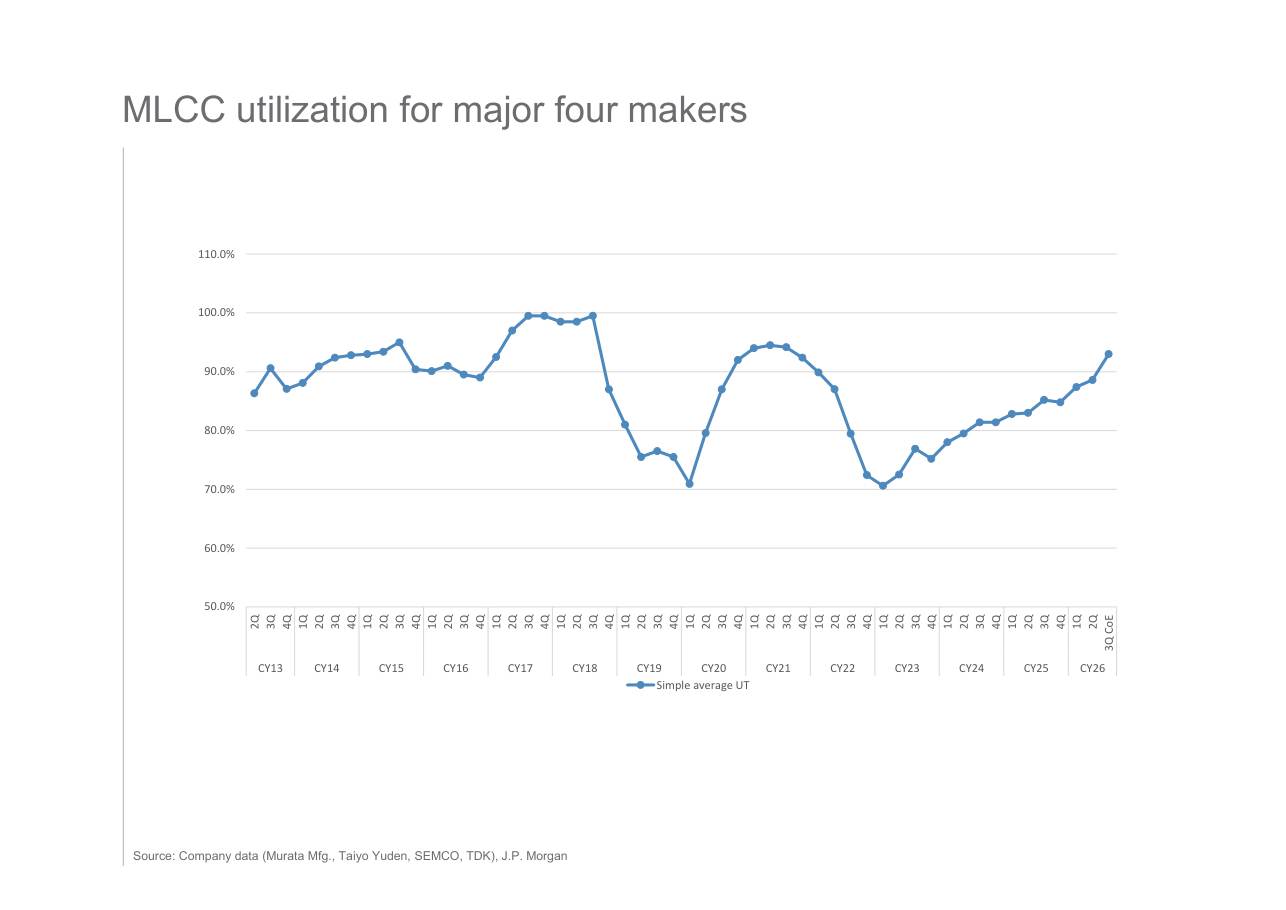
Page 16 · 四大厂 MLCC 产能稼动率
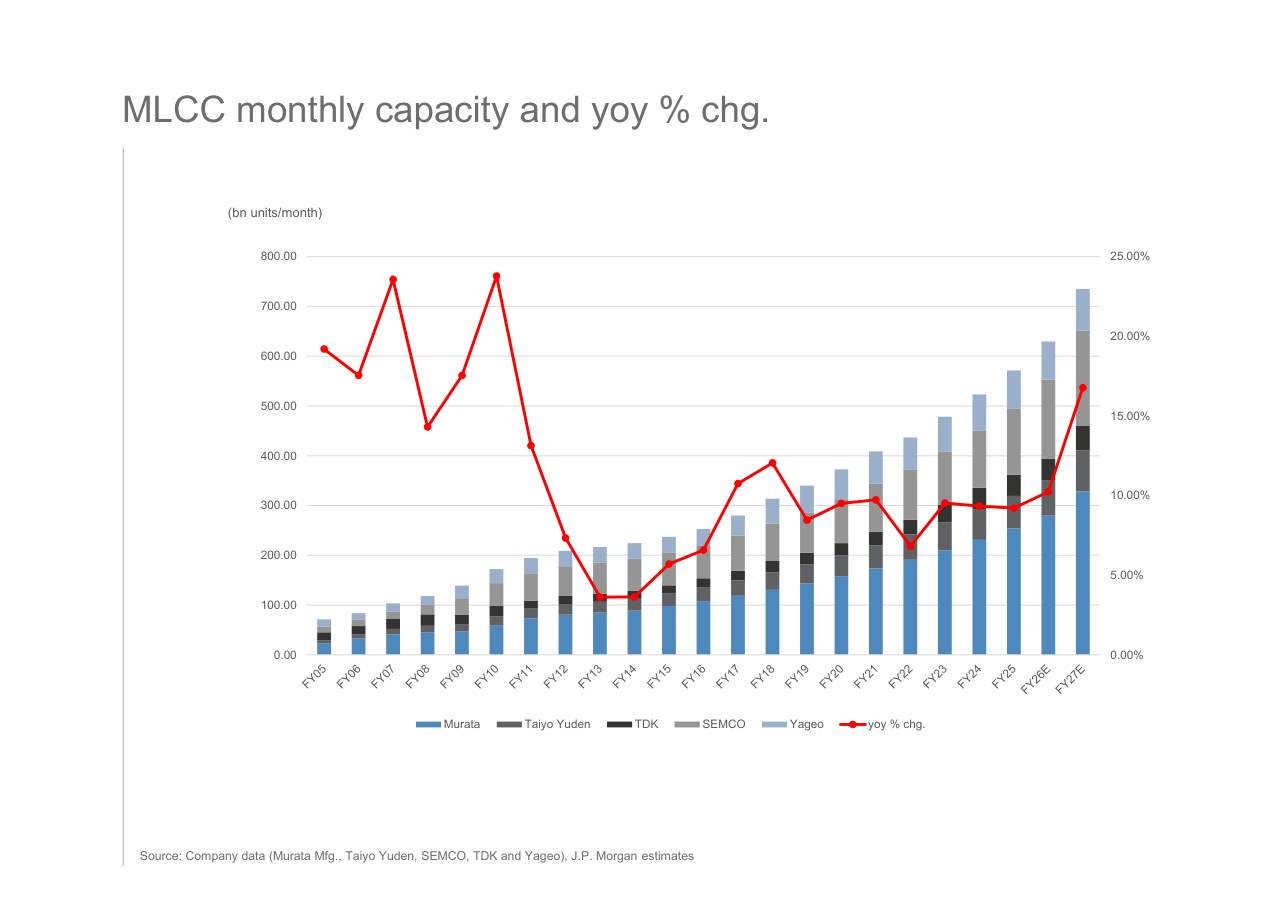
Page 17 · MLCC 月产能及同比增速
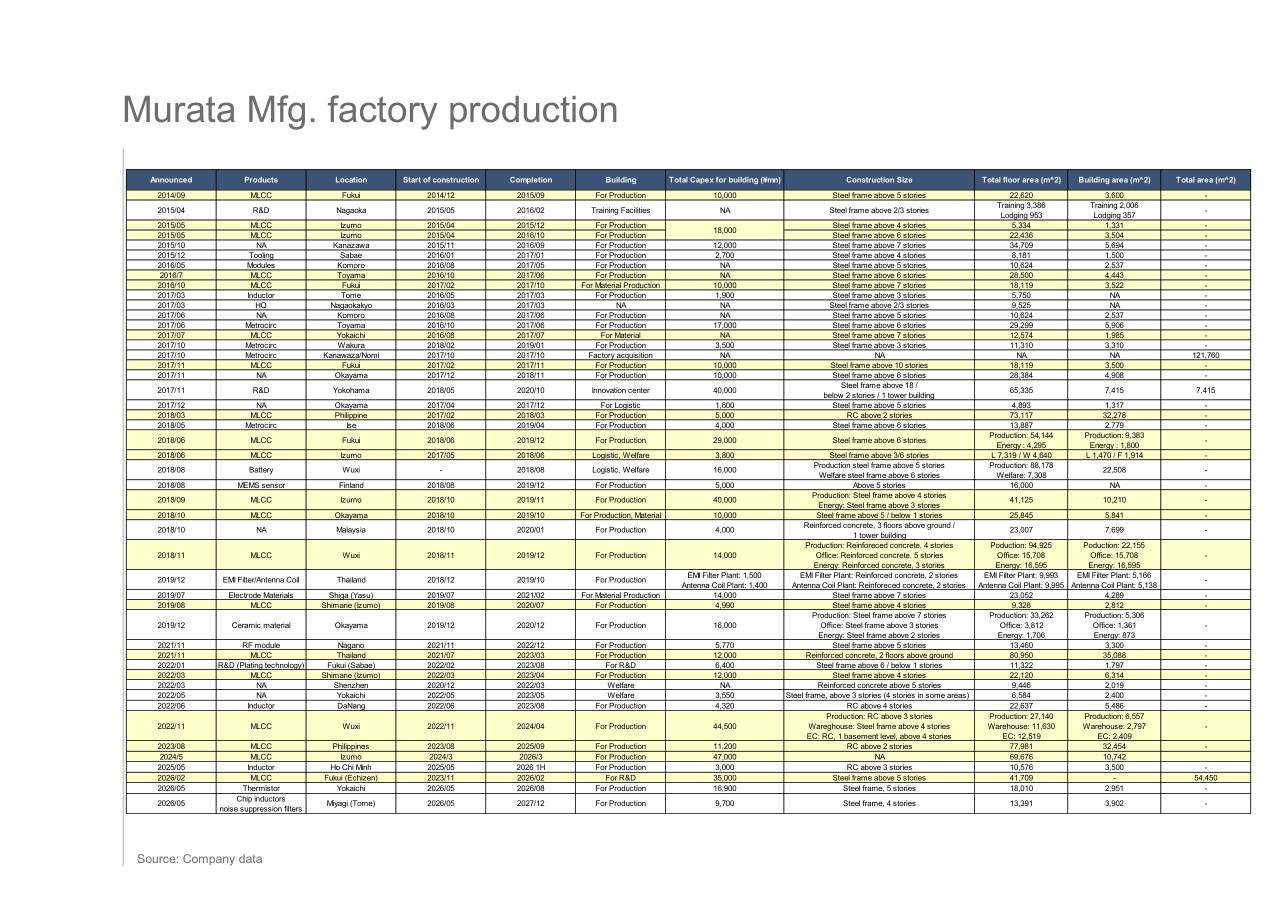
Page 18 · Murata 工厂建设与资本开支明细
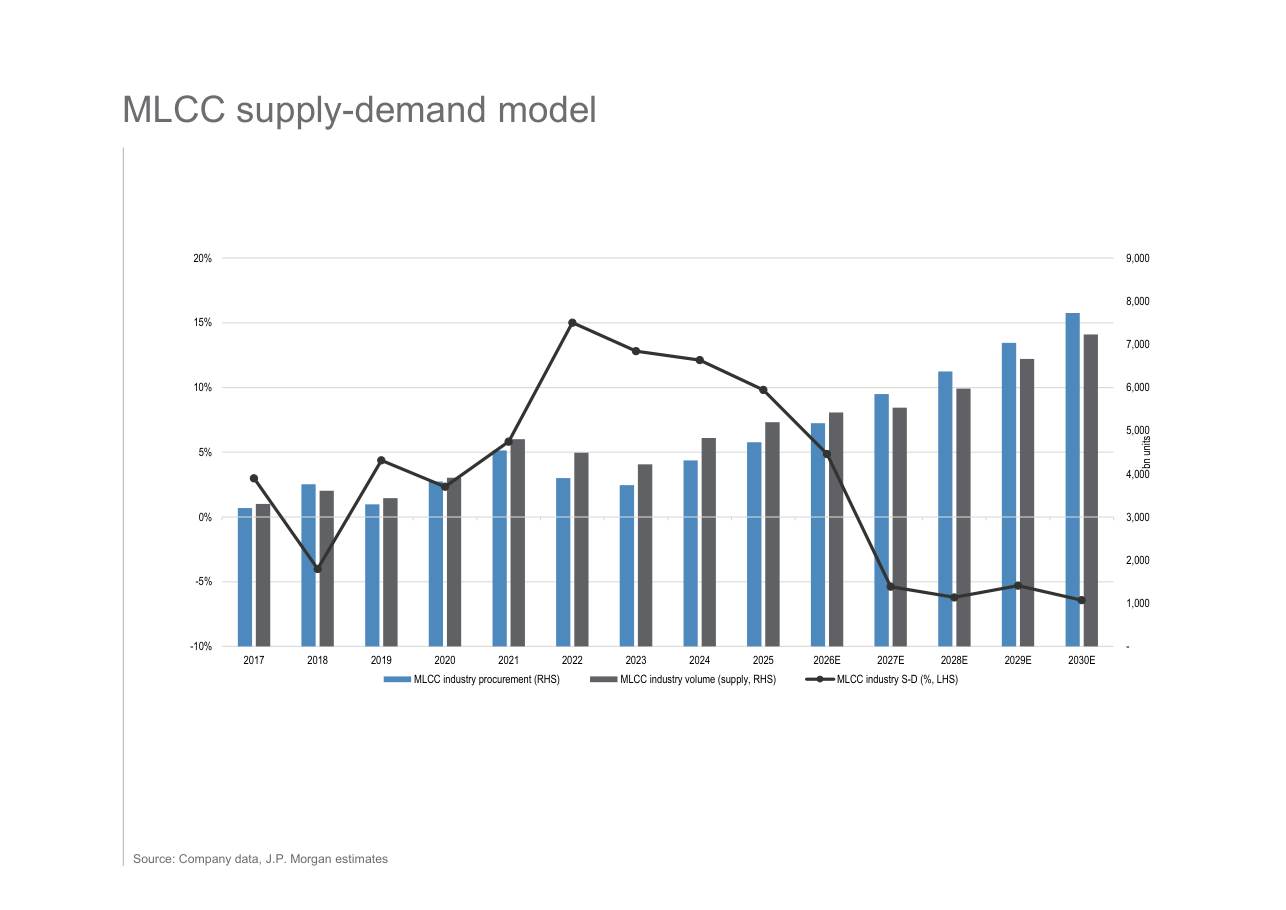
Page 19 · MLCC 供需平衡模型(2017–2030E)
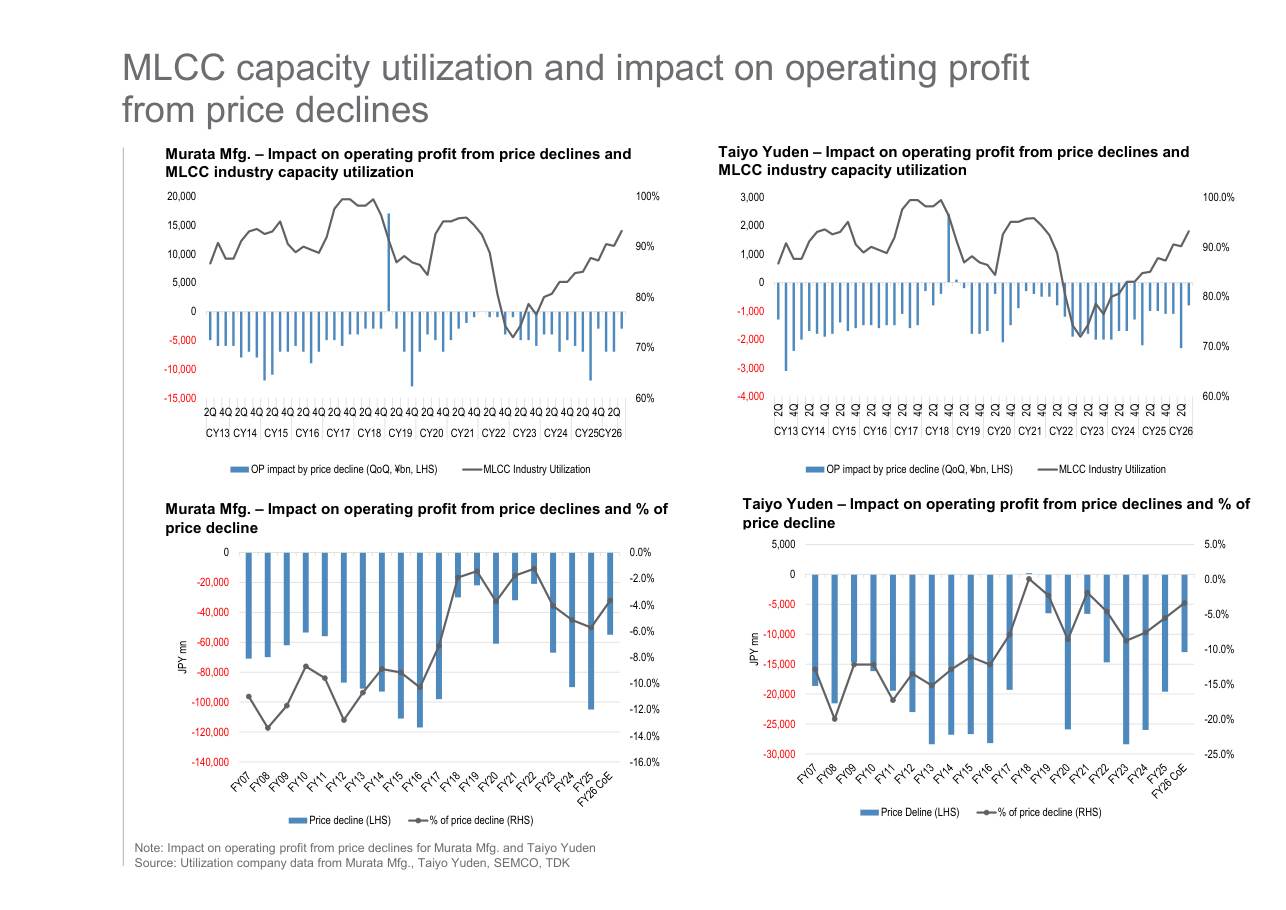
Page 20 · 稼动率与降价对营业利润的冲击(Murata / 太阳诱电)
AI 服务器:MLCC 需求的跃迁
本手册的核心章节。从 AI 加速器 TDP 路线图出发,推导单机架 MLCC 用量与容量、新一代产品(侧面成型)的成本与利润率结构,最终落到三大厂的利润预测。
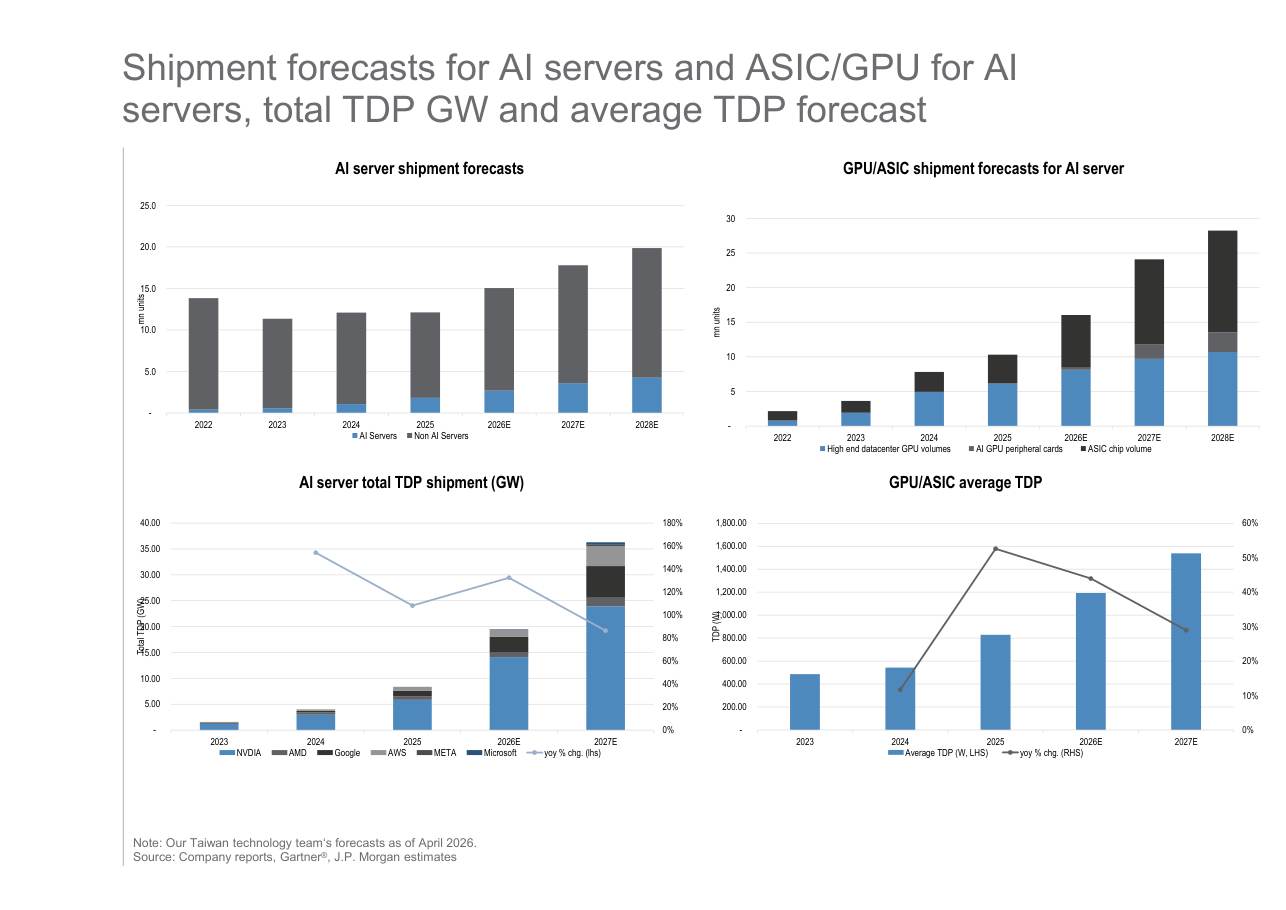
Page 21 · AI 服务器与 GPU/ASIC 出货预测、总算力 TDP(GW)
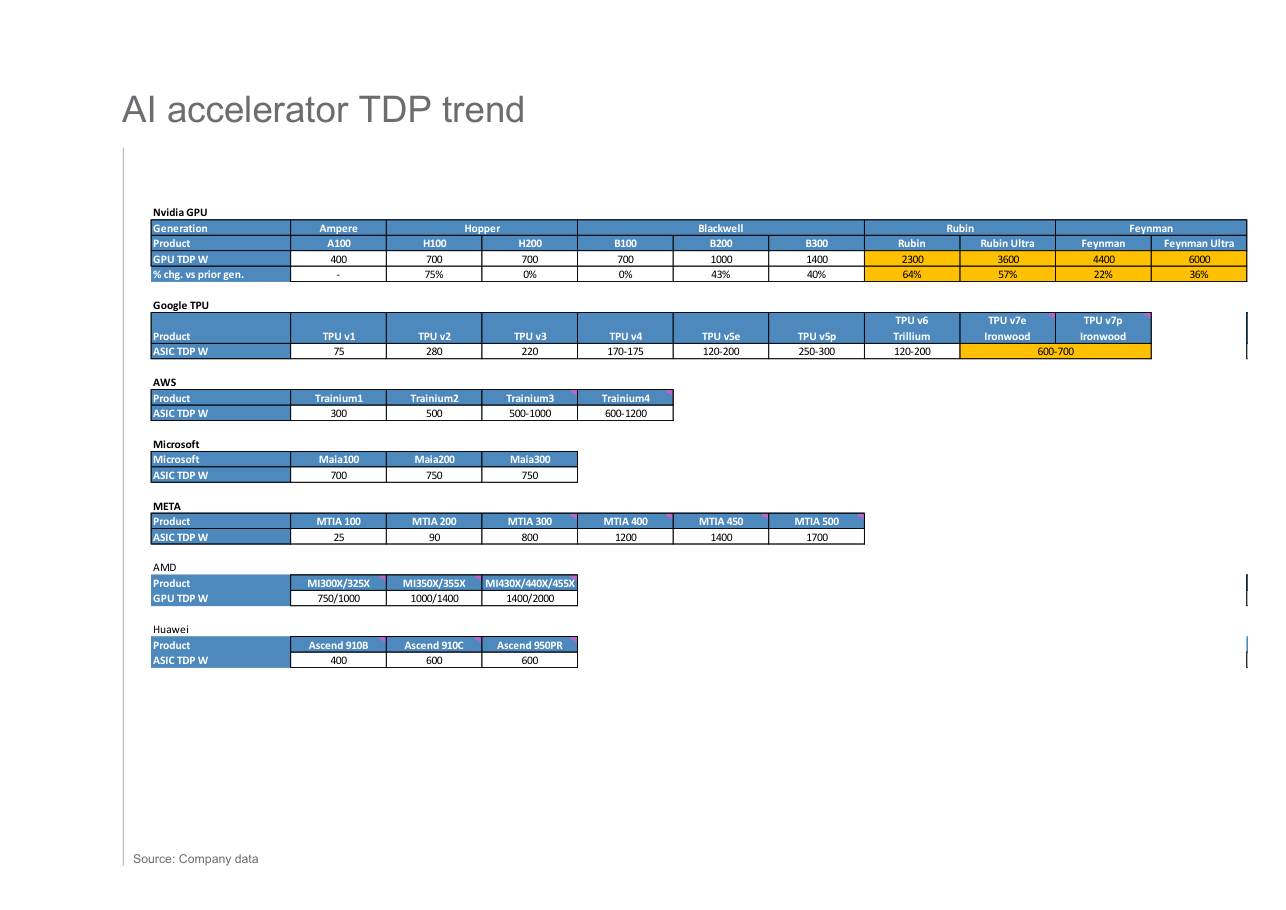
Page 22 · AI 加速器 TDP 趋势(NVIDIA / Google / AWS / Microsoft / Meta / AMD / Huawei)
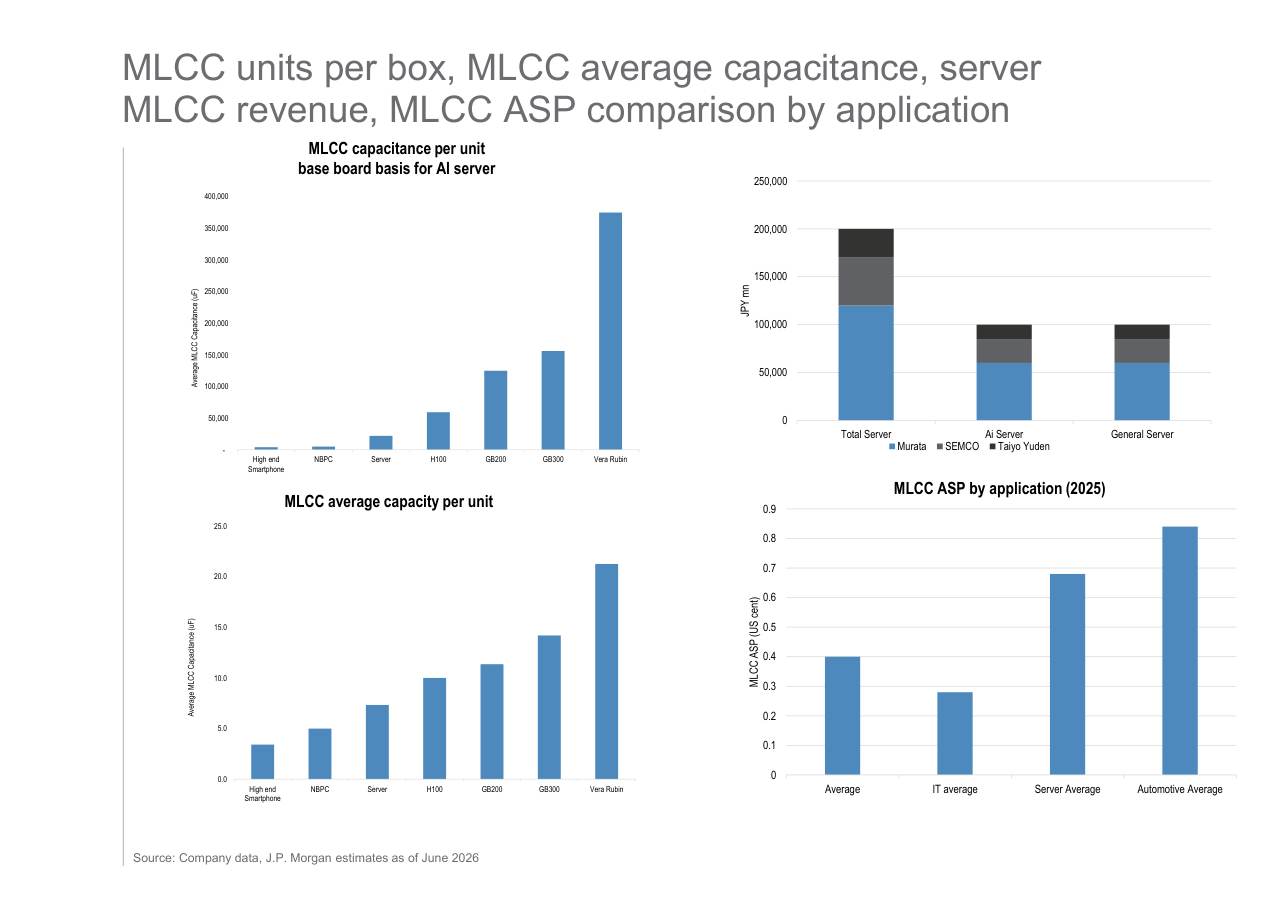
Page 23 · AI 服务器单板 MLCC 用量、平均容量、收入与 ASP 对比
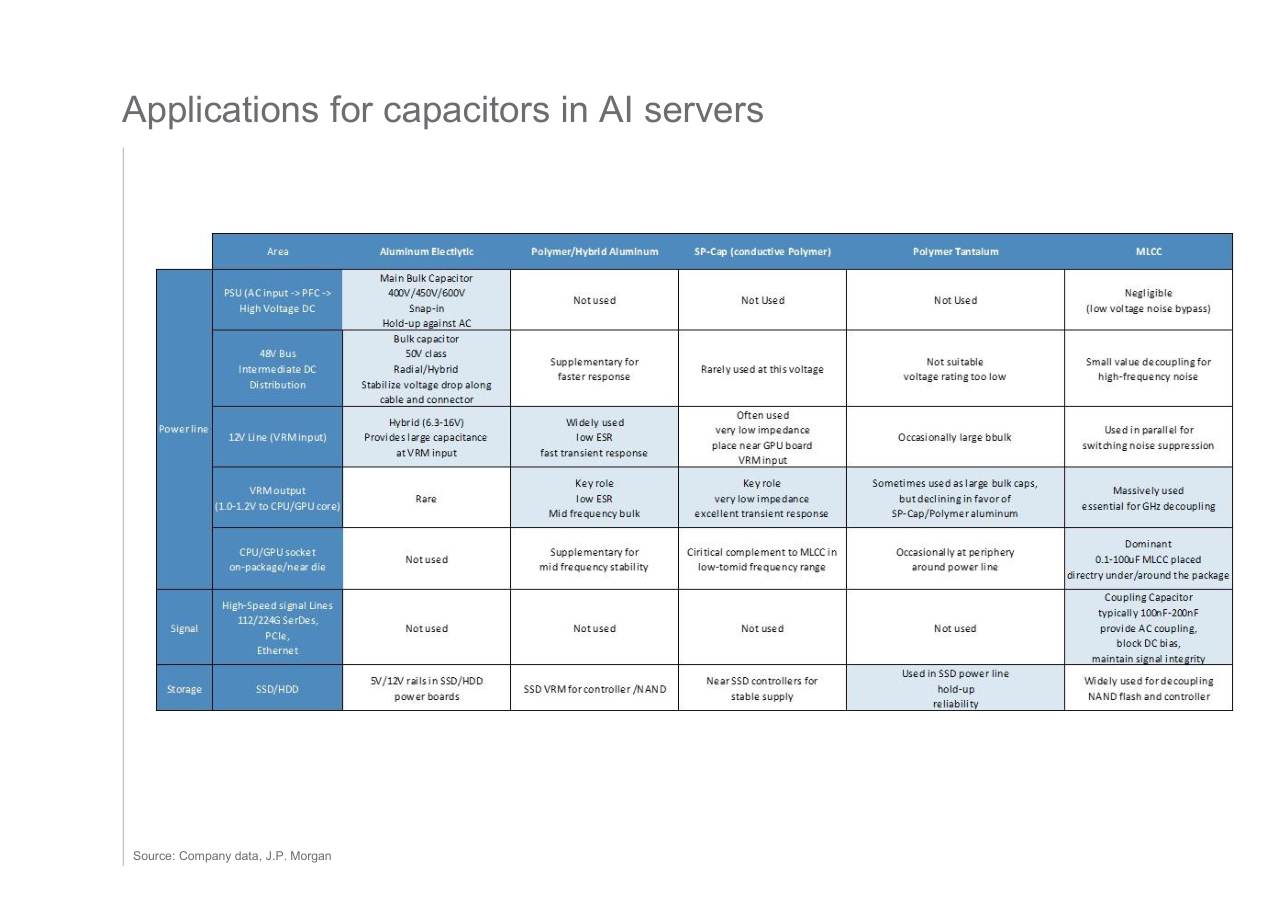
Page 24 · AI 服务器中电容的应用位置
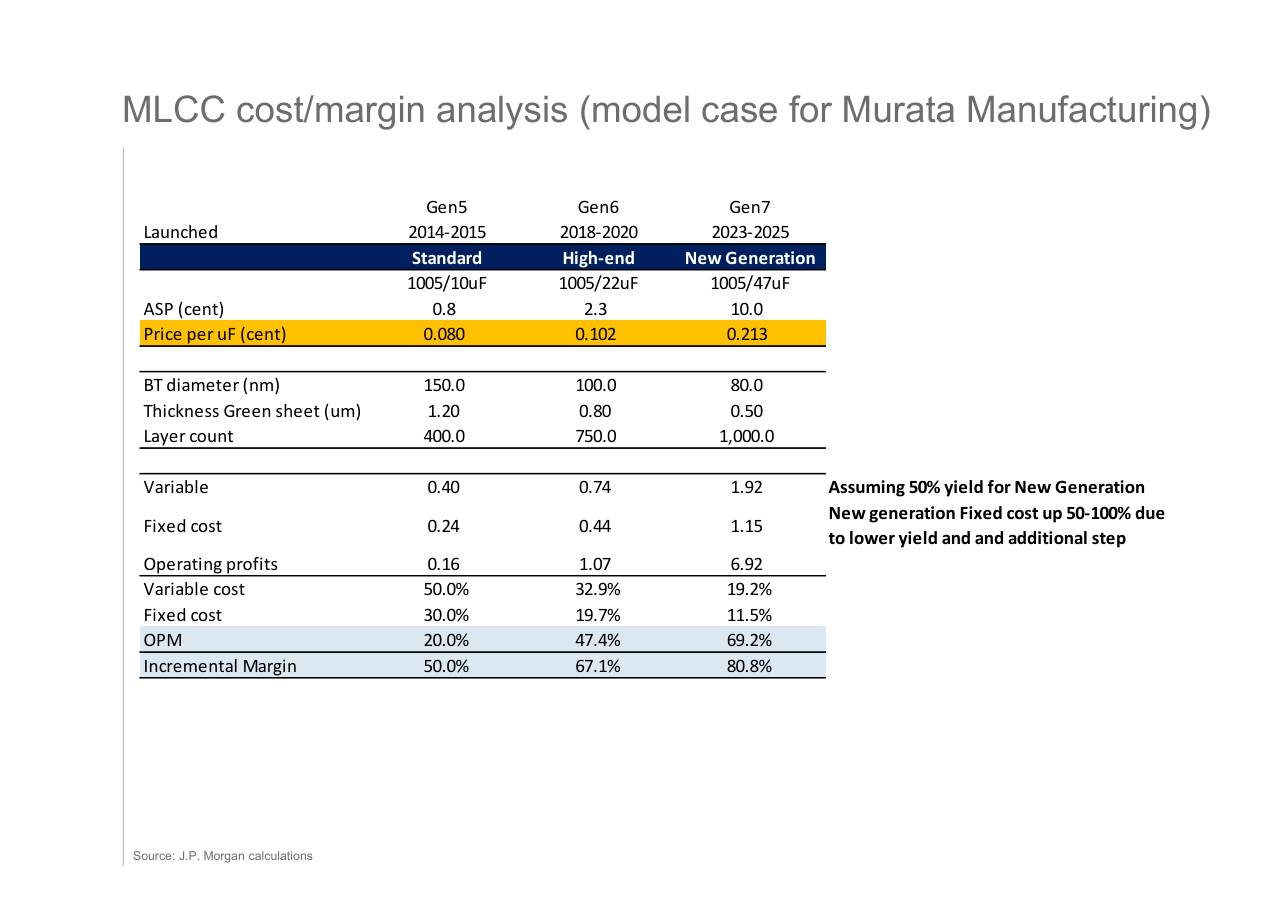
Page 25 · MLCC 成本 / 利润率分析(以 Murata 为模型案例,Gen5→Gen7)
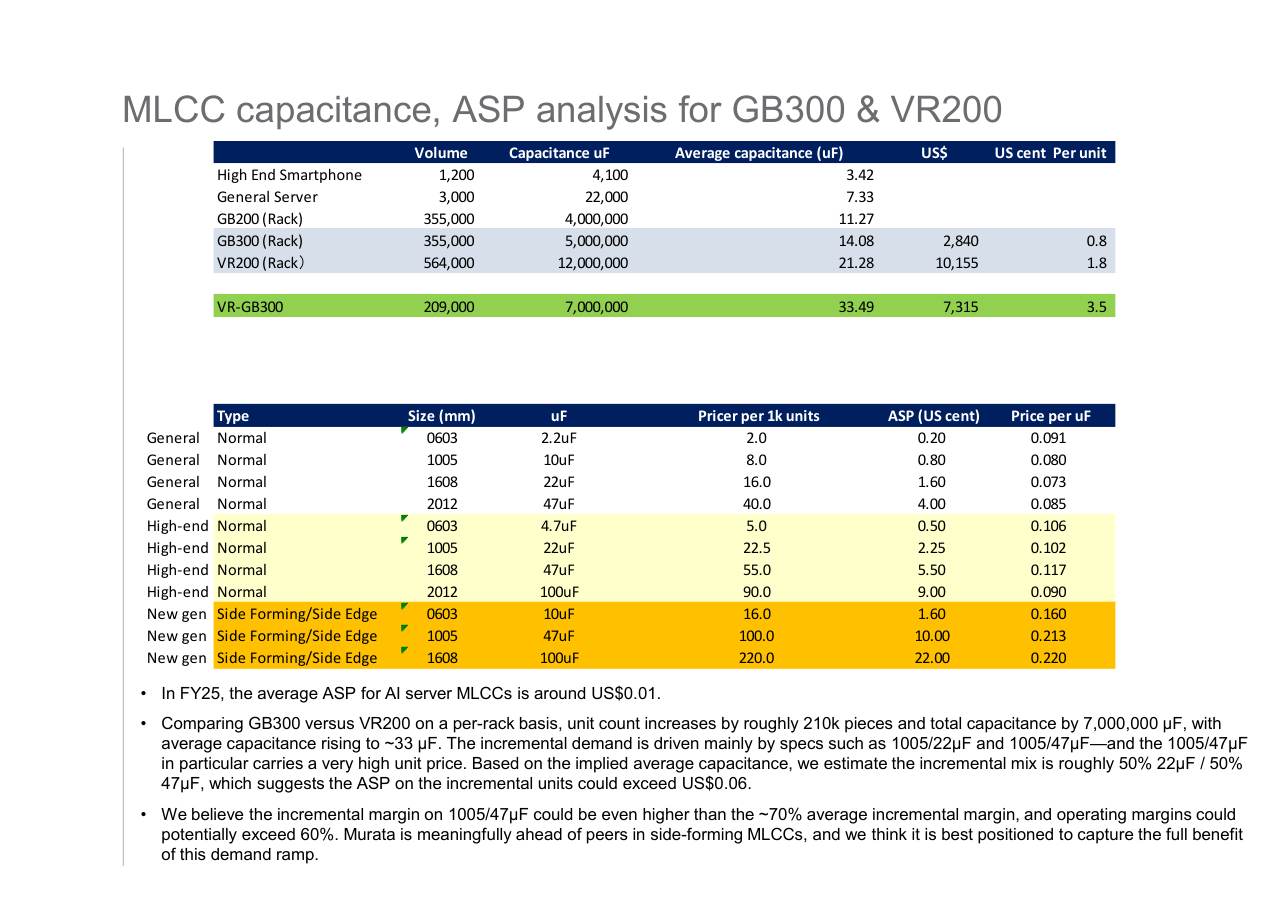
Page 26 · MLCC 容量与 ASP 分析:GB300 与 VR200
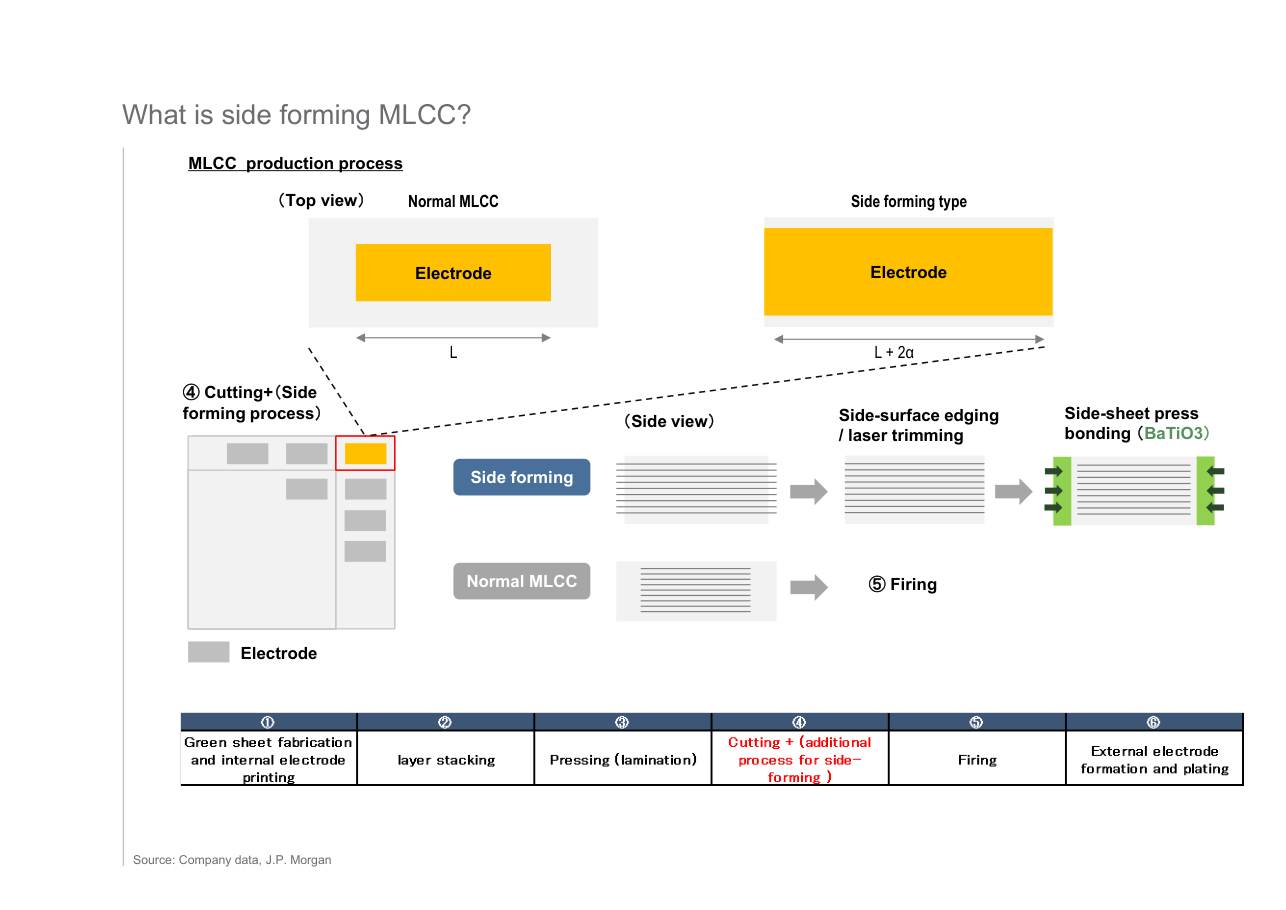
Page 27 · 什么是侧面成型(Side Forming)MLCC?
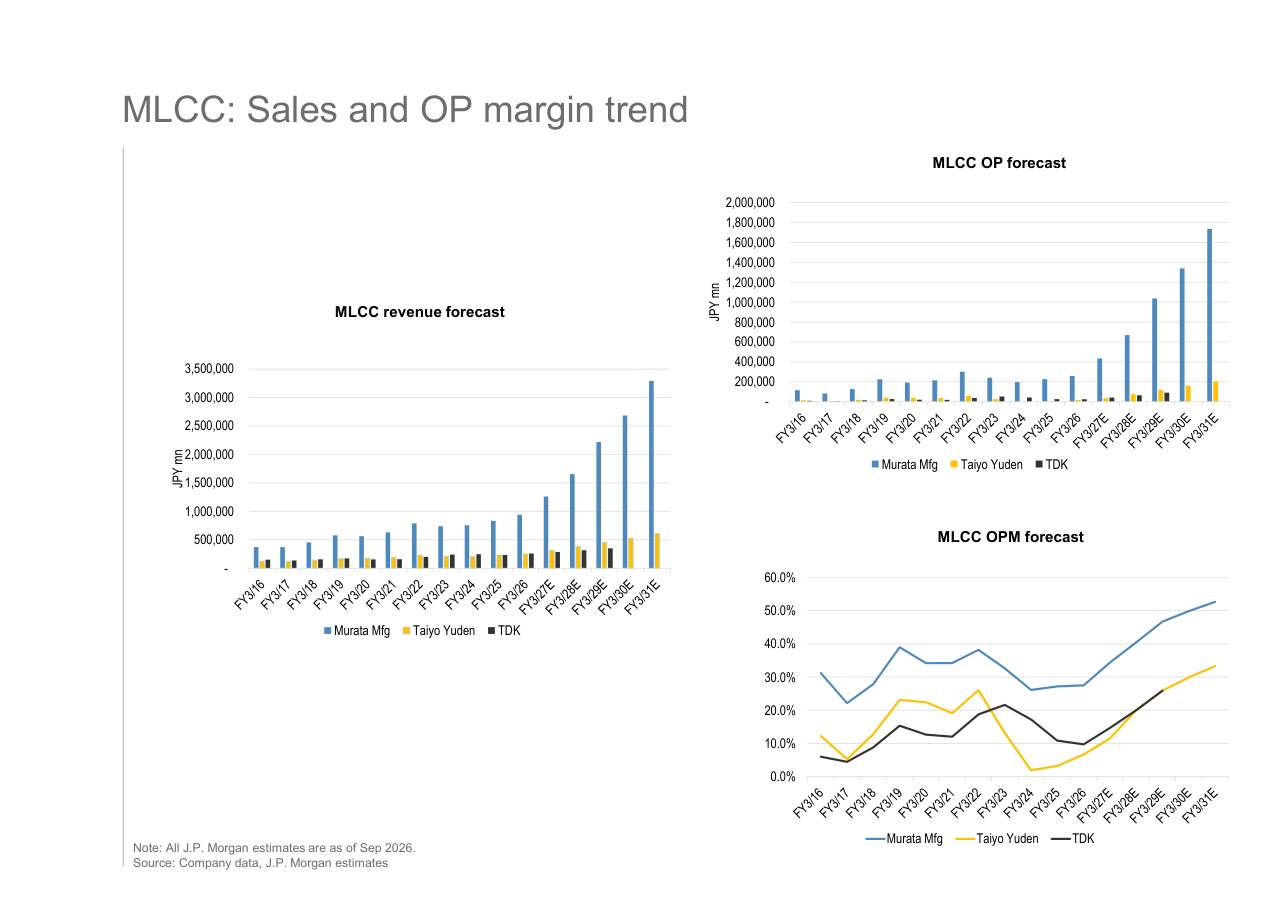
Page 28 · MLCC:销售额与营业利润率趋势(Murata / 太阳诱电 / TDK)
封装基板:Ibiden 与 AI 基板
同一枚硬币的封装端:AI GPU / ASIC 的基板面积与层数暴涨,带来的 ABF 载板与 SAP(半加成工艺)需求,以及 Ibiden 的产能如何在 Intel / NVIDIA / AMD 之间再分配。
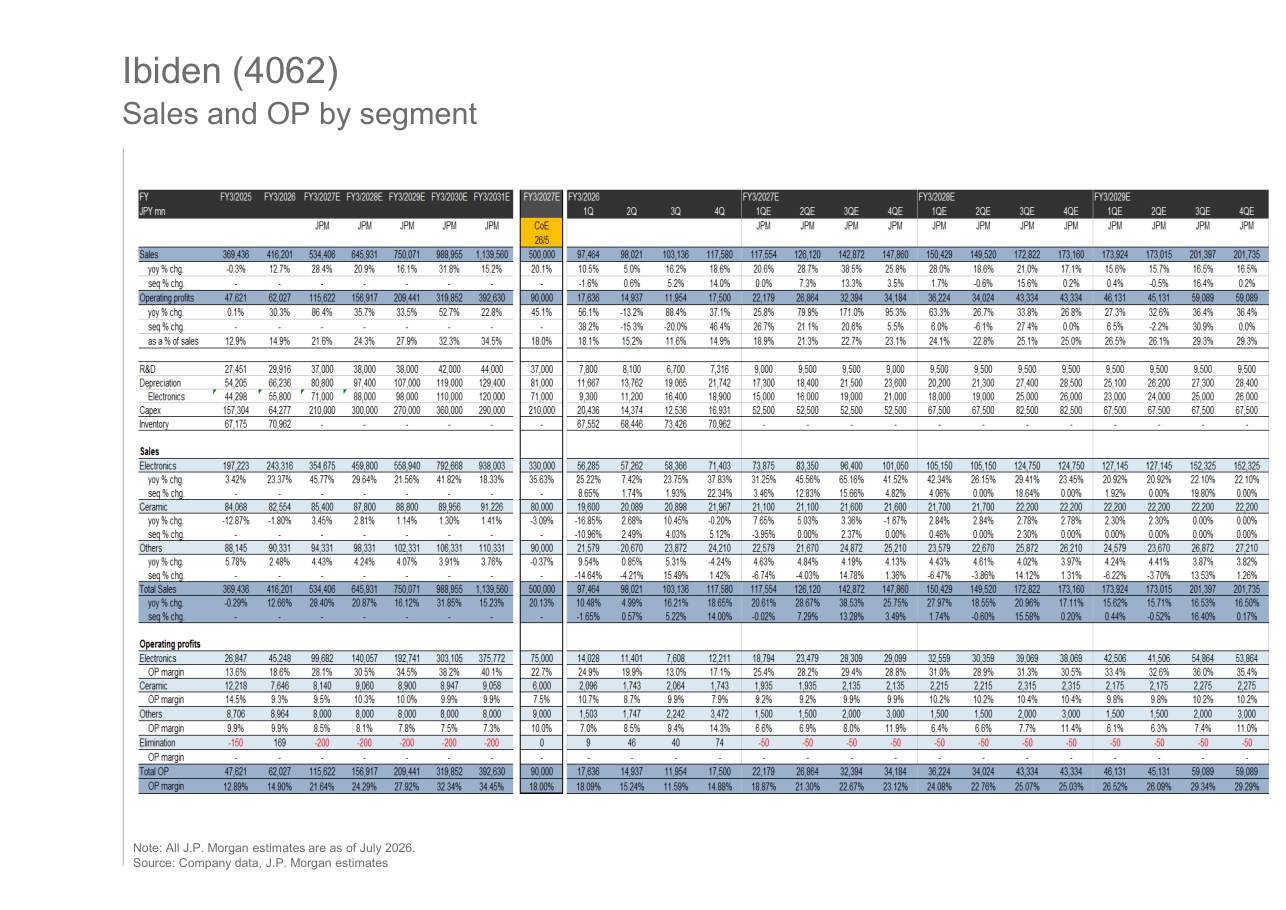
Page 29 · Ibiden(4062):分部销售额与营业利润
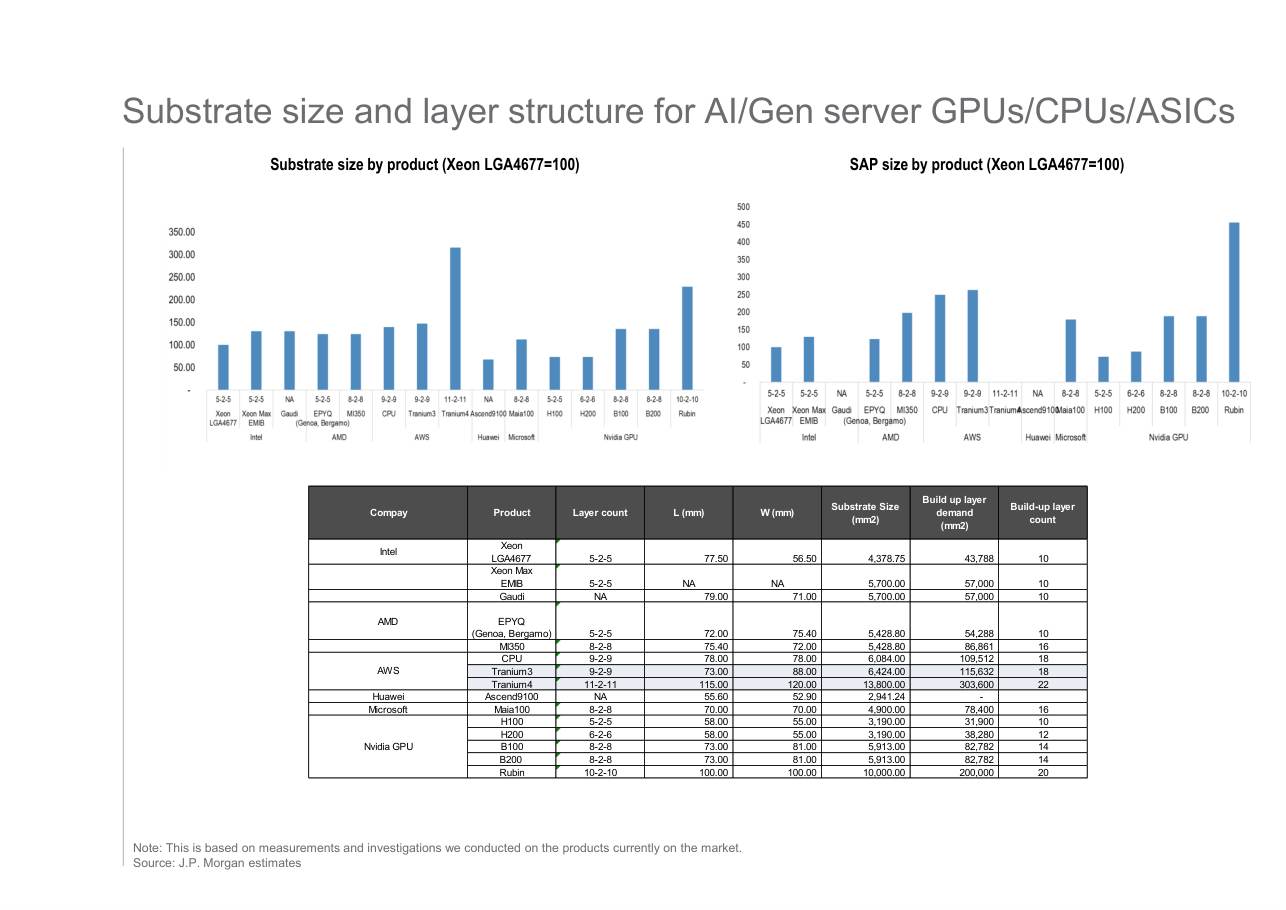
Page 30 · AI / 通用服务器 GPU / CPU / ASIC 的基板尺寸与层数结构
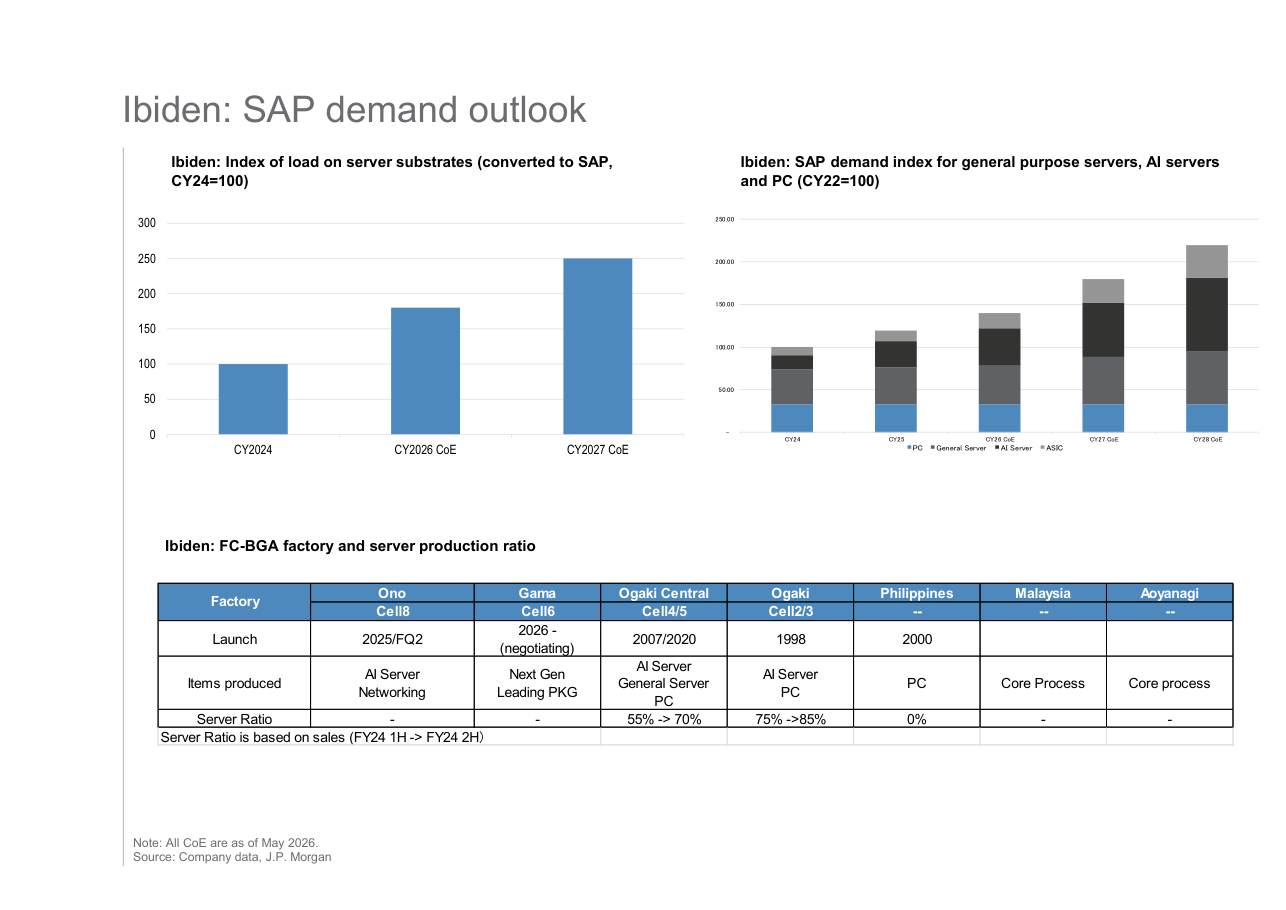
Page 31 · Ibiden:SAP 需求展望与服务器占比
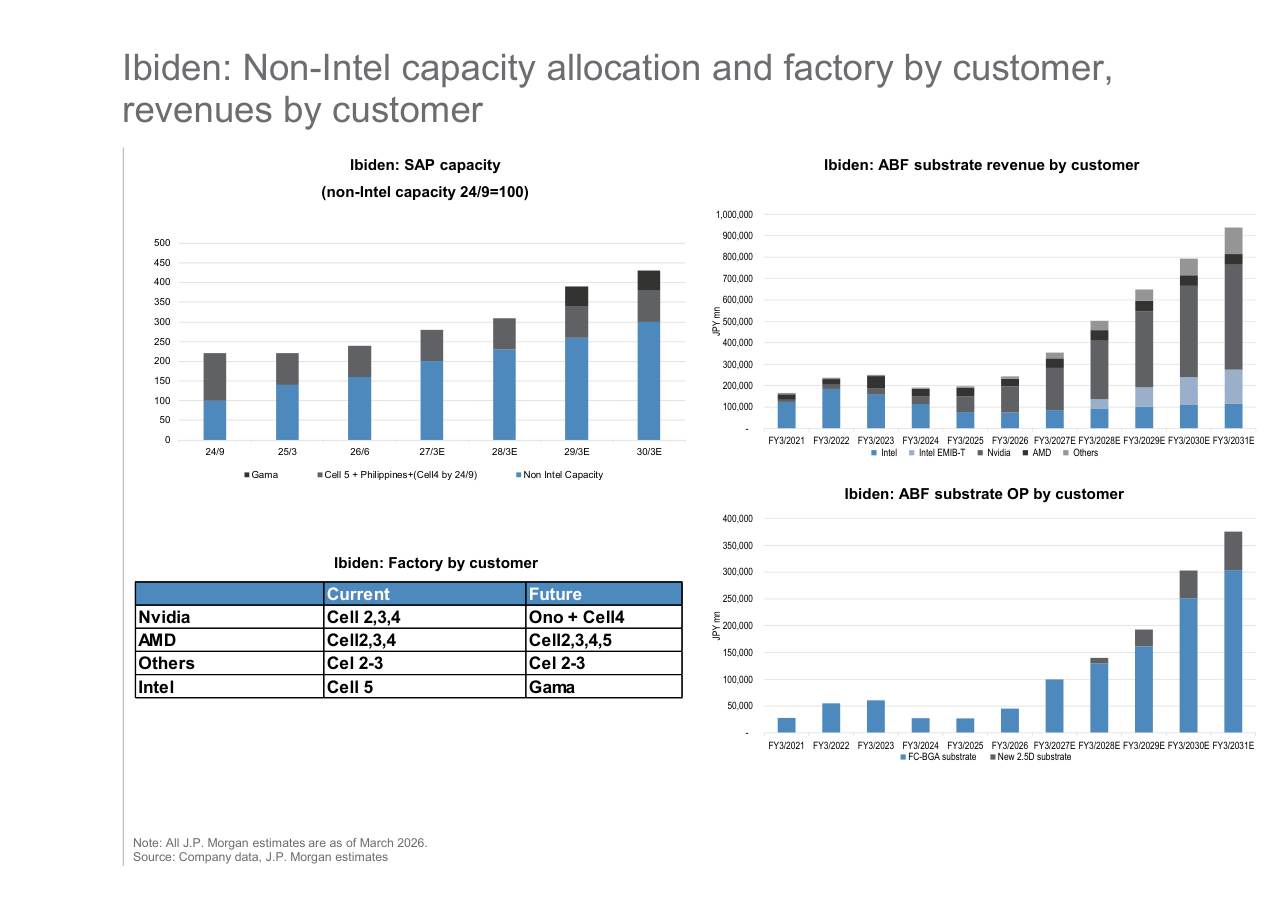
Page 32 · Ibiden:非 Intel 产能分配、客户与工厂对应、ABF 收入拆分
公司页
手册后半部分是个股数据页,每页给出分部销售额 / 营业利润及关键应用的预测拆分。此处按公司归组呈现。
Niterra(5334)
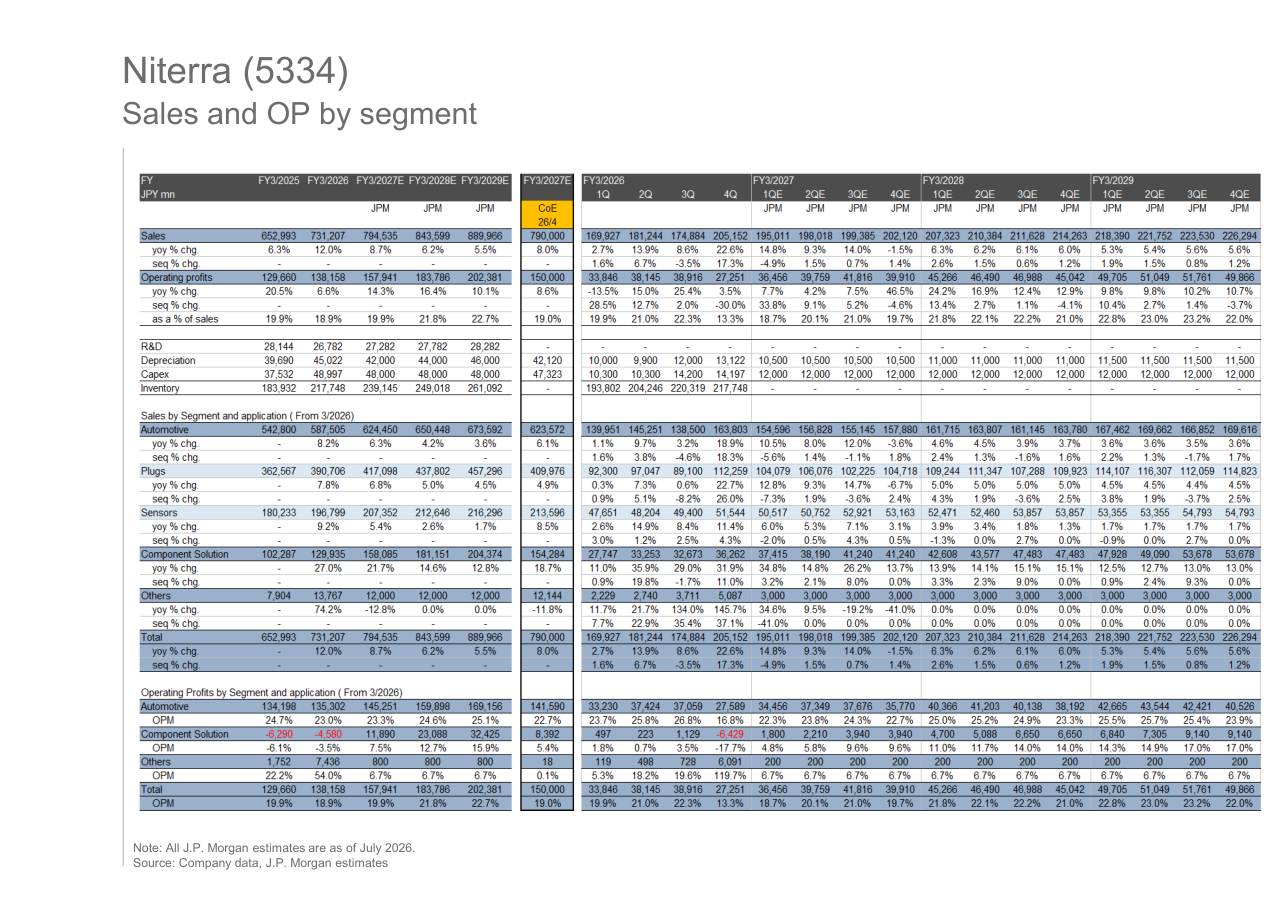
Page 33 · Niterra(5334):分部销售额与营业利润
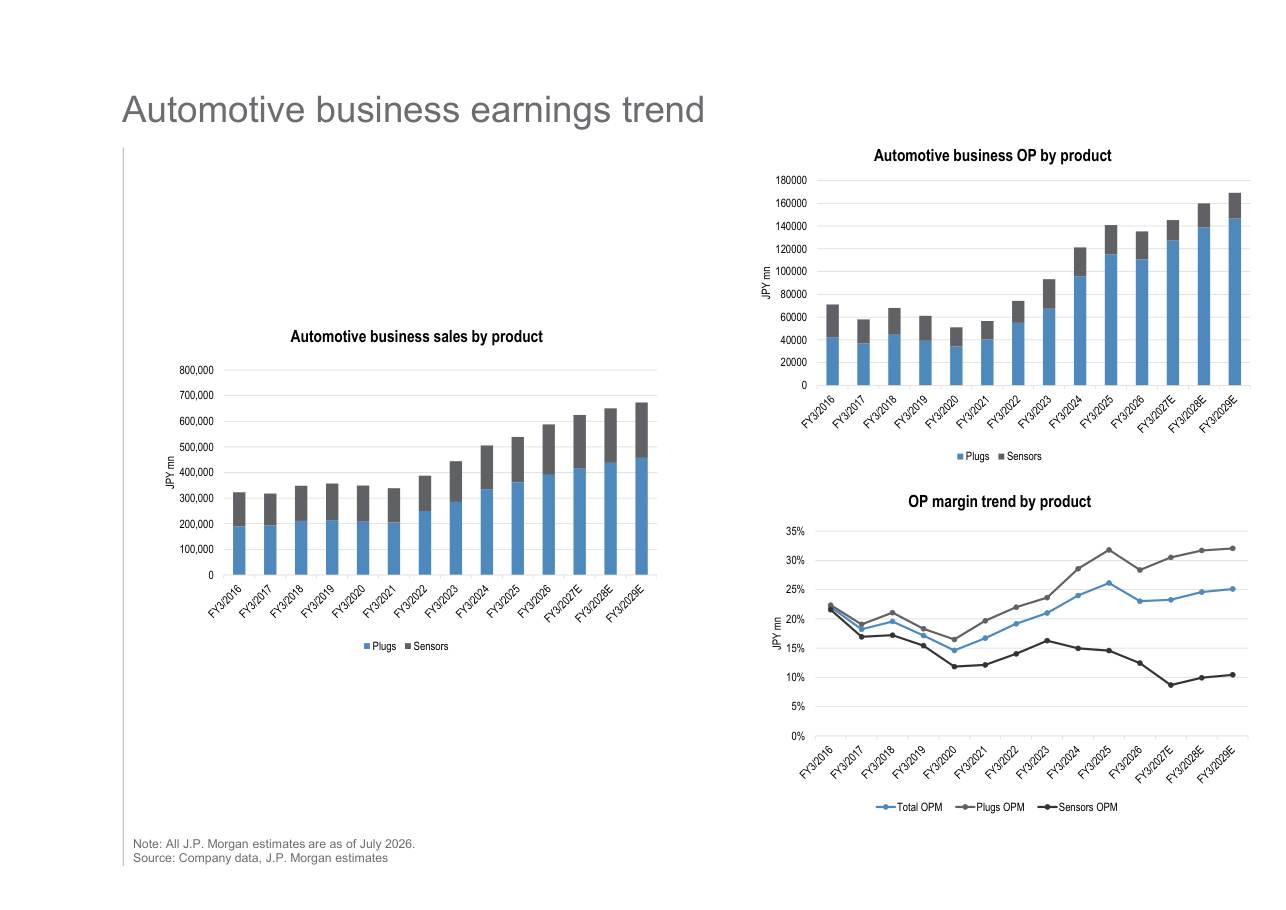
Page 34 · Niterra:汽车业务盈利趋势与产品拆分
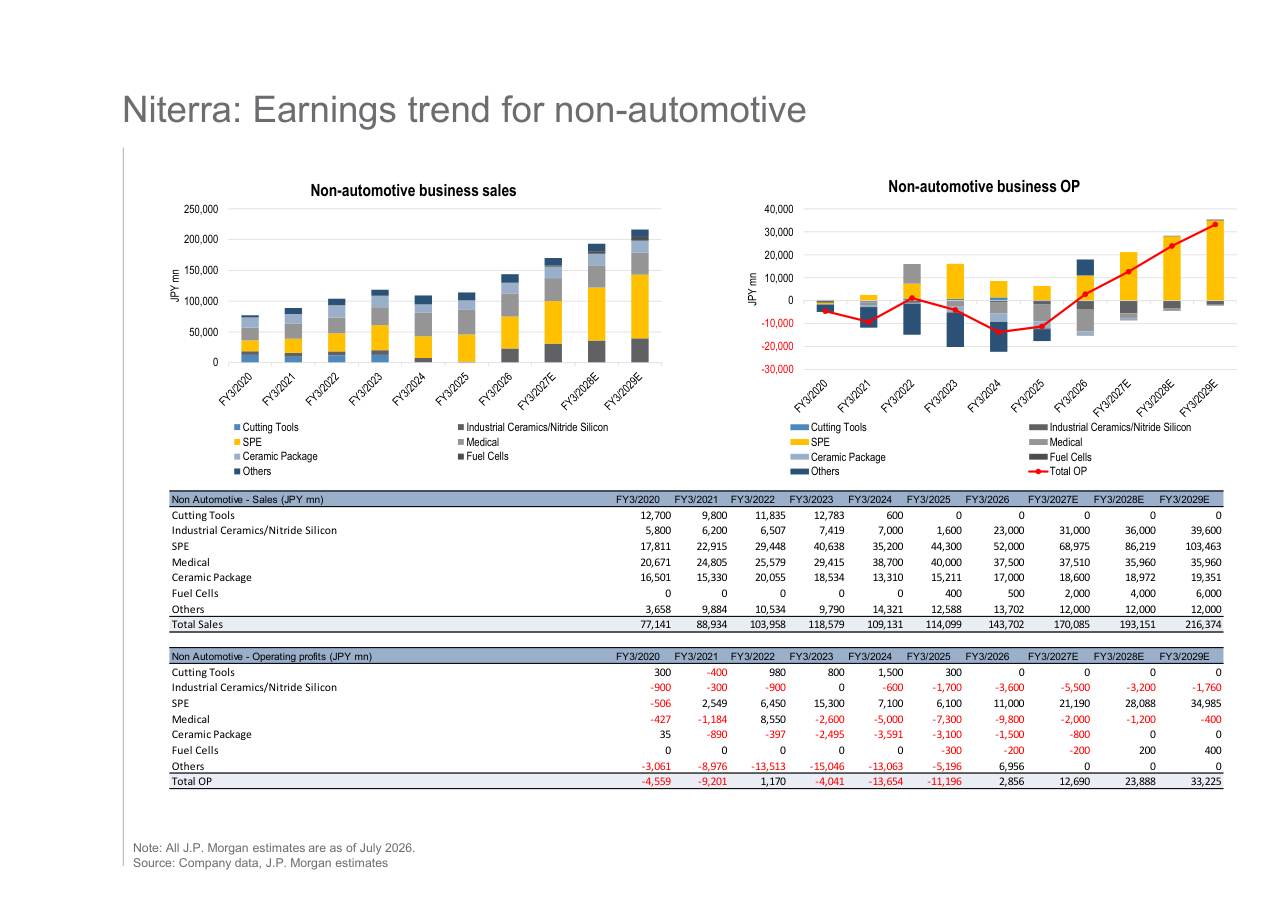
Page 35 · Niterra:非汽车业务(工业陶瓷 / 氮化硅)盈利趋势
MinebeaMitsumi(6479)
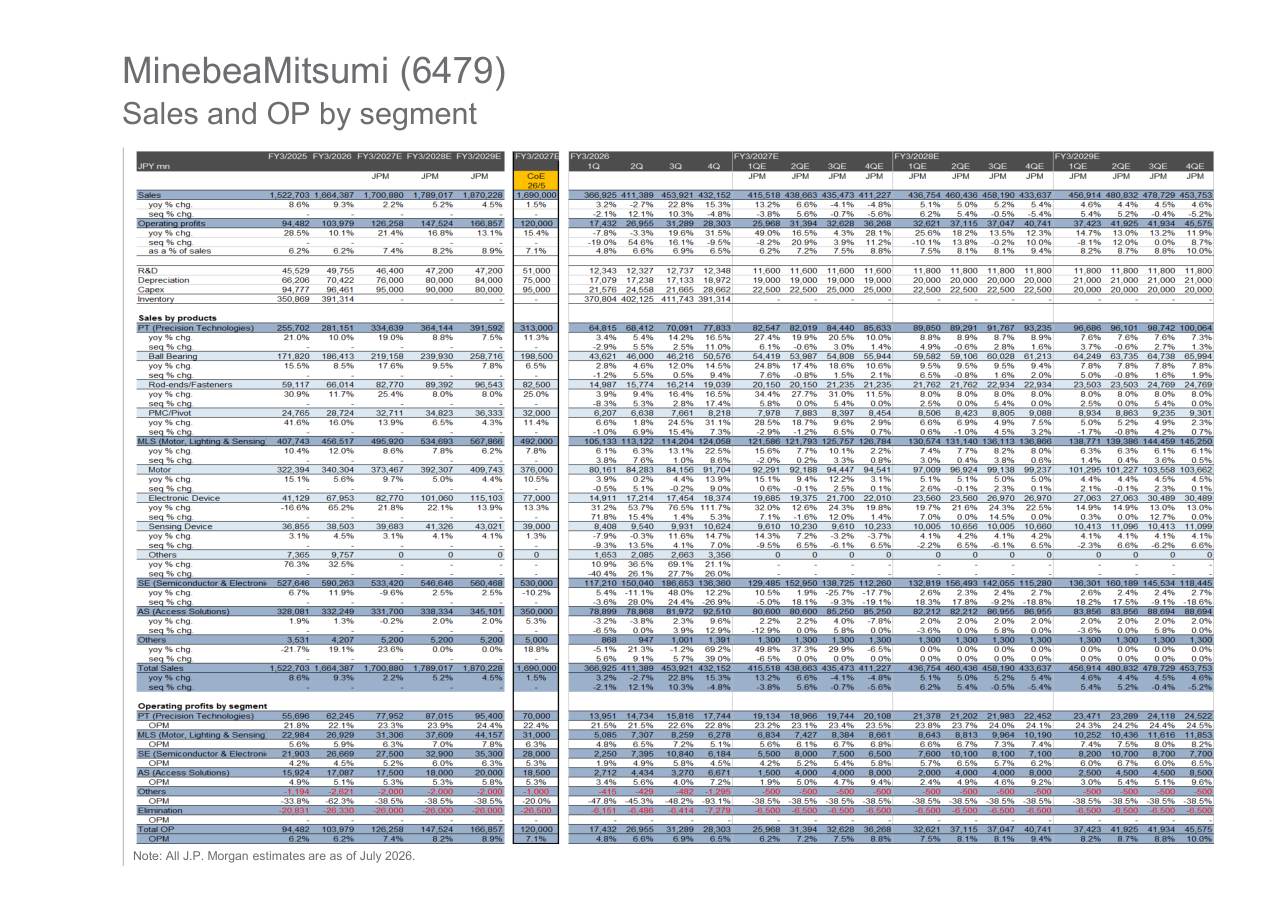
Page 36 · MinebeaMitsumi(6479):分部销售额与营业利润
Nidec(6594)
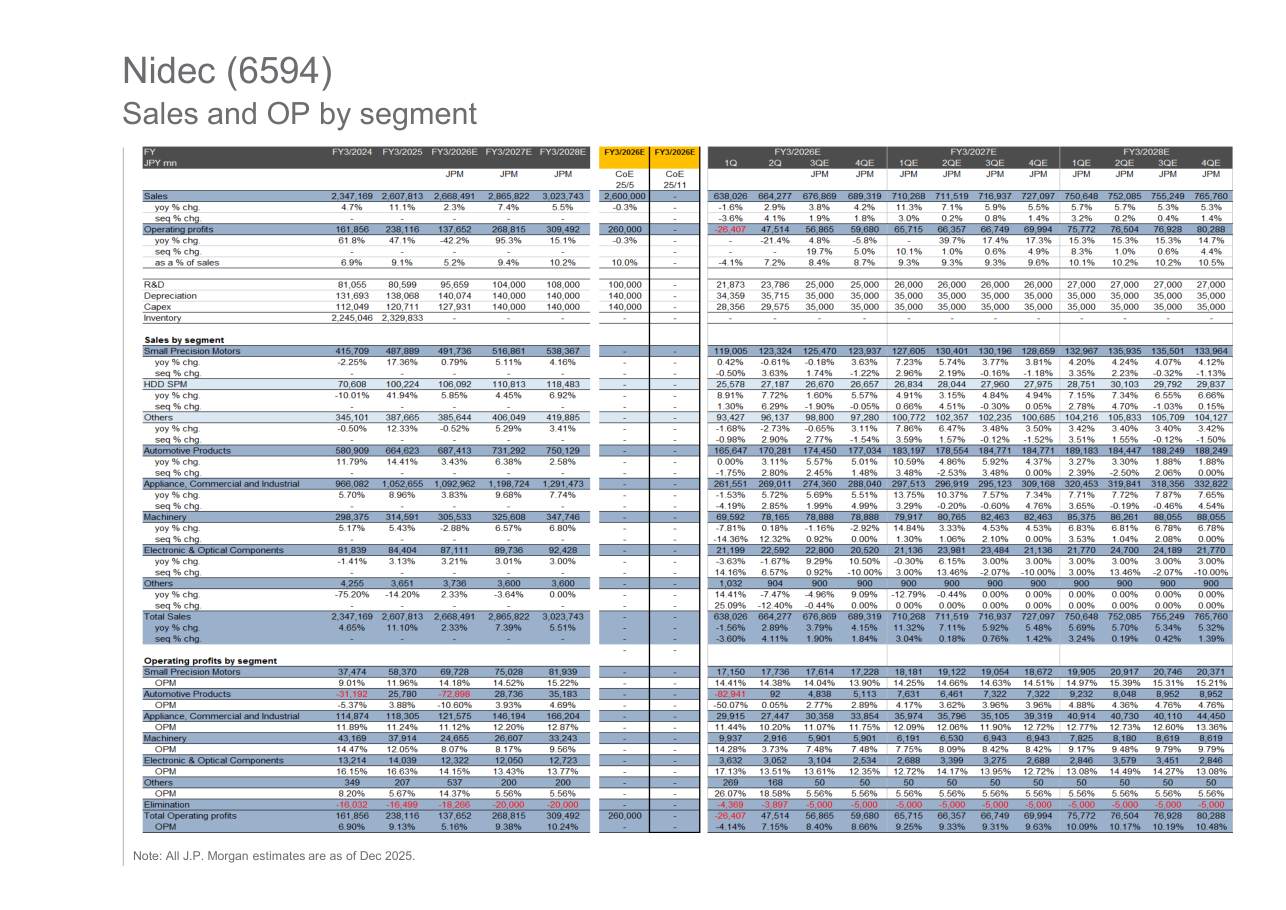
Page 37 · Nidec(6594):分部销售额与营业利润
Wacom(6727)
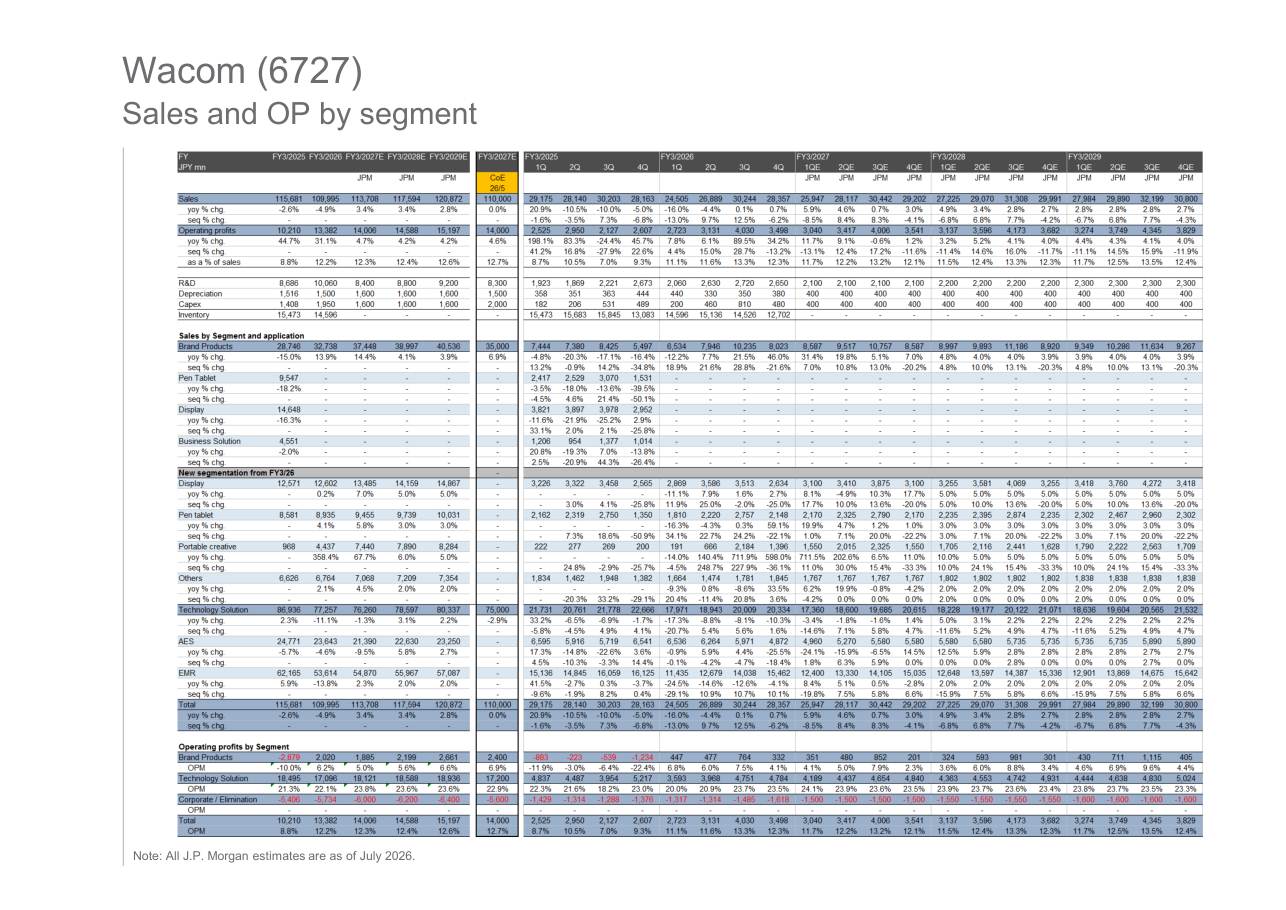
Page 38 · Wacom(6727):分部销售额与营业利润
TDK(6762)
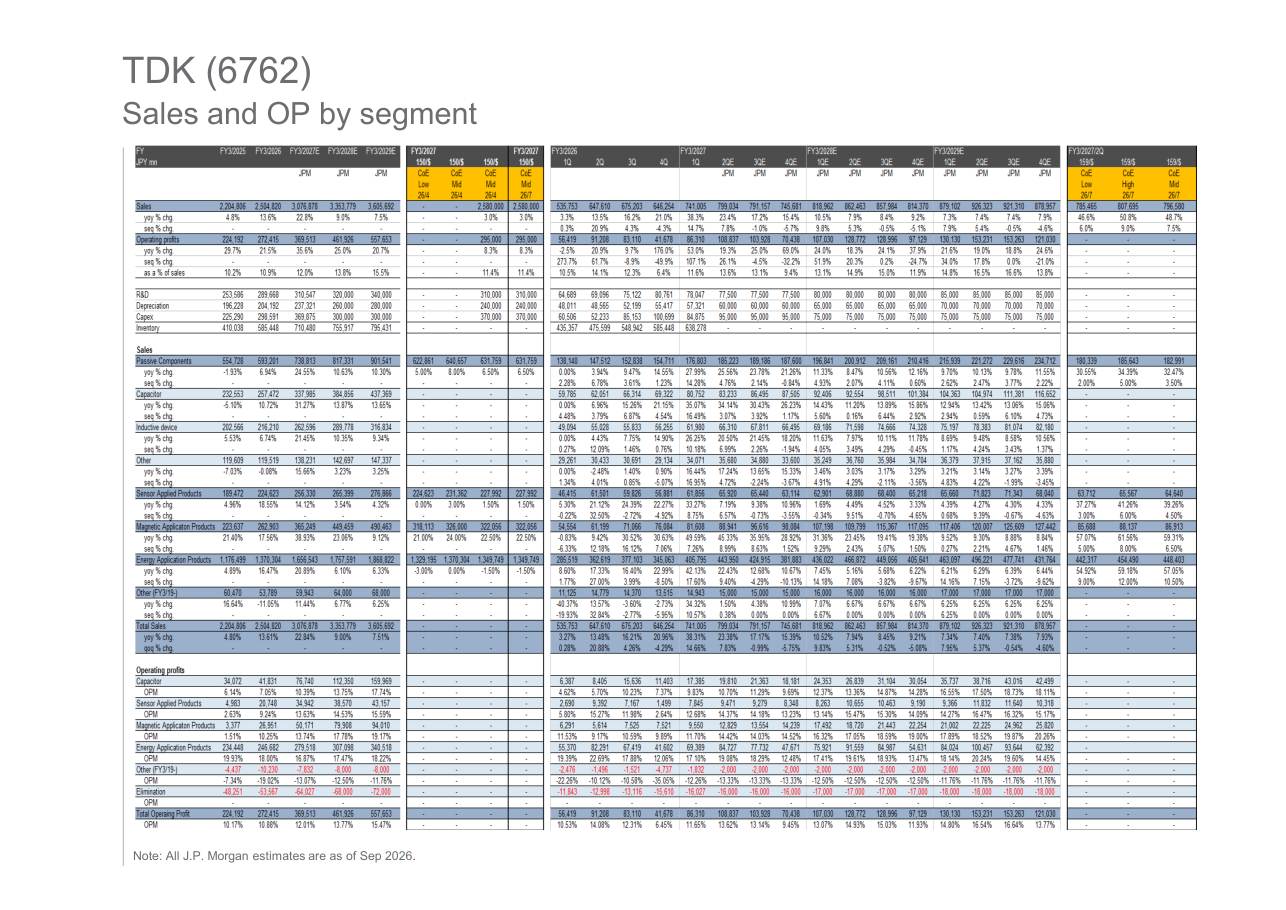
Page 39 · TDK(6762):分部销售额与营业利润
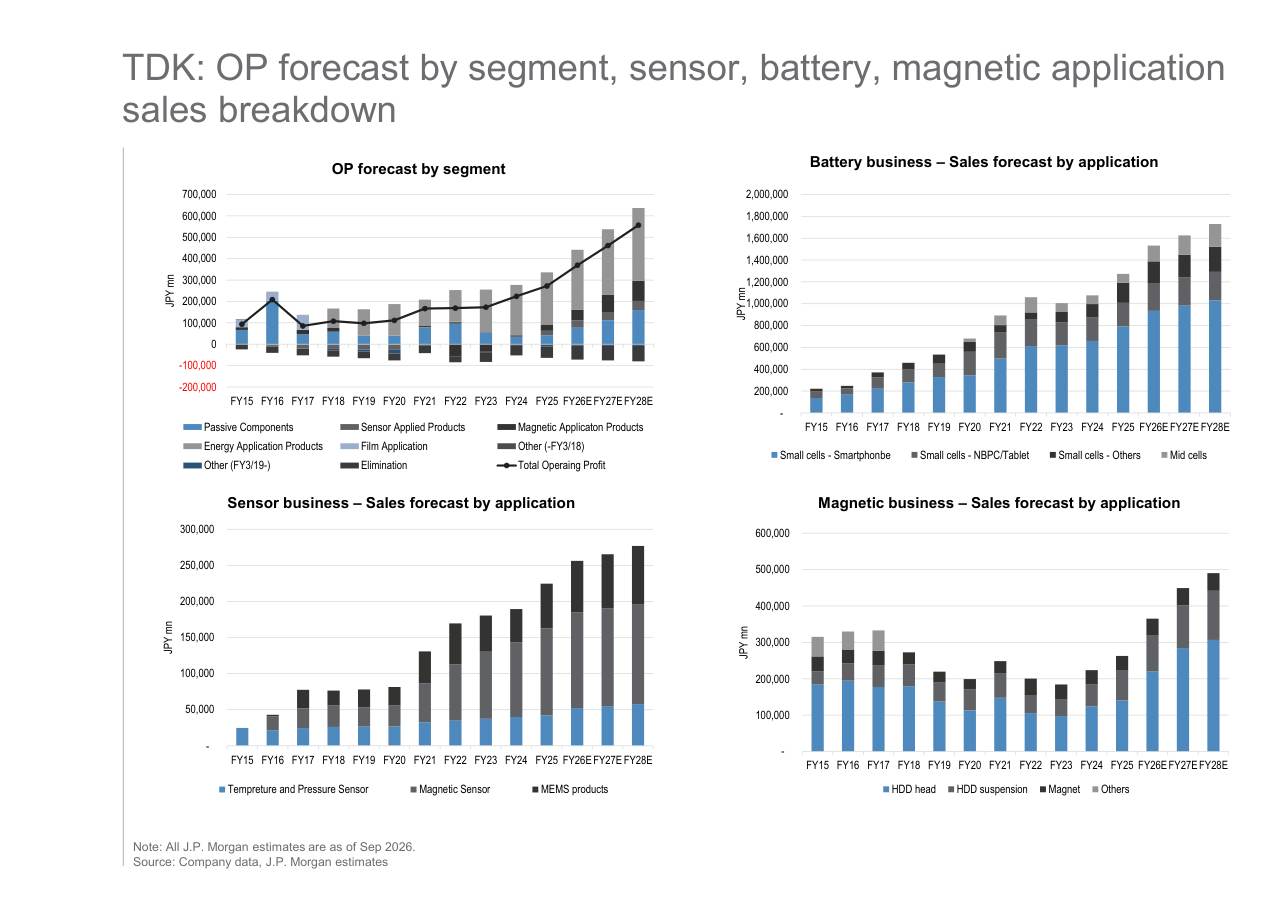
Page 40 · TDK:分部营业利润预测与传感器 / 电池 / 磁性应用拆分
Alps Alpine(6770)
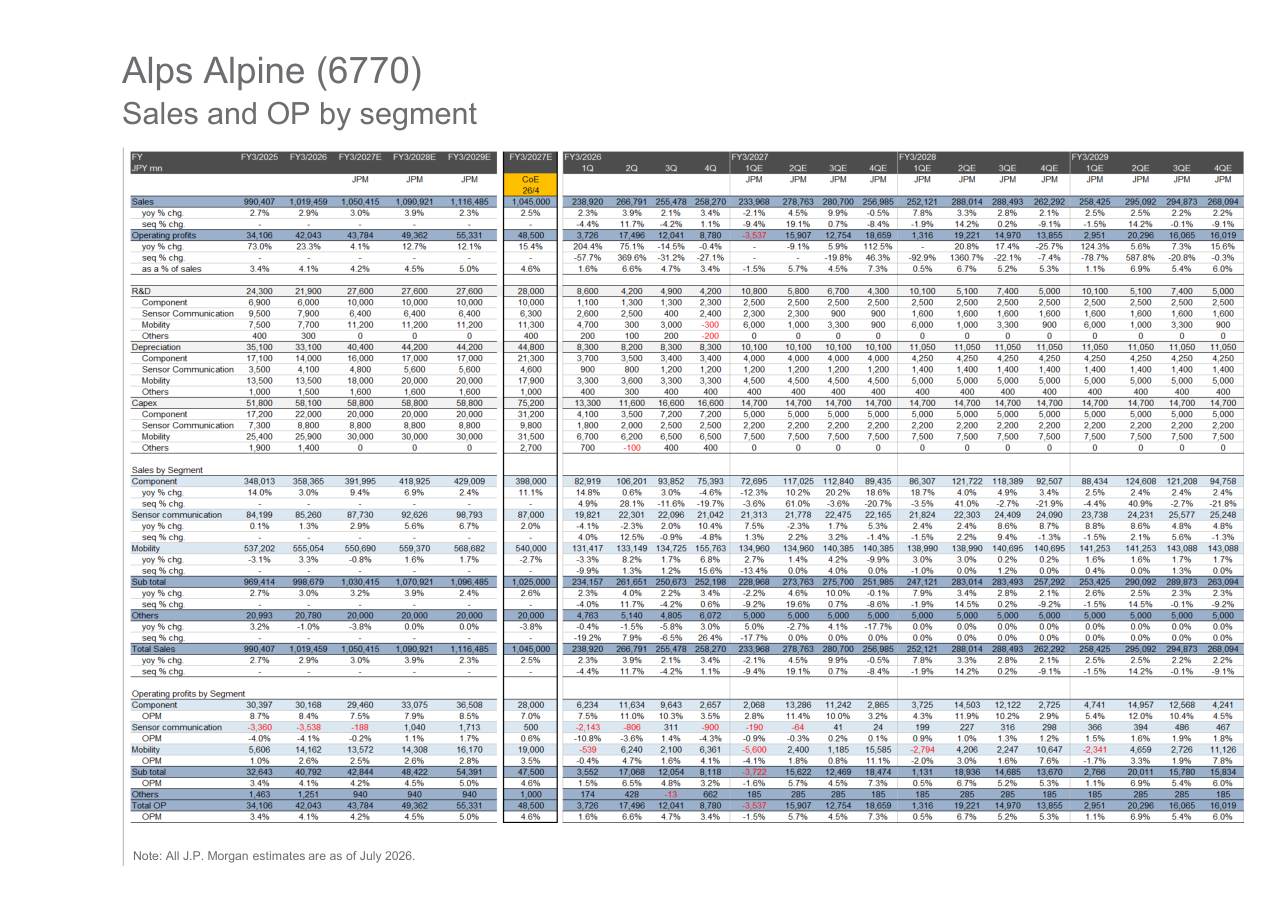
Page 41 · Alps Alpine(6770):分部销售额与营业利润
Hirose Electric(6806)
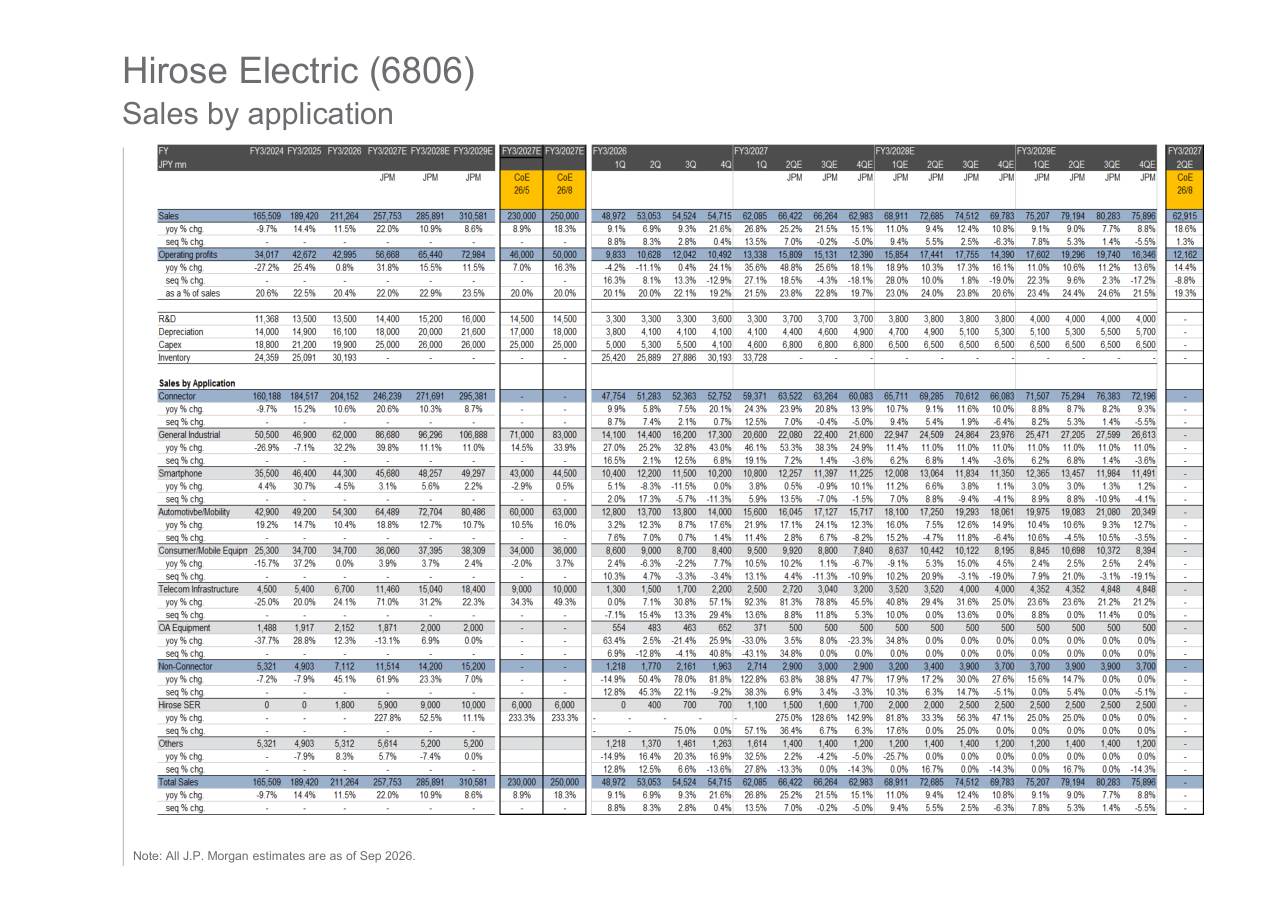
Page 42 · Hirose Electric(6806):按应用的销售额
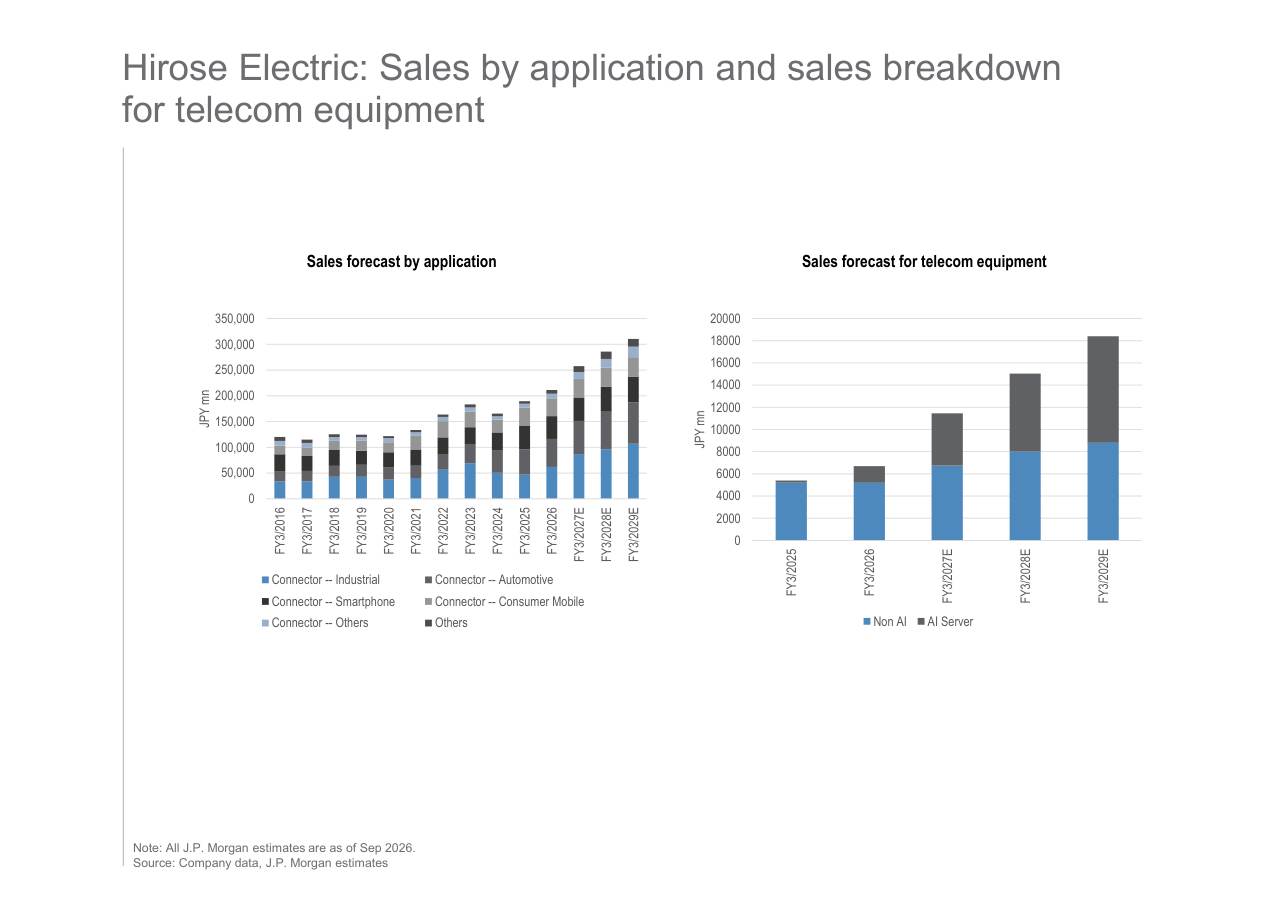
Page 43 · Hirose Electric:按应用销售额与通信设备占比
Japan Aviation Electronics(6807)
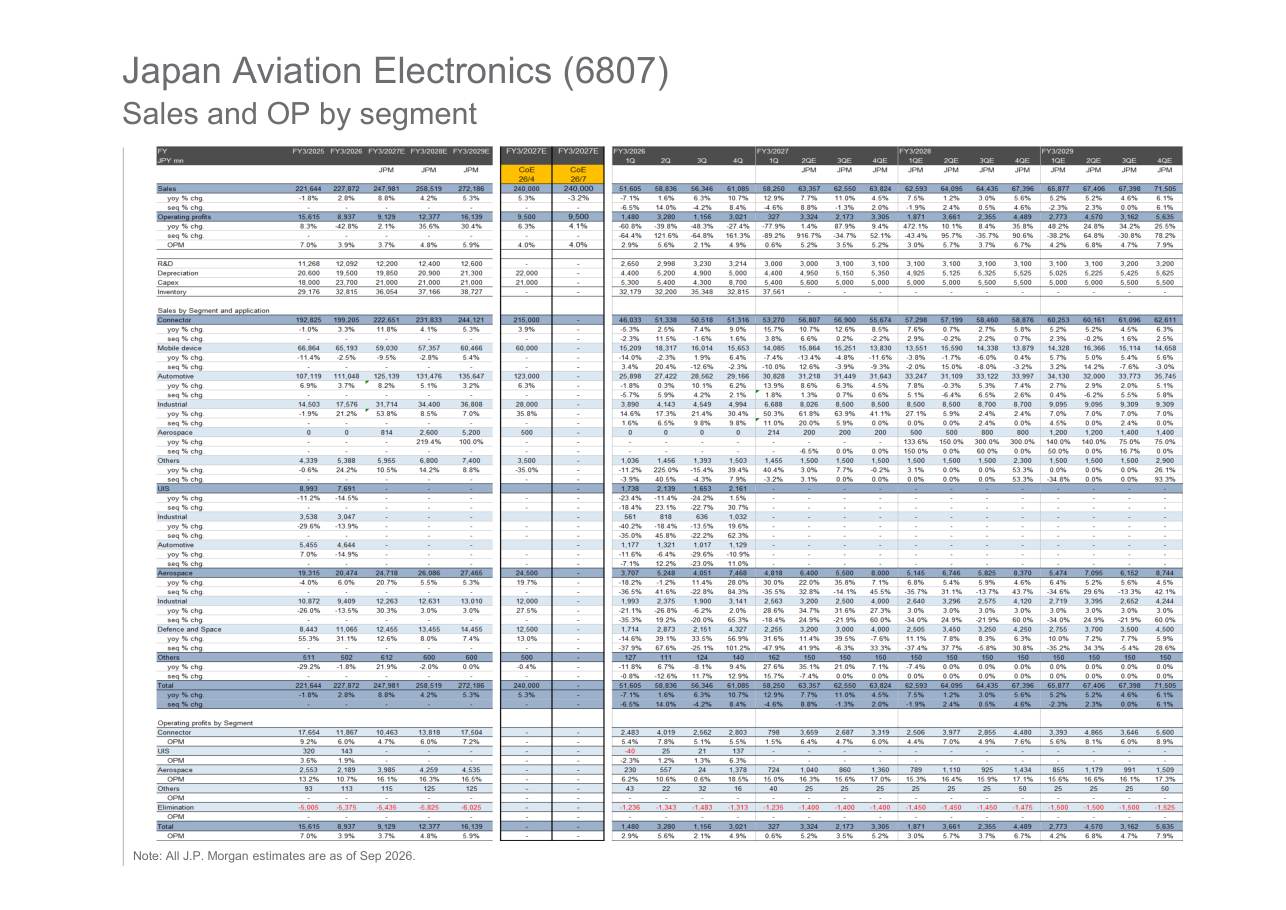
Page 44 · Japan Aviation Electronics(6807):分部销售额与营业利润
Rohm(6963)与分立器件
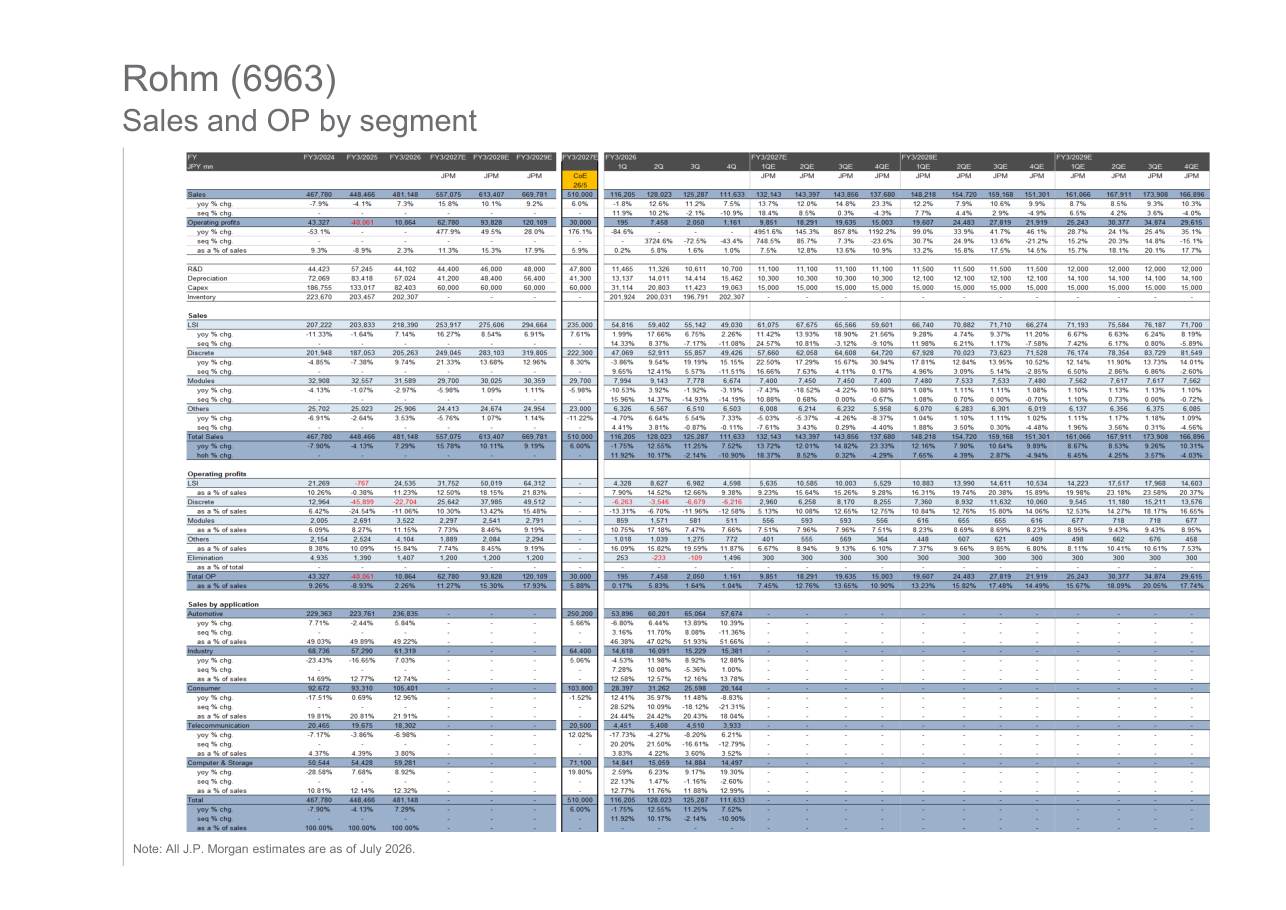
Page 45 · Rohm(6963):分部销售额与营业利润
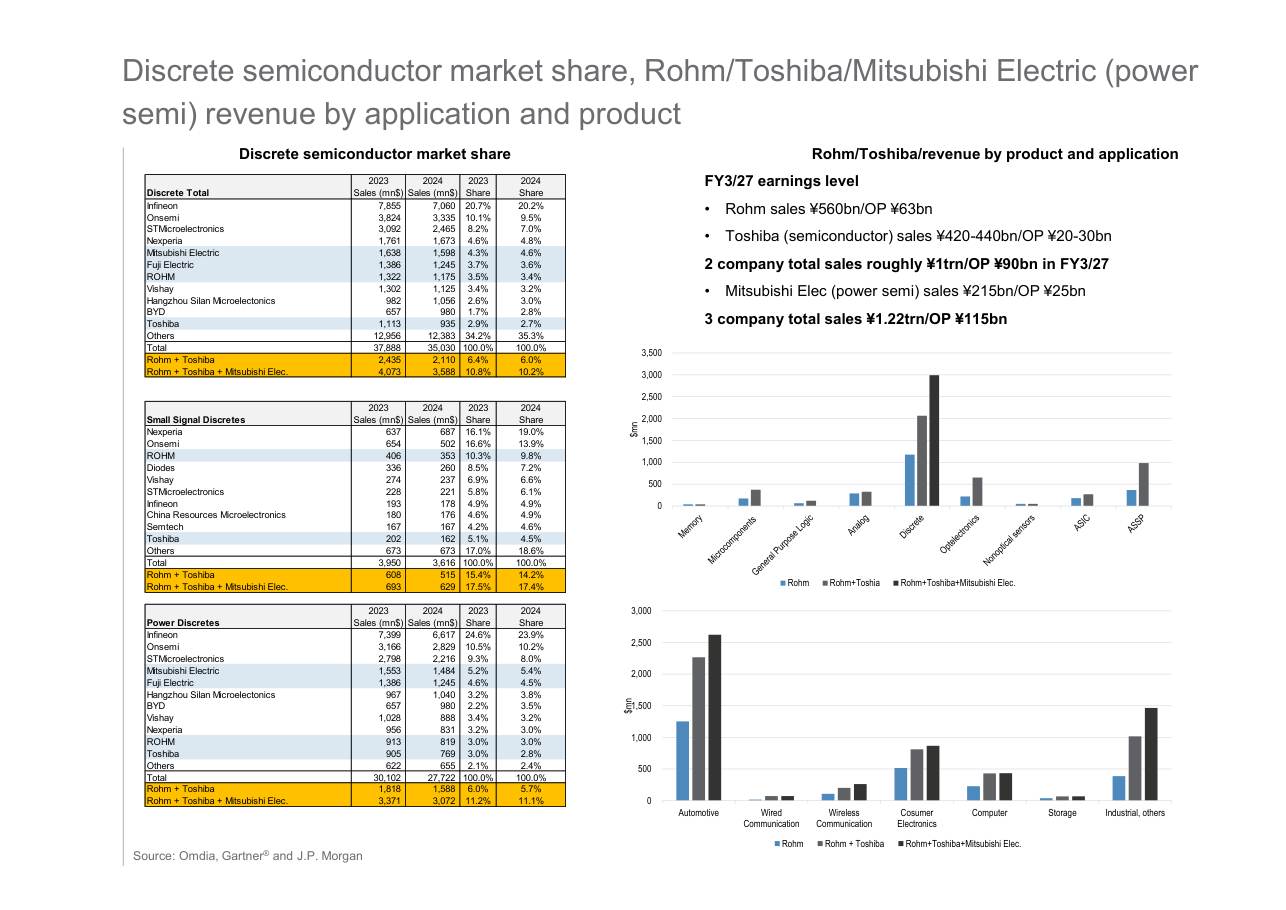
Page 46 · 分立器件市场规模与份额(2023 vs 2024)
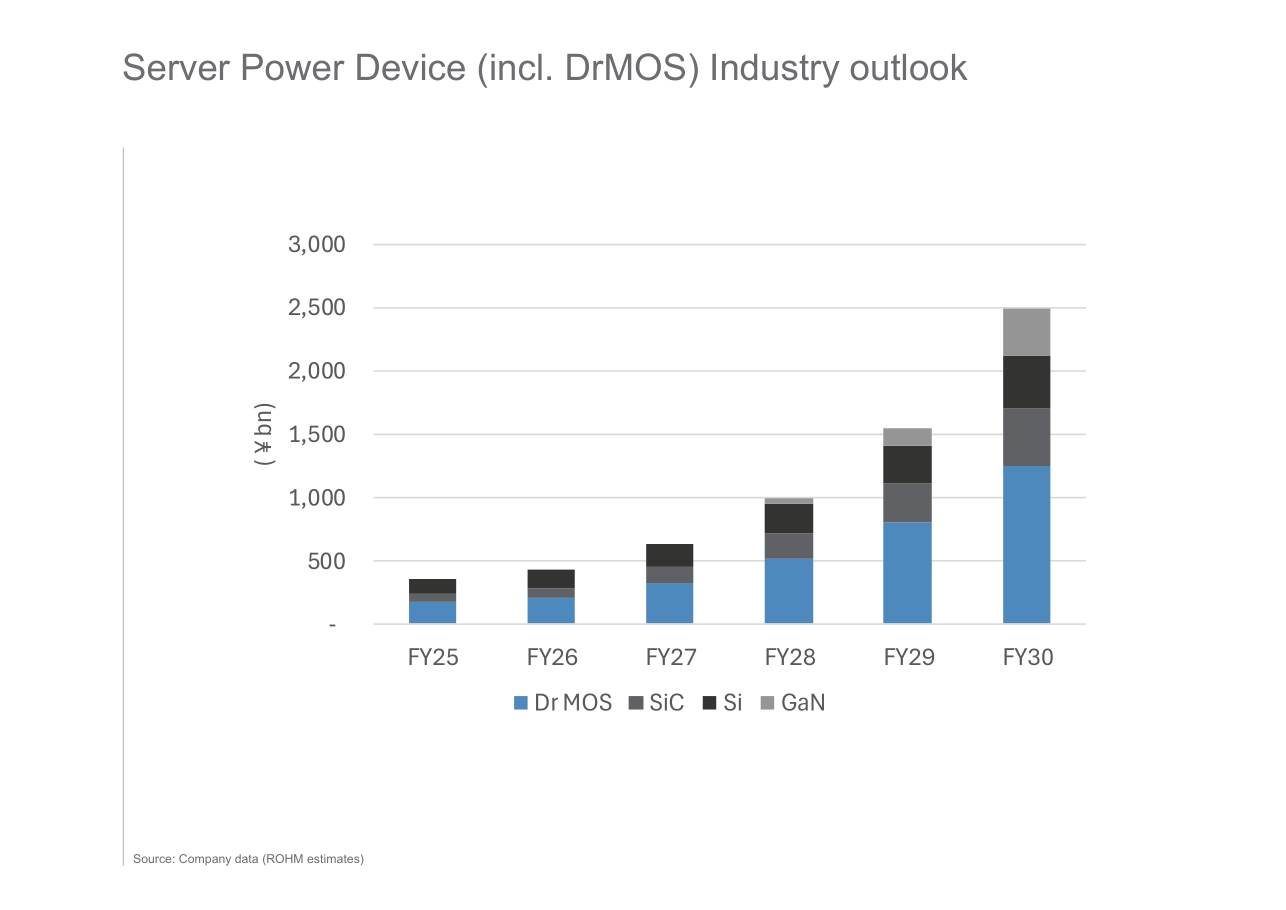
Page 47 · 服务器电源器件(含 DrMOS)行业展望(ROHM 口径)
Kyocera(6971)
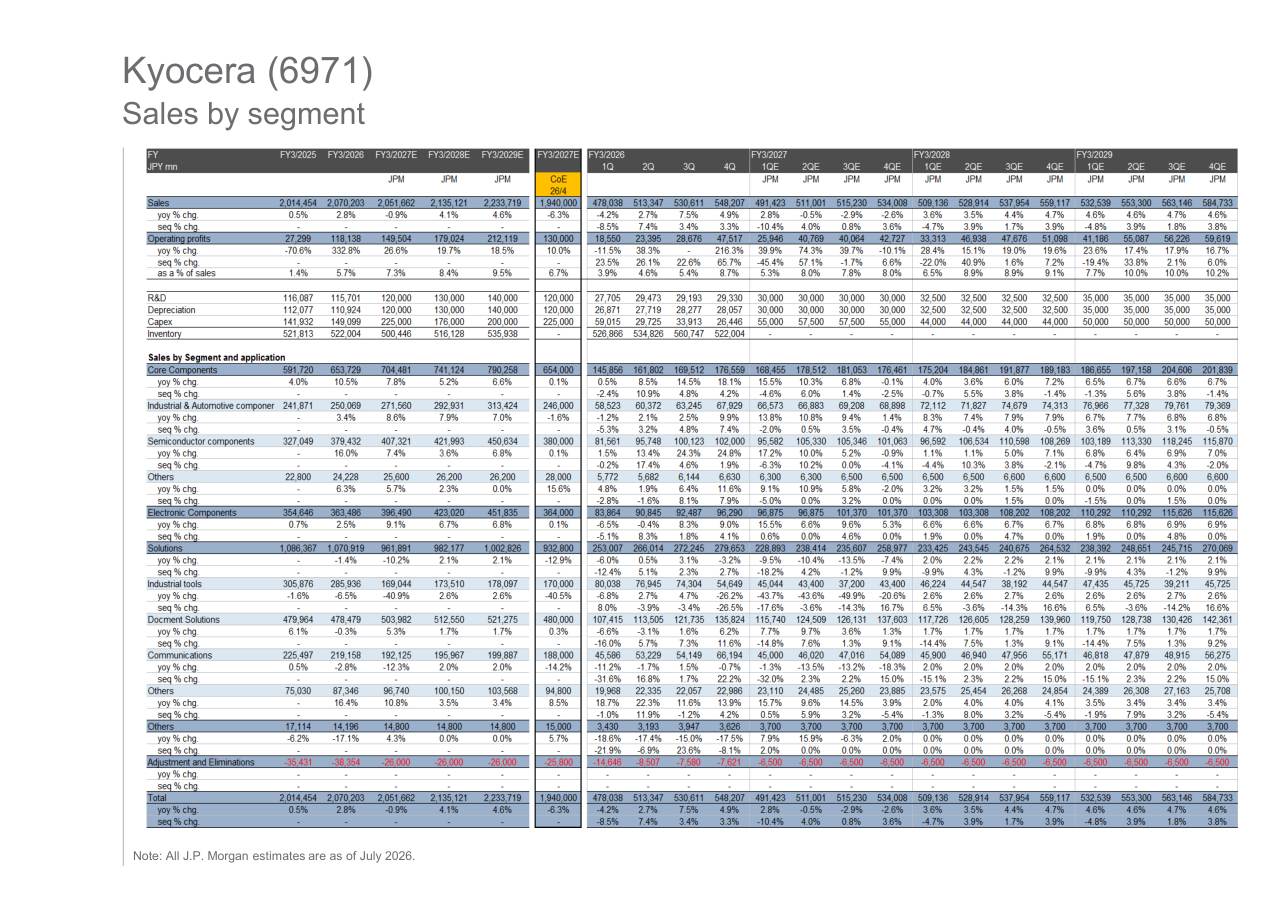
Page 48 · Kyocera(6971):分部销售额
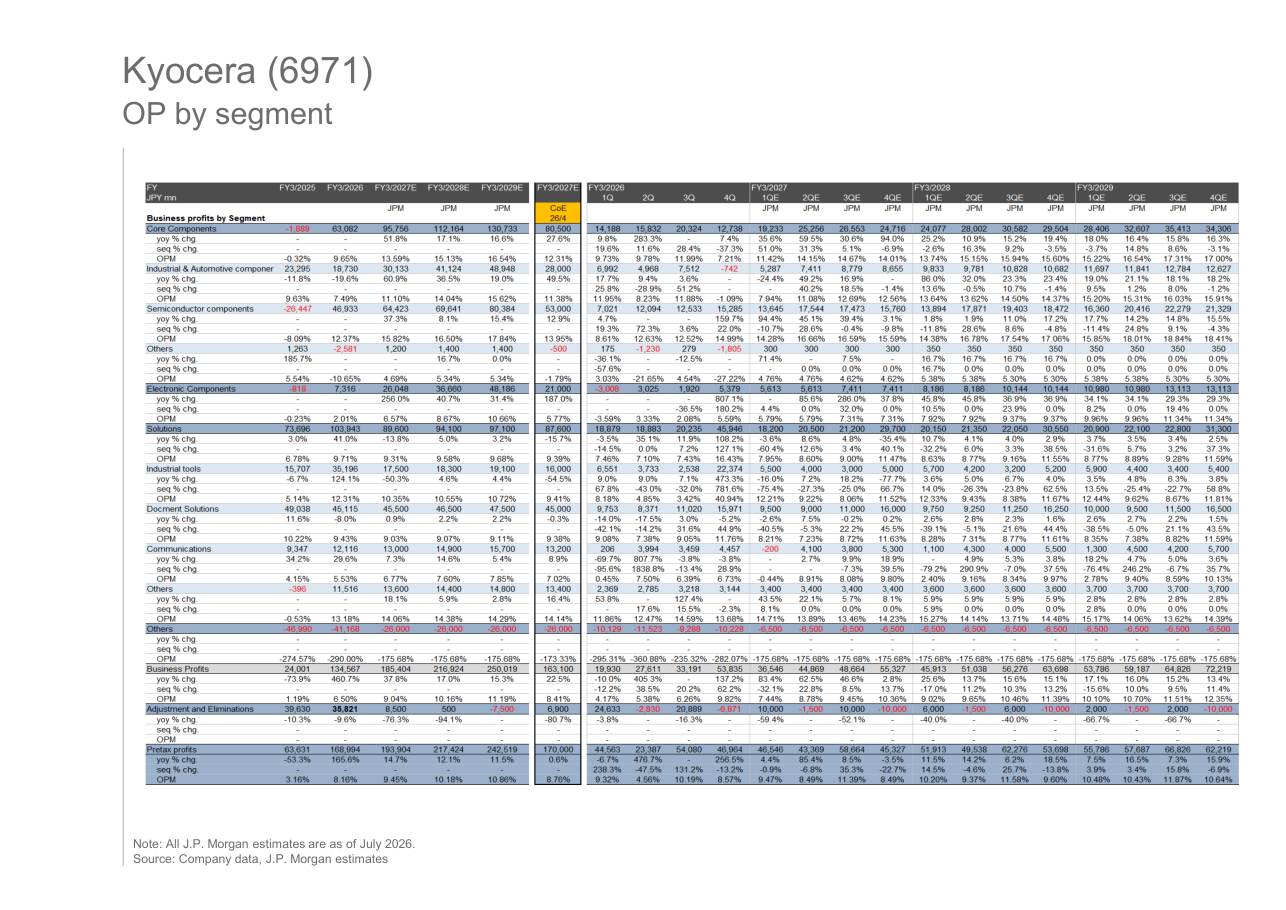
Page 49 · Kyocera(6971):分部营业利润
Taiyo Yuden(6976)
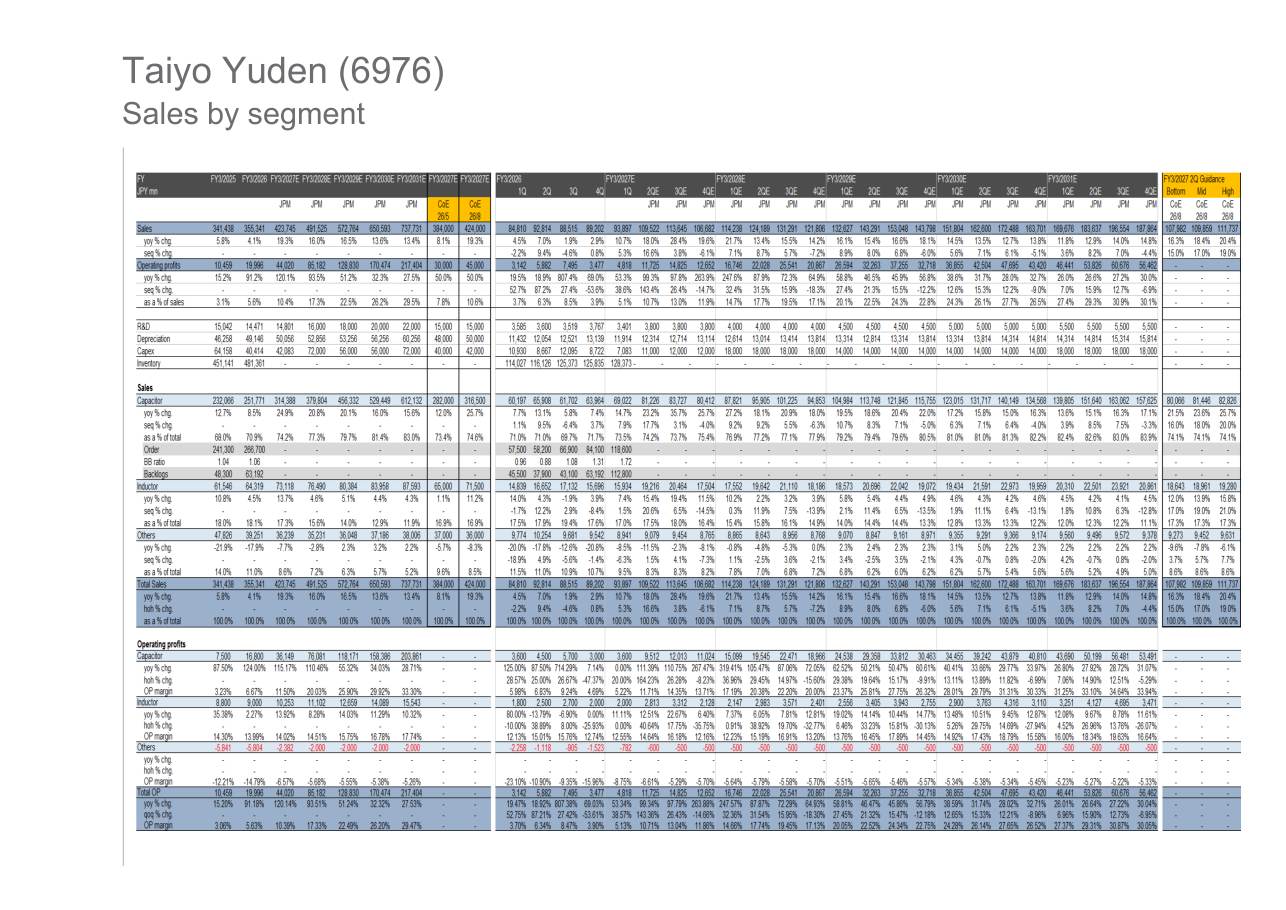
Page 50 · Taiyo Yuden(6976):分部销售额
Murata Mfg.(6981)
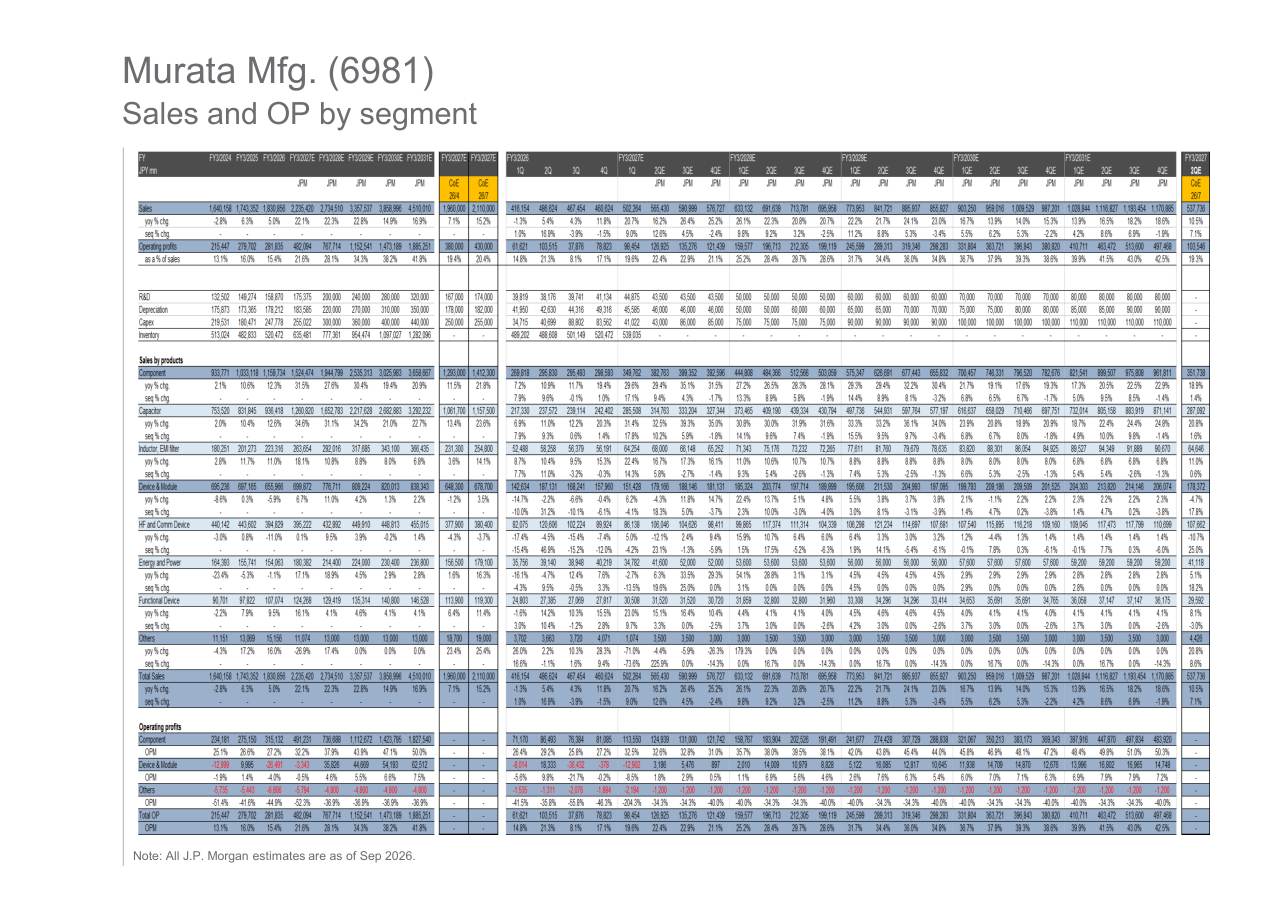
Page 51 · Murata Mfg.(6981):分部销售额与营业利润
Nichicon(6996)
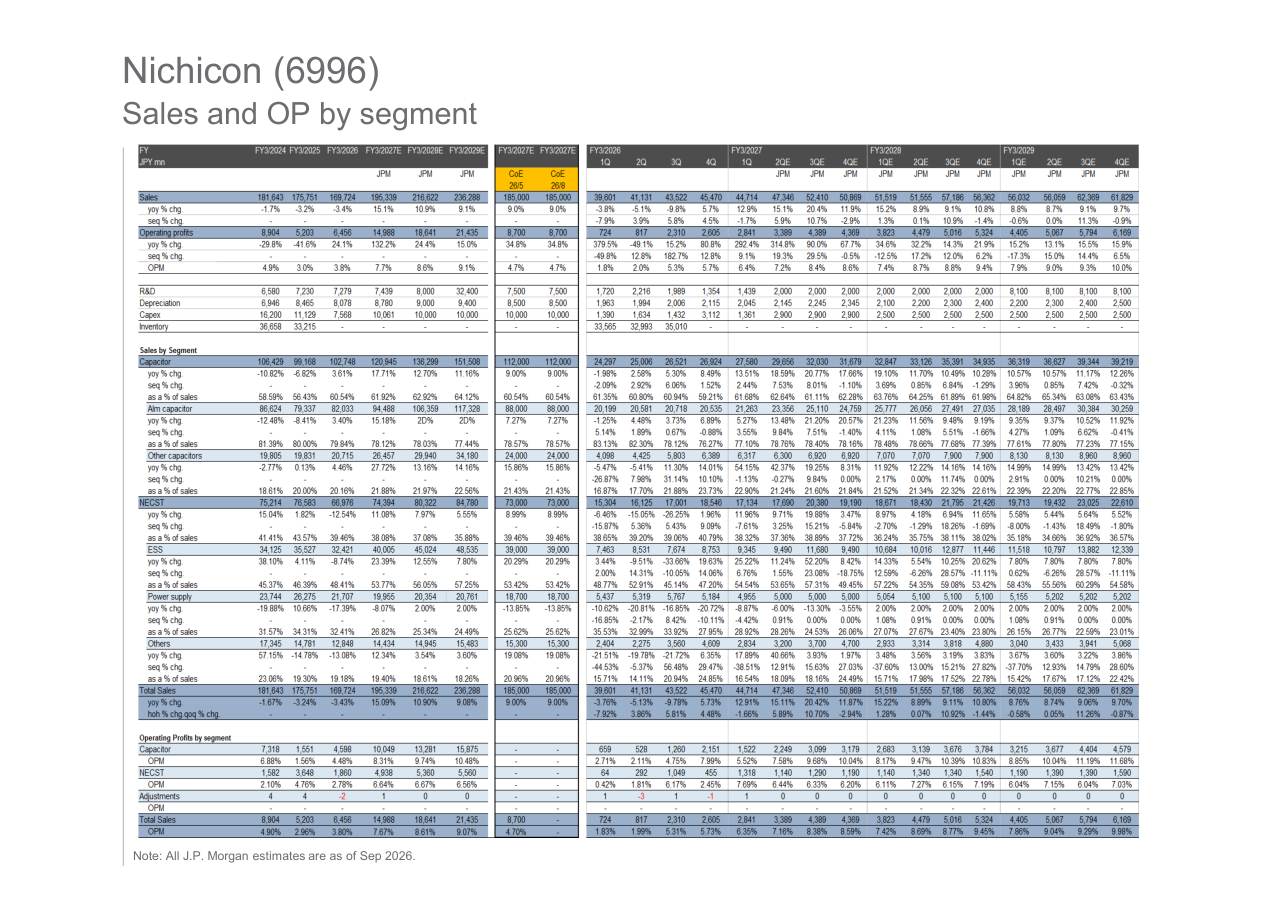
Page 52 · Nichicon(6996):分部销售额与营业利润
Nippon Chemi-con(6997)
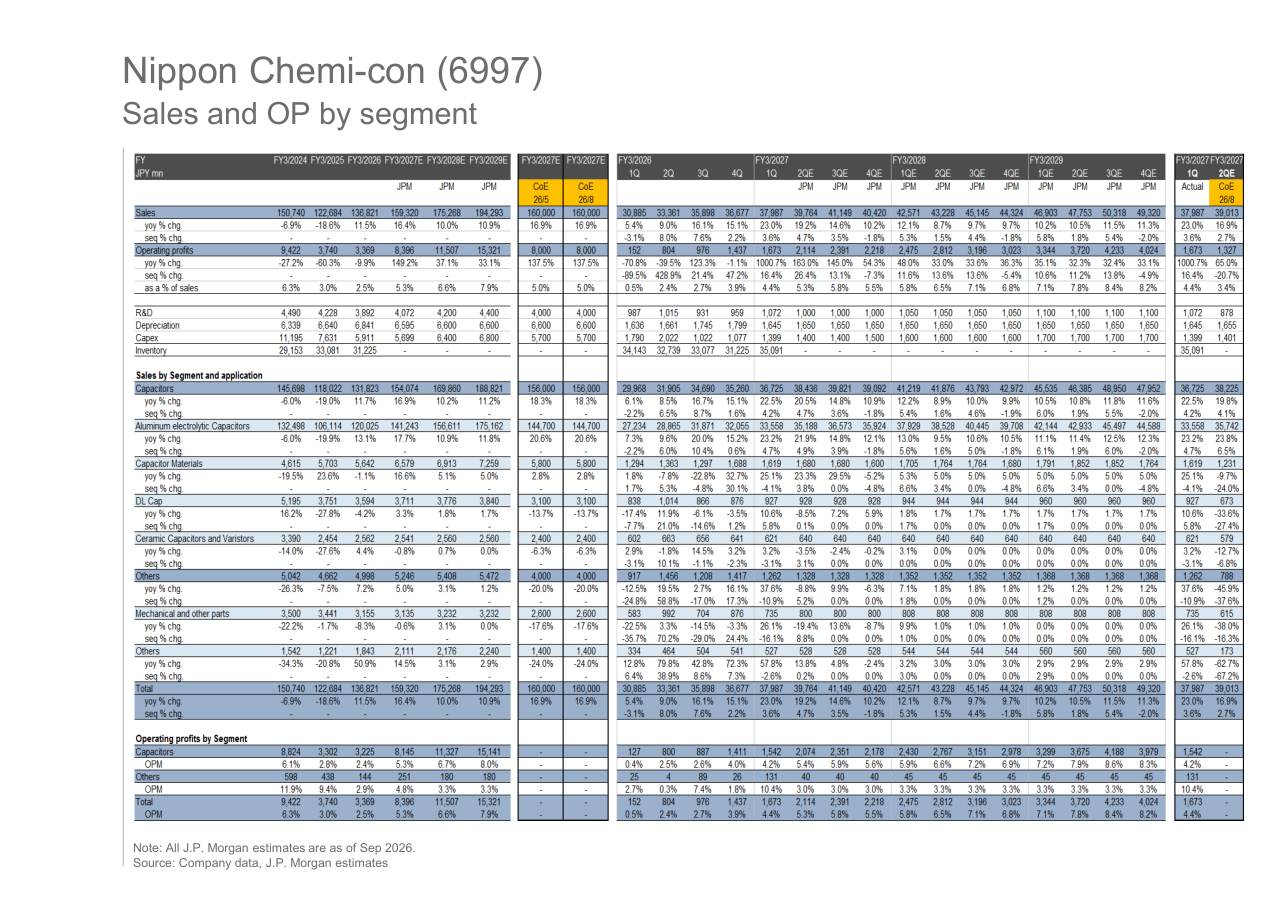
Page 53 · Nippon Chemi-con(6997):分部销售额与营业利润
NISSHA(7915)
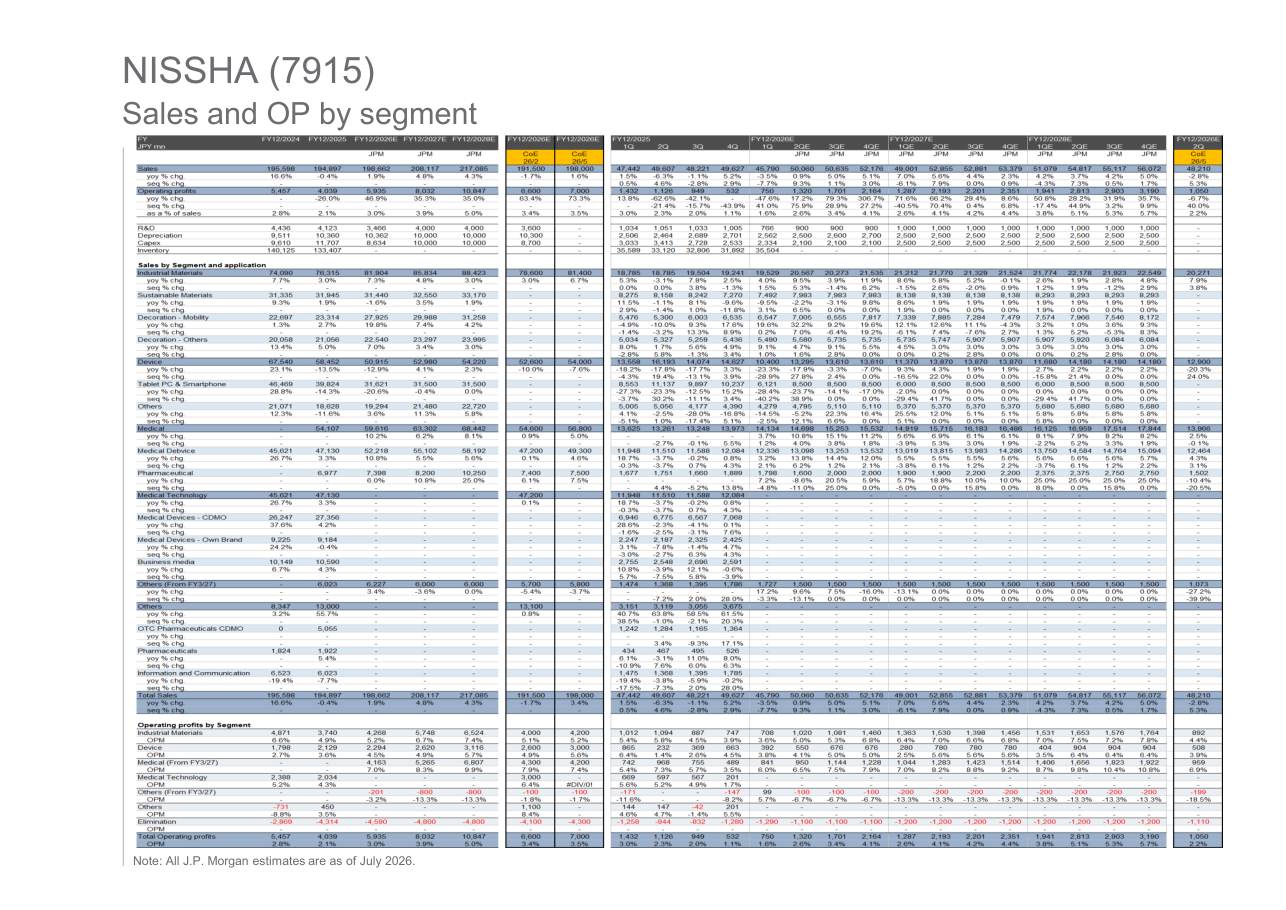
Page 54 · NISSHA(7915):分部销售额与营业利润
第二部分:结构化解读
以下解读由本站基于上述报告数据独立撰写,观点归属本站,不代表 J.P. Morgan。所有数字均取自原报告图表,CY26E–CY30E 为 J.P. Morgan 预测值,非事实陈述。报告不含个股评级与目标价(该部分未收录,见文首说明)。
一、这份报告是什么:一张被动元件行业的「体检表」
这不是一篇观点文,而是一份图表数据手册(chart pack):62 页里几乎没有段落式论述,全部是带数据标签的图表与表格。它的价值不在「说了什么」,而在把整条日本电子元件产业链的量化事实摊在一张桌子上——需求按应用拆到 2030 年、供给拆到稼动率和月产能、单机价值量拆到「一个机架用多少颗电容、总共多少微法、值多少钱」。
覆盖链条可以概括为四层:
| 层 | 内容 | 代表页 |
|---|---|---|
| 需求侧 | AI 加速器 TDP 路线图、AI 服务器出货与总算力(GW) | P21–22 |
| 元件侧 | MLCC 用量 / 容量 / ASP、成本与利润率代际模型 | P23–28 |
| 供给侧 | 四大厂稼动率、月产能、工厂建设、供需平衡 | P16–20 |
| 封装侧 | AI 基板尺寸与层数、Ibiden 产能再分配 | P29–32 |
二、核心结论一:MLCC 的需求结构正在被 AI 服务器重写
报告最关键的一张表是 MLCC 销售预测(P15)。把数字抽出来:
| 应用 | CY25($mn) | CY30E($mn) | CAGR | 占比 CY25 → CY30E |
|---|---|---|---|---|
| 服务器(含 AI) | 1,200 | 19,681 | 75% | 9% → 56% |
| 汽车 | 4,926 | 7,435 | 8.6% | 39% → 21% |
| 电信 | 3,534 | 4,357 | 4.3% | 28% → 12% |
| PC / 平板 | 1,414 | 1,821 | 5.2% | 11% → 5% |
| 消费 | 978 | 1,059 | 1.6% | 8% → 3% |
| 合计 | 12,752 | 35,147 | 22.5% | — |
三个读法:
- 总量:五年 2.8 倍($12.8bn → $35.1bn,CAGR 22.5%)。对一个人均资本开支以「亿日元」计、历史上长期个位数增长的被动元件行业,这个斜率本身就是事件。
- 结构:到 2030 年,服务器一项将占 MLCC 需求的 56%——它一个人的体量($19.7bn)比 2025 年整个市场($12.8bn)还大。汽车仍是稳健的第二大项(CAGR 8.6%),但从主角退居配角。
- 权重转移的含义:手机 / 消费 / 电信这类传统周期驱动合计占比从 47% 降到 20%。这意味着行业未来的估值锚将从「消费电子库存周期」切向「AI 算力资本开支周期」——两者的波动来源、领先指标和估值框架完全不同。
三、核心结论二:单机架价值量的跃升(GB300 → VR200,3.6 倍)
P26 给出了最硬的量化证据——每机架的 MLCC 用量与价值:
| 口径 | 用量(颗) | 总容量(µF) | 平均容量(µF) | 单机架价值(US$) | 单颗 ASP |
|---|---|---|---|---|---|
| 高端智能手机 | 1,200 | 4,100 | 3.42 | — | — |
| 通用服务器 | 3,000 | 22,000 | 7.33 | — | — |
| GB200 机架 | 355,000 | 4,000,000 | 11.27 | — | — |
| GB300 机架 | 355,000 | 5,000,000 | 14.08 | 2,840 | 0.8¢ |
| VR200 机架 | 564,000 | 12,000,000 | 21.28 | 10,155 | 1.8¢ |
| GB300 → VR200 增量 | +209,000 | +7,000,000 | 33.49 | +7,315 | 3.5¢ |
解读链条:
- 量:GB300 → VR200(NVIDIA Rubin 代机架),单机架用量 +59%,但总容量 +140%——平均单颗容量从 14µF 跳到 21µF,增量部分的平均容量高达 33µF。不是「用更多颗」,是「用更高级的颗」。
- 价:增量单颗 ASP 约 3.5¢,是 FY25 AI 服务器 MLCC 平均 ASP(约 $0.01)的 3 倍以上;单机架 MLCC 价值量从 $2,840 提到 $10,155,3.6 倍。
- 为什么是大容量小尺寸:P22 的 TDP 表是需求侧的总开关。NVIDIA 单 GPU 功耗从 A100 的 400W 一路走到 Rubin Ultra 3600W、Feynman Ultra 6000W;AMD MI450X/455X 到 1400–2000W,Meta 自研 MTIA 也到 1700W。功耗越高 → 电流瞬变越剧烈 → 电源完整性越难做 → 越需要在 ASIC 旁边放低等效串联电感(低 ESL)、大容量、小封装的去耦电容。侧面成型(Side Forming,P27)正是为「贴得更近、电感更低」服务的封装工艺。
四、核心结论三:代际跃迁是利润率跃迁,不只是收入跃迁
P25 用 Murata 做模型案例,把「同一颗电容」在不同技术代上的经济性拆开了:
| Gen5(2014–15) | Gen6(2018–20) | Gen7(2023–25) | |
|---|---|---|---|
| 规格 | 1005 / 10µF | 1005 / 22µF | 1005 / 47µF |
| ASP(美分) | 0.8 | 2.3 | 10.0 |
| 每 µF 价格(美分) | 0.080 | 0.102 | 0.213 |
| 介质层粒径(nm) | 150 | 100 | 80 |
| 生瓷片厚度(µm) | 1.2 | 0.8 | 0.5 |
| 叠层数 | 400 | 750 | 1,000 |
| 营业利润率 | 20.0% | 47.4% | 69.2% |
| 增量利润率 | 50% | 67.1% | 80.8% |
这是整份手册里最能解释「为什么被动元件能讲 AI 故事」的一页:
- ASP 十二年 12.5 倍,靠的不是涨价,而是在同样的 1005 封装尺寸里塞进 4.7 倍的容量——介质层从 150nm 磨到 80nm、生瓷片薄到 0.5µm、叠到 1,000 层共烧。这是材料与工艺的护城河,不是资本开支能直接买来的。
- 报告判断(P26):增量主力规格 1005/47µF 的单颗价格约 10¢(普通版同容量的 12 倍),其增量利润率可能高于 70% 的行业平均,营业利润率可能超过 60%。换言之,AI 服务器带来的增量收入,落在利润表上的杠杆远大于收入表。
- 与 P11 的份额表对照:Murata 长期稳定在 41–45%,且报告明确认为其在侧面成型工艺上「显著领先同业」。份额稳定 + 结构上移,是典型的「量稳价升」利润结构。
五、核心结论四:供给是瓶颈,而瓶颈有结构性偏向
需求侧讲得再好,也必须回答「产能跟不跟得上」。报告给出的供给侧证据:
- 稼动率(P16):四大厂(Murata、太阳诱电、SEMCO、TDK)历史稼动率区间大致在 60–100% 波动,报告给出 CY26 二季度时点(CoE)的当前读数。
- 产能(P17):行业月产能以「十亿颗 / 月」计,Murata 单家占据大头。
- 扩产节奏(P18):以 Murata 为样本的工厂建设明细——新建厂房的楼层数、钢构规格与建筑资本开支逐项列出。这类微观数据是验证「扩产是真是假」最硬的证据。
- 供需平衡(P19):2017–2030E 的行业供需模型(十亿颗 + 供需差百分比)。
- 降价的利润冲击(P20):量化了稼动率下行叠加降价对 Murata / 太阳诱电营业利润的季度冲击幅度。
值得注意的结构性矛盾:AI 服务器要的是高端小尺寸高容(1005/47µF 这类 Gen7 产品),与消费类产线并不完全通用。所以即使总量产能富余,高端产能仍可能紧张——这就是 P19 供需模型里「总量」与「高端」可能给出不同结论的原因,也是读这类数据手册时最容易被「合计数」掩盖的地方。
六、核心结论五:基板是同一个故事的封装端镜像
P30 的基板结构表,把 AI 算力对封装的挤压量化到了平方毫米:
| 产品 | 叠层结构 | 基板尺寸(mm) | 面积(mm²) | Build-up 层数 | Build-up 需求(mm²) |
|---|---|---|---|---|---|
| Intel Xeon(基准=100) | 5-2-5 | 77.5 × 56.5 | 4,379 | 10 | 43,788 |
| NVIDIA H100 | 5-2-5 | 58 × 55 | 3,190 | 10 | 31,900 |
| NVIDIA B100/B200 | 8-2-8 | 73 × 81 | 5,913 | 14 | 82,782 |
| NVIDIA Rubin | 10-2-10 | 100 × 100 | 10,000 | 20 | 200,000 |
| AMD MI350 | 8-2-8 | 75.4 × 72 | 5,429 | 16 | 86,861 |
| AWS Trainium3 | 9-2-9 | 73 × 88 | 6,424 | 18 | 115,632 |
| AWS Trainium4 | 11-2-11 | 115 × 120 | 13,800 | 22 | 303,600 |
| Microsoft Maia100 | 8-2-8 | 70 × 70 | 4,900 | 16 | 78,400 |
- Rubin vs Xeon:基板面积 2.3 倍,但 build-up 需求 4.6 倍——因为层数同时从 10 加到 20。基板的增长是「面积 × 层数」的乘积效应。
- Trainium4 vs H100:面积 4.3 倍、build-up 需求 9.5 倍。自研 ASIC 为降本走极端大封装路线,对载板厂商反而是更陡的价值量曲线。
- P31–32 落到 Ibiden:SAP 需求指数、非 Intel 产能如何从 Intel(Cell 5 / Gama)逐步转向 NVIDIA(Cell 2,3,4 → Ono+Cell4)与 AMD(Cell 2,3,4,5),以及 FC-BGA 之外新 2.5D 基板的收入线。
MLCC 与基板在这里是同一个逻辑的两次出现:AI 芯片把功耗和引脚密度同时推高,前者把去耦电容推向高容低感,后者把载板推向大尺寸多层——两者的共性是「单机价值量随代际非线性上升,且供给受工艺与良率约束」。
七、其他值得记录的量化事实
- 市占率稳定性(P11):Murata 约 41–45%、SEMCO 约 24%、太阳诱电约 11–12%、TDK 在 10–15% 间波动。格局高度集中且多年未变——这是一个「份额换不动、只能换结构」的行业。
- 车用 MLCC(P13–14):单车 MLCC 价值量持续上行,四大厂(Murata / TDK / 太阳诱电 / SEMCO)合计占据车用市场主导份额;汽车是需求结构中确定性最高、增速中等的一环。
- 离散器件(P46):2024 年全球分立器件市场约 $35.0bn(同比 -7.6%),Infineon 20.2%、onsemi 9.5%、ST 7.0%、ROHM 3.4%;值得留意的是杭州士兰微(2.6%→3.0%)与 BYD 半导体(1.7%→2.8%)份额在上行——中国厂商在分立器件端的价格压力是结构性的。
- 服务器电源器件(P47):含 DrMOS 的服务器功率器件行业展望(ROHM 口径),与 MLCC 共享同一个「AI 服务器电源完整性」需求源。
- 汇率敏感性(P8):日本元件企业收入以美元计价、成本以日元计价,日元汇率对利润的敏感度是这类公司盈利预测的常量变量。
八、怎么用这份手册:三个可跟踪的先行指标
如果要把它变成一个可持续跟踪的框架,报告里最有信号价值的是三组数:
- NVIDIA Rubin / Feynman 的 TDP 与机架渗透节奏(P22)——MLCC 单机架价值量的直接乘数。
- 高端产能(而非总产能):稼动率 + Murata 工厂建设进度(P16–18)——决定 2027–2028 年高端供需是否再度错配。
- 1005/47µF(侧面成型)的 ASP 与增量利润率(P25–26)——决定这轮需求红利有多少留在利润表。
九、阅读边界与风险提示
- 预测非事实:CY26E–CY30E 全部为 J.P. Morgan 估计,其中部分依赖其台湾科技团队 2026 年 4 月的 AI 服务器出货预测(P21)。AI 资本开支的任何下修都会等比例传导到这里的 2030 年数字。
- 口径注意:MLCC 市场数据为四大厂(Murata、太阳诱电、TDK、SEMCO)口径,非全球全行业;基板数据来自 JPM 对市售产品的实测与调查(P30 注释)。
- 未收录部分:第 2–3 页的评级 / 目标价 / 估值表、第 55–62 页的标准法务披露页未在本页复现;本站亦不提供任何投资建议。
- 来源说明:本 PDF 为第三方整理流传版本(带第三方水印),非 J.P. Morgan 官方分发渠道;数据以原报告为准,本站仅作研究性解读。
展开:原报告文字层(图表数据标签,共 52 页,供检索与核对数字)
Page 1 · 封面
Technology – Electronic Components
Technology – Electronic Components
Akinori Kanemoto AC
+813-6736-8628
akinori.kanemoto@jpmorgan.com
JPMorgan Securities Japan Co., Ltd.
Technology – Consumer/Industrial/Precision
Junya Ayada
+813-6736-8631
junya.ayada@jpmorgan.com
JPMorgan Securities Japan Co., Ltd.
Asia Pacific Equity Research
11 September 2026
See the end pages of this presentation for analyst certification and important disclosures, including non-US analyst disclosures.
Page 4 · 股价表现
Electronic components
Share price performance
Note: Share price as of 9/9/2026
Source: Bloomberg Finance L.P., J.P. Morgan
Page 5 · 盈利预测摘要 I
Earnings forecast summary
Note: BBG consensus as of 9/9/2026.
Source: Company data, Bloomberg Finance L.P. consensus, J.P. Morgan estimates
Page 6 · 盈利预测摘要 II
Earnings forecast summary
Note: BBG consensus as of 9/9/2026.
Source: Company data, Bloomberg Finance L.P. consensus, J.P. Morgan estimates
Page 7 · FCF/ROIC/ROE
Electronic components
FCF/ROIC/ROE estimates
Note: J.P. Morgan estimates are all as of July-Sep 2026 (Nidec is as of Dec 2025).
Source: Company data, J.P. Morgan estimates
Page 8 · 汇率敏感性
F/X sensitivity
Source: Company data
Page 9 · 板块历史估值
Electronic components sector
Historical valuations and relative valuation to TOPIX (Bloomberg consensus basis)
12-month forward P/E and relative P/E to TOPIX
12-month forward P/B and relative P/B to TOPIX
24-month forward P/E and relative P/E to TOPIX
24-month forward P/B and relative P/B to TOPIX
Note: BBG consensus and share price as of 9/9/2026
Source: Bloomberg Finance L.P. consensus, J.P. Morgan estimates
Page 10 · MLCC 收入按应用
MLCC revenue by application $mn (yearly, quarterly)
Note: Company data includes Murata, Taiyo Yuden, TDK, and SEMCO.
0
500
1,000
1,500
2,000
2,500
3,000
3,500
4,000
4,500
1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q
CY10 CY11 CY12 CY13 CY14 CY15 CY16 CY17 CY18 CY19 CY20 CY21 CY22 CY23 CY24 CY25CY26
$mn
Automotive
Computer
Telecom
Customer
Industrial & Others
0%
10%
20%
30%
40%
50%
60%
70%
80%
90%
100%
1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q
CY10 CY11 CY12 CY13 CY14 CY15 CY16 CY17 CY18 CY19 CY20 CY21 CY22 CY23 CY24 CY25CY26
Automotive
Computer
Telecom
Customer
Industrial & Others
Page 11 · MLCC 市占率
MLCC revenue market share (yearly, quarterly)
0%
10%
20%
30%
40%
50%
60%
70%
80%
90%
100%
Murata
Taiyo Yuden
TDK
Kyocera
SEMCO
Yageo
0
2,000
4,000
6,000
8,000
10,000
12,000
14,000
16,000
18,000
$mn
Murata
Taiyo Yuden
TDK
Kyocera
SEMCO
Yageo
0
500
1,000
1,500
2,000
2,500
3,000
3,500
4,000
4,500
5,000
1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q
CY14
CY15
CY16
CY17
CY18
CY19
CY20
CY21
CY22
CY23
CY24
CY25 CY26
$mn
Murata
Taiyo Yuden
TDK
kyocera
SEMCO
Yageo
0%
10%
20%
30%
40%
50%
60%
70%
80%
90%
100%
1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q 3Q 1Q
CY14
CY15
CY16
CY17
CY18
CY19
CY20
CY21
CY22
CY23
CY24
CY25 CY26
Murata
Taiyo Yuden
TDK
Kyocera
SEMCO
Yageo
M/S
CY20
CY21
CY22
CY23
CY24
CY25
CY26
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
Murata
41.2%
40.8%
39.7%
41.8%
40.5%
41.5%
40.4%
41.9%
40.8%
42.8%
42.8%
44.3%
41.7%
40.9%
43.4%
44.9%
43.6%
43.8%
42.5%
44.1%
41.7%
45.2%
45.1%
45.8%
44.6%
45.0%
Taiyo Yuden
13.0%
12.1%
13.3%
12.9%
12.1%
11.6%
11.7%
12.4%
12.3%
11.6%
12.4%
12.1%
12.4%
11.4%
11.4%
12.3%
12.1%
12.0%
11.6%
12.1%
12.3%
12.5%
12.5%
11.8%
11.8%
10.9%
TDK
11.2%
10.1%
9.8%
10.4%
10.6%
10.3%
9.9%
10.6%
10.6%
12.2%
13.8%
14.9%
15.1%
15.1%
13.8%
13.5%
14.0%
13.2%
11.5%
11.9%
11.8%
12.4%
11.8%
12.7%
12.8%
12.7%
SEMCO
24.8%
26.6%
25.4%
23.6%
25.5%
24.6%
25.7%
23.2%
24.7%
21.3%
18.0%
17.5%
18.3%
20.2%
19.4%
17.4%
18.3%
19.4%
23.5%
21.4%
22.8%
23.8%
24.9%
23.6%
24.2%
24.6%
Others
9.8%
10.4%
11.8%
11.2%
11.3%
11.9%
12.3%
11.9%
11.6%
12.2%
13.0%
11.2%
12.5%
12.4%
12.0%
12.0%
12.0%
11.5%
10.9%
10.6%
11.3%
6.1%
5.8%
6.1%
6.6%
6.7%
Page 12 · MLCC 按应用销售额
MLCC
Sales by application
Note: Company data includes Murata, Taiyo Yuden, TDK, and SEMCO.
For Smartphone
For Automotive
For PC/Servers
For Consumer and Others
0
200
400
600
800
1,000
1,200
1,400
1,600
1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q
CY10CY11CY12CY13CY14CY15CY16CY17CY18CY19CY20CY21CY22CY23CY24CY25CY26
$mn
0
200
400
600
800
1,000
1,200
1,400
1,600
1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q3Q1Q
CY10CY11CY12CY13CY14CY15CY16CY17CY18CY19CY20CY21CY22CY23CY24CY25CY26
$mn
0
200
400
600
800
1,000
1,200
1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q
CY10CY11CY12CY13CY14CY15CY16CY17CY18CY19CY20CY21CY22CY23CY24CY25CY26
$mn
0
100
200
300
400
500
600
1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q
CY10CY11CY12CY13CY14CY15CY16CY17CY18CY19CY20CY21CY22CY23CY24CY25CY26
$mn
Page 13 · MLCC 单机价值量
MLCC $ contents for smartphones, computers, autos
Note: Company data includes Murata, Taiyo Yuden, TDK, and SEMCO.
Source: Company data, J.P. Morgan
MLCC $ contents per handset
MLCC $ contents per computer
MLCC $ contents per car
-40%
-30%
-20%
-10%
0%
10%
20%
30%
40%
50%
60%
0.00
0.50
1.00
1.50
2.00
2.50
3.00
3.50
4.00
1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q
CY11CY12CY13CY14CY15CY16CY17CY18CY19CY20CY21CY22CY23CY24CY25CY26
MLCC contents per handset (lhs,$)
yoy % chg. (rhs)
-40%
-20%
0%
20%
40%
60%
80%
0.00
10.00
20.00
30.00
40.00
50.00
60.00
70.00
1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q
CY11CY12CY13CY14CY15CY16CY17CY18CY19CY20CY21CY22CY23CY24CY25CY26
MLCC contents per car (lhs,$)
yoy % chg. (rhs)
-100%
-50%
0%
50%
100%
150%
200%
250%
300%
0.00
1.00
2.00
3.00
4.00
5.00
6.00
7.00
8.00
9.00
10.00
2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q 3Q 2Q 1Q 4Q
CY16 CY17 CY18 CY19 CY20 CY21 CY22 CY23 CY24 CY25CY26
MLCC $ contents per box (LHS, $)
yoy % chg.(RHS)
Page 14 · 车用 MLCC
Automotive MLCC: $ contents per car, market share, market size
Note: Combined Total for Murata Mfg., TDK, Taiyo Yuden, and SEMCO.
Source: J.P. Morgan, Company data.
Automotive MLCC revenues for major four suppliers
$ contents per car of MLCC for major four suppliers
Automotive MLCC market share for four major makers
Page 15 · MLCC 销售预测至 CY30E
MLCC sales forecast by application
Source: Company data, J.P. Morgan estimates
0
5,000
10,000
15,000
20,000
25,000
30,000
35,000
40,000
CY20
CY21
CY22
CY23
CY24
CY25
CY26E
CY27E
CY28E
CY29E
CY30E
$ mn
Consumer
PC/Tablet PCs
Telecom
Automotive
Others
Servers
0%
10%
20%
30%
40%
50%
60%
70%
80%
90%
100%
Consumer
PC/Tablet
Telecom
Automotive
Others
Server
AI Server
$ mn
CY10
CY11
CY12
CY13
CY14
CY15
CY16
CY17
CY18
CY19
CY20
CY21
CY22
CY23
CY24
CY25
CY26E
CY27E
CY28E
CY29E
CY30E
Consumer
1,811
1,577
1,221
909
823
756
872
921
1,184
1,013
1,112
1,317
1,002
783
764
959
978
998
1,018
1,038
1,059
YoY % chg.
-12.9%
-22.6%
-25.6%
-9.4%
-8.2%
15.3%
5.6%
28.5%
-14.4%
9.8%
18.4%
-23.9%
-21.9%
-2.3%
25.4%
2.0%
2.0%
2.0%
2.0%
2.0%
PC/Tablet
1,577
1,467
1,450
985
803
679
848
949
1,379
1,443
1,629
1,898
1,617
1,017
1,147
1,414
1,424
1,515
1,619
1,717
1,821
YoY % chg.
-6.9%
-1.2%
-32.1%
-18.5%
-15.5%
24.9%
11.9%
45.3%
4.6%
12.9%
16.5%
-14.8%
-37.1%
12.8%
23.2%
0.7%
6.4%
6.9%
6.1%
6.1%
Server
390
421
430
438
451
465
511
614
859
902
1,082
1,515
837
598
816
1,200
2,694
5,641
10,122
14,839
19,681
YoY % chg.
8.0%
2.0%
2.0%
3.0%
3.0%
10.0%
20.0%
40.0%
5.0%
20.0%
40.0%
-44.7%
-28.6%
36.4%
47.1%
124.5%
109.4%
79.4%
46.6%
32.6%
Telecom
1,790
2,510
2,994
2,820
2,737
3,013
3,098
3,238
4,114
4,036
4,552
4,997
3,761
3,088
3,131
3,534
3,577
3,758
3,948
4,148
4,357
YoY % chg.
40.2%
19.3%
-5.8%
-2.9%
10.1%
2.8%
4.5%
27.1%
-1.9%
12.8%
9.8%
-24.7%
-17.9%
1.4%
12.9%
1.2%
5.1%
5.1%
5.1%
5.1%
Automotive
740
864
1,013
1,080
1,175
1,332
1,684
1,957
2,559
3,036
3,046
4,119
4,252
4,409
4,516
4,926
5,317
5,812
6,288
6,840
7,435
YoY % chg.
16.8%
17.2%
6.6%
8.8%
13.4%
26.4%
16.2%
30.7%
18.7%
0.3%
35.2%
3.2%
3.7%
2.4%
9.1%
7.9%
9.3%
8.2%
8.8%
8.7%
Others
627
545
391
302
365
411
431
745
1,065
888
964
1,229
926
784
797
719
733
748
763
778
794
YoY % chg.
-13.0%
-28.4%
-22.7%
21.0%
12.5%
4.9%
73.0%
42.9%
-16.7%
8.6%
27.6%
-24.7%
-15.4%
1.6%
-9.7%
10.0%
2.0%
2.0%
2.0%
2.0%
Total
6,934
7,384
7,498
6,534
6,354
6,656
7,444
8,424
11,160
11,318
12,385
15,076
12,395
10,678
11,171
12,752
14,722
18,471
23,757
29,360
35,147
yoy % chg.
6.5%
1.5%
-12.9%
-2.7%
4.8%
11.8%
13.2%
32.5%
1.4%
9.4%
21.7%
-17.8%
-13.9%
4.6%
14.2%
15.5%
25.5%
28.6%
23.6%
19.7%
Consumer
26%
21%
16%
14%
13%
11%
12%
11%
11%
9%
9%
9%
8%
7%
7%
8%
7%
5%
4%
4%
3%
PC/Tablet
23%
20%
19%
15%
13%
10%
11%
11%
12%
13%
13%
13%
13%
10%
10%
11%
10%
8%
7%
6%
5%
Server
6%
6%
6%
7%
7%
7%
7%
7%
8%
8%
9%
10%
7%
6%
7%
9%
18%
31%
43%
51%
56%
Telecom
26%
34%
40%
43%
43%
45%
42%
38%
37%
36%
37%
33%
30%
29%
28%
28%
24%
20%
17%
14%
12%
Automotive
11%
12%
14%
17%
18%
20%
23%
23%
23%
27%
25%
27%
34%
41%
40%
39%
36%
31%
26%
23%
21%
Others
9%
7%
5%
5%
6%
6%
6%
9%
10%
8%
8%
8%
7%
7%
7%
6%
5%
4%
3%
3%
2%
AI Server
1%
3%
5%
13%
25%
38%
46%
52%
Page 16 · 四大厂稼动率
MLCC utilization for major four makers
50.0%
60.0%
70.0%
80.0%
90.0%
100.0%
110.0%
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q
4Q
1Q
2Q
3Q CoE
CY13
CY14
CY15
CY16
CY17
CY18
CY19
CY20
CY21
CY22
CY23
CY24
CY25
CY26
Simple average UT
Source: Company data (Murata Mfg., Taiyo Yuden, SEMCO, TDK), J.P. Morgan
Page 17 · MLCC 月产能
MLCC monthly capacity and yoy % chg.
Source: Company data (Murata Mfg., Taiyo Yuden, SEMCO, TDK and Yageo), J.P. Morgan estimates
0.00%
5.00%
10.00%
15.00%
20.00%
25.00%
0.00
100.00
200.00
300.00
400.00
500.00
600.00
700.00
800.00
(bn units/month)
Murata
Taiyo Yuden
TDK
SEMCO
Yageo
yoy % chg.
Page 18 · Murata 工厂建设
Murata Mfg. factory production
Announced
Products
Location
Start of construction
Completion
Building
Total Capex for building (¥mn)
Construction Size
Total floor area (m^2)
Building area (m^2)
Total area (m^2)
2014/09
MLCC
Fukui
2014/12
2015/09
For Production
10,000
Steel frame above 5 stories
22,620
3,600
-
2015/04
R&D
Nagaoka
2015/05
2016/02
Training Facilities
NA
Steel frame above 2/3 stories
Training 3,386
Lodging 953
Training 2,006
Lodging 357
-
2015/05
MLCC
Izumo
2015/04
2015/12
For Production
Steel frame above 4 stories
5,334
1,331
-
2015/05
MLCC
Izumo
2015/04
2016/10
For Production
Steel frame above 6 stories
22,436
3,504
-
2015/10
NA
Kanazawa
2015/11
2016/09
For Production
12,000
Steel frame above 7 stories
34,709
5,694
-
2015/12
Tooling
Sabae
2016/01
2017/01
For Production
2,700
Steel frame above 4 stories
8,181
1,500
-
2016/05
Modules
Komoro
2016/08
2017/05
For Production
NA
Steel frame above 5 stories
10,624
2,537
-
2016/7
MLCC
Toyama
2016/10
2017/06
For Production
NA
Steel frame above 6 stories
28,500
4,443
-
2016/10
MLCC
Fukui
2017/02
2017/10
For Material Production
10,000
Steel frame above 7 stories
18,119
3,522
-
2017/03
Inductor
Tome
2016/05
2017/03
For Production
1,900
Steel frame above 3 stories
5,750
NA
-
2017/03
HQ
Nagaokakyo
2016/03
2017/03
NA
NA
Steel frame above 2/3 stories
9,525
NA
-
2017/06
NA
Komoro
2016/08
2017/06
For Production
NA
Steel frame above 5 stories
10,624
2,537
-
2017/06
Metrocirc
Toyama
2016/10
2017/06
For Production
17,000
Steel frame above 6 stories
29,299
5,906
-
2017/07
MLCC
Yokaichi
2016/08
2017/07
For Material
NA
Steel frame above 7 stories
12,574
1,985
-
2017/10
Metrocirc
Wakura
2018/02
2019/01
For Production
3,500
Steel frame above 3 stories
11,310
3,310
-
2017/10
Metrocirc
Kanawaza/Nomi
2017/10
2017/10
Factory acquisition
NA
NA
NA
NA
121,760
2017/11
MLCC
Fukui
2017/02
2017/11
For Production
10,000
Steel frame above 10 stories
18,119
3,500
-
2017/11
NA
Okayama
2017/12
2018/11
For Production
10,000
Steel frame above 6 stories
28,384
4,908
-
2017/11
R&D
Yokohama
2018/05
2020/10
Innovation center
40,000
Steel frame above 18 /
below 2 stories / 1 tower building
65,335
7,415
7,415
2017/12
NA
Okayama
2017/04
2017/12
For Logistic
1,600
Steel frame above 5 stories
4,893
1,317
-
2018/03
MLCC
Philippine
2017/02
2018/03
For Production
5,000
RC above 2 stories
73,117
32,278
-
2018/05
Metrocirc
Ise
2018/06
2019/04
For Production
4,000
Steel frame above 6 stories
13,887
2,779
-
2018/06
MLCC
Fukui
2018/06
2019/12
For Production
29,000
Steel frame above 6 stories
Production: 54,144
Energy : 4,295
Production: 9,383
Energy : 1,800
-
2018/06
MLCC
Izumo
2017/05
2018/06
Logistic, Welfare
3,800
Steel frame above 3/6 stories
L 7,319 / W 4,640
L 1,470 / F 1,914
-
2018/08
Battery
Wuxi
-
2018/08
Logistic, Welfare
16,000
Production steel frame above 5 stories
Welfare steel frame above 6 stories
Production: 88,178
Welfare: 7,308
22,508
-
2018/08
MEMS sensor
Finland
2018/08
2019/12
For Production
5,000
Above 5 stories
16,000
NA
-
2018/09
MLCC
Izumo
2018/10
2019/11
For Production
40,000
Production: Steel frame above 4 stories
Energy: Steel frame above 3 stories
41,125
10,210
-
2018/10
MLCC
Okayama
2018/10
2019/10
For Production, Material
10,000
Steel frame above 5 / below 1 stories
25,845
5,841
-
2018/10
NA
Malaysia
2018/10
2020/01
For Production
4,000
Reinforced concrete, 3 floors above ground /
1 tower building
23,007
7,699
-
2018/11
MLCC
Wuxi
2018/11
2019/12
For Production
14,000
Production: Reinforeced concrete, 4 stories
Office: Reinforced concrete. 5 stories
Energy: Reinforced concrete, 3 stories
Poduction: 94,925
Office: 15,708
Energy: 16,595
Poduction: 22,155
Office: 15,708
Energy: 16,595
-
2019/12
EMI Filter/Antenna Coil
Thailand
2018/12
2019/10
For Production
EMI Filter Plant: 1,500
Antenna Coil Plant: 1,400
EMI Filter Plant: Reinforced concrete, 2 stories
Antenna Coil Plant: Reinforeced concrete, 2 stories
EMI Filter Plant: 9,993
Antenna Coil Plant: 9,995
EMI Filter Plant: 5,166
Antenna Coil Plant: 5,138
-
2019/07
Electrode Materials
Shiga (Yasu)
2019/07
2021/02
For Material Production
14,000
Steel frame above 7 stories
23,052
4,289
-
2019/08
MLCC
Shimane (Izumo)
2019/08
2020/07
For Production
4,990
Steel frame above 4 stories
9,328
2,812
-
2019/12
Ceramic material
Okayama
2019/12
2020/12
For Production
16,000
Production: Steel frame above 7 stories
Office: Steel frame above 3 stories
Energy: Steel frame above 2 stories
Production: 33,262
Office: 3,812
Energy: 1,706
Production: 5,306
Office: 1,361
Energy: 873
-
2021/11
RF module
Nagano
2021/11
2022/12
For Production
5,770
Steel frame above 5 stories
13,460
3,300
-
2021/11
MLCC
Thailand
2021/07
2023/03
For Production
12,000
Reinforced concrete, 2 floors above ground
80,950
35,088
-
2022/01
R&D (Plating technology)
Fukui (Sabae)
2022/02
2023/08
For R&D
6,400
Steel frame above 6 / below 1 stories
11,322
1,797
-
2022/03
MLCC
Shimane (Izumo)
2022/03
2023/04
For Production
12,000
Steel frame above 4 stories
22,120
6,314
-
2022/03
NA
Shenzhen
2020/12
2022/03
Welfare
NA
Reinforced concrete above 5 stories
9,446
2,019
-
2022/05
NA
Yokaichi
2022/05
2023/05
Welfare
3,550
Steel frame, above 3 stories (4 stories in some areas)
6,584
2,400
-
2022/06
Inductor
DaNang
2022/06
2023/08
For Production
4,320
RC above 4 stories
22,637
5,486
-
2022/11
MLCC
Wuxi
2022/11
2024/04
For Production
44,500
Production: RC above 3 stories
Wareghouse: Steel frame above 4 stories
EC: RC, 1 basement level, above 4 stories
Production: 27,140
Warehouse: 11,630
EC: 12,519
Production: 6,557
Warehouse: 2,797
EC: 2,409
-
2023/08
MLCC
Philippines
2023/08
2025/09
For Production
11,200
RC above 2 stories
77,981
32,454
-
2024/5
MLCC
Izumo
2024/3
2026/3
For Production
47,000
NA
69,676
10,742
2025/05
Inductor
Ho Chi Minh
2025/05
2026 1H
For Production
3,000
RC above 3 stories
10,576
3,500
-
2026/02
MLCC
Fukui (Echizen)
2023/11
2026/02
For R&D
35,000
Steel frame above 5 stories
41,709
-
54,450
2026/05
Thermistor
Yokaichi
2026/05
2026/08
For Production
16,900
Steel frame, 5 stories
18,010
2,951
-
2026/05
Chip inductors
noise suppression filters
Miyagi (Tome)
2026/05
2027/12
For Production
9,700
Steel frame, 4 stories
13,391
3,902
-
18,000
Source: Company data
Page 19 · 供需平衡模型
MLCC supply-demand model
 -
 1,000
 2,000
 3,000
 4,000
 5,000
 6,000
 7,000
 8,000
 9,000
-10%
-5%
0%
5%
10%
15%
20%
2017
2018
2019
2020
2021
2022
2023
2024
2025
2026E
2027E
2028E
2029E
2030E
bn units
MLCC industry procurement (RHS)
MLCC industry volume (supply, RHS)
MLCC industry S-D (%, LHS)
Source: Company data, J.P. Morgan estimates
Page 20 · 降价对 OP 的冲击
MLCC capacity utilization and impact on operating profit
from price declines
Note: Impact on operating profit from price declines for Murata Mfg. and Taiyo Yuden
Source: Utilization company data from Murata Mfg., Taiyo Yuden, SEMCO, TDK
Murata Mfg. – Impact on operating profit from price declines and
MLCC industry capacity utilization
Taiyo Yuden – Impact on operating profit from price declines and
MLCC industry capacity utilization
Murata Mfg. – Impact on operating profit from price declines and % of
price decline
Taiyo Yuden – Impact on operating profit from price declines and % of
price decline
60%
70%
80%
90%
100%
-15,000
-10,000
-5,000
0
5,000
10,000
15,000
20,000
2Q 4Q 2Q 4Q 2Q 4Q 2Q 4Q 2Q 4Q 2Q 4Q 2Q 4Q 2Q 4Q 2Q 4Q 2Q 4Q 2Q 4Q 2Q 4Q 2Q 4Q 2Q
CY13 CY14 CY15 CY16 CY17 CY18 CY19 CY20 CY21 CY22 CY23 CY24 CY25CY26
OP impact by price decline (QoQ, ¥bn, LHS)
MLCC Industry Utilization
60.0%
70.0%
80.0%
90.0%
100.0%
-4,000
-3,000
-2,000
-1,000
0
1,000
2,000
3,000
2Q
4Q
2Q
4Q
2Q
4Q
2Q
4Q
2Q
4Q
2Q
4Q
2Q
4Q
2Q
4Q
2Q
4Q
2Q
4Q
2Q
4Q
2Q
4Q
2Q
4Q
2Q
CY13 CY14 CY15 CY16 CY17 CY18 CY19 CY20 CY21 CY22 CY23 CY24 CY25 CY26
OP impact by price decline (QoQ, ¥bn, LHS)
MLCC Industry Utilization
-16.0%
-14.0%
-12.0%
-10.0%
-8.0%
-6.0%
-4.0%
-2.0%
0.0%
-140,000
-120,000
-100,000
-80,000
-60,000
-40,000
-20,000
0
JPY mn
Price decline (LHS)
% of price decline (RHS)
-25.0%
-20.0%
-15.0%
-10.0%
-5.0%
0.0%
5.0%
-30,000
-25,000
-20,000
-15,000
-10,000
-5,000
0
5,000
JPY mn
Price Deline (LHS)
% of price decline (RHS)
Page 21 · AI 服务器出货与 TDP(GW)
-
 5
 10
 15
 20
 25
 30
2022
2023
2024
2025
2026E
2027E
2028E
mn units
High end datacenter GPU volumes
AI GPU peripheral cards
ASIC chip volume
Shipment forecasts for AI servers and ASIC/GPU for AI
servers, total TDP GW and average TDP forecast
Note: Our Taiwan technology team‘s forecasts as of April 2026.
Source: Company reports, Gartner®, J.P. Morgan estimates
AI server shipment forecasts
GPU/ASIC shipment forecasts for AI server
 -
 5.0
 10.0
 15.0
 20.0
 25.0
2022
2023
2024
2025
2026E
2027E
2028E
mn units
AI Servers
Non AI Servers
0%
20%
40%
60%
80%
100%
120%
140%
160%
180%
 -
 5.00
 10.00
 15.00
 20.00
 25.00
 30.00
 35.00
 40.00
2023
2024
2025
2026E
2027E
Total TDP (GW)
NVDIA
AMD
Google
AWS
META
Microsoft
yoy % chg. (lhs)
0%
10%
20%
30%
40%
50%
60%
 -
 200.00
 400.00
 600.00
 800.00
 1,000.00
 1,200.00
 1,400.00
 1,600.00
 1,800.00
2023
2024
2025
2026E
2027E
TDP (W)
Average TDP (W, LHS)
yoy % chg. (RHS)
AI server total TDP shipment (GW)
GPU/ASIC average TDP
Page 22 · AI 加速器 TDP 趋势
AI accelerator TDP trend
Nvidia GPU
Generation
Ampere
Product
A100
H100
H200
B100
B200
B300
Rubin
Rubin Ultra
Feynman
Feynman Ultra
GPU TDP W
400
700
700
700
1000
1400
2300
3600
4400
6000
% chg. vs prior gen.
-
75%
0%
0%
43%
40%
64%
57%
22%
36%
Google TPU
Product
TPU v1
TPU v2
TPU v3
TPU v4
TPU v5e
TPU v5p
TPU v6
Trillium
TPU v7e
Ironwood
TPU v7p
Ironwood
ASIC TDP W
75
280
220
170-175
120-200
250-300
120-200
AWS
Product
Trainium1
Trainium2
Trainium3
Trainium4
ASIC TDP W
300
500
500-1000
600-1200
Microsoft
Microsoft
Maia100
Maia200
Maia300
ASIC TDP W
700
750
750
META
Product
MTIA 100
MTIA 200
MTIA 300
MTIA 400
MTIA 450
MTIA 500
ASIC TDP W
25
90
800
1200
1400
1700
AMD
Product
MI300X/325X
MI350X/355X
MI430X/440X/455X
GPU TDP W
750/1000
1000/1400
1400/2000
Huawei
Product
Ascend 910B
Ascend 910C
Ascend 950PR
ASIC TDP W
400
600
600
Hopper
Blackwell
Rubin
Feynman
600-700
Source: Company data
Page 23 · AI 服务器 MLCC 用量/ASP
0
0.1
0.2
0.3
0.4
0.5
0.6
0.7
0.8
0.9
Average
IT average
Server Average
Automotive Average
MLCC ASP (US cent)
MLCC units per box, MLCC average capacitance, server
MLCC revenue, MLCC ASP comparison by application
MLCC capacitance per unit
base board basis for AI server
Source: Company data, J.P. Morgan estimates as of June 2026
FY25 Sever MLCC revenue image
0.0
5.0
10.0
15.0
20.0
25.0
High end
Smartphone
NBPC
Server
H100
GB200
GB300
Vera Rubin
Average MLCC Capacitance (uF)
 -
 50,000
 100,000
 150,000
 200,000
 250,000
 300,000
 350,000
 400,000
High end
Smartphone
NBPC
Server
H100
GB200
GB300
Vera Rubin
Average MLCC Capacitance (uF)
MLCC average capacity per unit
0
50,000
100,000
150,000
200,000
250,000
Total Server
Ai Server
General Server
JPY mn
Murata
SEMCO
Taiyo Yuden
MLCC ASP by application (2025)
Page 24 · AI 服务器电容应用位置
Applications for capacitors in AI servers
Source: Company data, J.P. Morgan
Page 25 · MLCC 成本/利润率 Gen5-7
MLCC cost/margin analysis (model case for Murata Manufacturing)
Gen5
Gen6
Gen7
Launched
2014-2015
2018-2020
2023-2025
Standard
High-end
New Generation
1005/10uF
1005/22uF
1005/47uF
ASP (cent)
0.8
2.3
10.0
Price per uF (cent)
0.080
0.102
0.213
BT diameter (nm)
150.0
100.0
80.0
Thickness Green sheet (um)
1.20
0.80
0.50
Layer count
400.0
750.0
1,000.0
Variable
0.40
0.74
1.92
Assuming 50% yield for New Generation
Fixed cost
0.24
0.44
1.15
New generation Fixed cost up 50-100% due
to lower yield and and additional step
Operating profits
0.16
1.07
6.92
Variable cost
50.0%
32.9%
19.2%
Fixed cost
30.0%
19.7%
11.5%
OPM
20.0%
47.4%
69.2%
Incremental Margin
50.0%
67.1%
80.8%
Source: J.P. Morgan calculations
Page 26 · GB300 与 VR200 分析
MLCC capacitance, ASP analysis for GB300 & VR200
•
In FY25, the average ASP for AI server MLCCs is around US$0.01.
•
Comparing GB300 versus VR200 on a per-rack basis, unit count increases by roughly 210k pieces and total capacitance by 7,000,000 µF, with
average capacitance rising to ~33 µF. The incremental demand is driven mainly by specs such as 1005/22µF and 1005/47µF—and the 1005/47µF
in particular carries a very high unit price. Based on the implied average capacitance, we estimate the incremental mix is roughly 50% 22µF / 50%
47µF, which suggests the ASP on the incremental units could exceed US$0.06.
•
We believe the incremental margin on 1005/47µF could be even higher than the ~70% average incremental margin, and operating margins could
potentially exceed 60%. Murata is meaningfully ahead of peers in side-forming MLCCs, and we think it is best positioned to capture the full benefit
of this demand ramp.
Volume
Capacitance uF
Average capacitance (uF)
US$
US cent  Per unit
High End Smartphone
1,200

4,100

3.42

General Server
3,000

22,000

7.33

GB200 (Rack)
355,000

4,000,000

11.27

GB300 (Rack)
355,000

5,000,000

14.08

2,840

0.8

VR200 (Rack)
564,000

12,000,000

21.28

10,155

1.8

VR-GB300
209,000

7,000,000

33.49

7,315

3.5

Type
Size (mm)
uF
Pricer per 1k units
ASP (US cent)
Price per uF
General Normal
0603
2.2uF
2.0
0.20
0.091
General Normal
1005
10uF
8.0
0.80
0.080
General Normal
1608
22uF
16.0
1.60
0.073
General Normal
2012
47uF
40.0
4.00
0.085
High-end Normal
0603
4.7uF
5.0
0.50
0.106
High-end Normal
1005
22uF
22.5
2.25
0.102
High-end Normal
1608
47uF
55.0
5.50
0.117
High-end Normal
2012
100uF
90.0
9.00
0.090
New gen Side Forming/Side Edge
0603
10uF
16.0
1.60
0.160
New gen Side Forming/Side Edge
1005
47uF
100.0
10.00
0.213
New gen Side Forming/Side Edge
1608
100uF
220.0
22.00
0.220
Page 27 · 侧面成型 MLCC 定义
④Cutting+(Side
forming process)
What is side forming MLCC?
Source: Company data, J.P. Morgan
Side forming
Normal MLCC
MLCC production process
⑤Firing
Side-surface edging
/ laser trimming
Side-sheet press
bonding (BaTiO3)
Electrode
Normal MLCC
Side forming type
Electrode
Electrode
L
L + 2α
(Side view)
(Top view)
Page 28 · MLCC 销售与 OPM 趋势
MLCC: Sales and OP margin trend
Note: All J.P. Morgan estimates are as of Sep 2026.
Source: Company data, J.P. Morgan estimates
MLCC revenue forecast
MLCC OP forecast
MLCC OPM forecast
 -
 500,000
 1,000,000
 1,500,000
 2,000,000
 2,500,000
 3,000,000
 3,500,000
JPY mn
Murata Mfg
Taiyo Yuden
TDK
 -
 200,000
 400,000
 600,000
 800,000
 1,000,000
 1,200,000
 1,400,000
 1,600,000
 1,800,000
 2,000,000
JPY mn
Murata Mfg
Taiyo Yuden
TDK
0.0%
10.0%
20.0%
30.0%
40.0%
50.0%
60.0%
Murata Mfg
Taiyo Yuden
TDK
Page 29 · Ibiden 分部
Ibiden (4062)
Sales and OP by segment
Note: All J.P. Morgan estimates are as of July 2026.
Source: Company data, J.P. Morgan estimates
Page 30 · AI 基板尺寸与层数
Substrate size and layer structure for AI/Gen server GPUs/CPUs/ASICs
Note: This is based on measurements and investigations we conducted on the products currently on the market.
Source: J.P. Morgan estimates
Substrate size by product (Xeon LGA4677=100)
SAP size by product (Xeon LGA4677=100)
Compay
Product
Layer count
L (mm)
W (mm)
Substrate Size
(mm2)
Build up layer
demand
(mm2)
Build-up layer
count
Intel
Xeon
LGA4677
5-2-5
77.50

56.50

4,378.75

43,788

10
Xeon Max
EMIB
5-2-5
NA
NA
5,700.00

57,000

10
Gaudi
NA
79.00

71.00

5,700.00

57,000

10
AMD
EPYQ
(Genoa, Bergamo)
5-2-5
72.00

75.40

5,428.80

54,288

10
MI350
8-2-8
75.40

72.00

5,428.80

86,861

16
CPU
9-2-9
78.00

78.00

6,084.00

109,512

18
Tranium3
9-2-9
73.00

88.00

6,424.00

115,632

18
Tranium4
11-2-11
115.00

120.00

13,800.00

303,600

22
Huawei
Ascend9100
NA
55.60

52.90

2,941.24

-

Microsoft
Maia100
8-2-8
70.00

70.00

4,900.00

78,400

16
H100
5-2-5
58.00

55.00

3,190.00

31,900

10
H200
6-2-6
58.00

55.00

3,190.00

38,280

12
B100
8-2-8
73.00

81.00

5,913.00

82,782

14
B200
8-2-8
73.00

81.00

5,913.00

82,782

14
Rubin
10-2-10
100.00

100.00

10,000.00

200,000

20
AWS
Nvidia GPU
Page 31 · Ibiden SAP 需求
0
50
100
150
200
250
300
CY2024
CY2026 CoE
CY2027 CoE
Ono
Gama
Ogaki Central
Ogaki
Philippines
Malaysia
Aoyanagi
Cell8
Cell6
Cell4/5
Cell2/3
--
--
--
Launch
2025/FQ2
2026 -
(negotiating)
2007/2020
1998
2000
Items produced
AI Server
Networking
Next Gen
Leading PKG
AI Server
General Server
PC
AI Server
PC
PC
Core Process
Core process
Server Ratio
-
-
55% -> 70%
75% ->85%
0%
-
-
Server Ratio is based on sales (FY24 1H -> FY24 2H)
Factory


Ibiden: SAP demand outlook
Note: All CoE are as of May 2026.
Source: Company data, J.P. Morgan
Ibiden: Index of load on server substrates (converted to SAP,
CY24=100)
Ibiden: SAP demand index for general purpose servers, AI servers
and PC (CY22=100)
Ibiden: FC-BGA factory and server production ratio
Page 32 · Ibiden 产能分配
Current
Future
Nvidia
Cell 2,3,4
Ono + Cell4
AMD
Cell2,3,4
Cell2,3,4,5
Others
Cel 2-3
Cel 2-3
Intel
Cell 5
Gama
Ibiden: Non-Intel capacity allocation and factory by customer,
revenues by customer
Note: All J.P. Morgan estimates are as of March 2026.
Source: Company data, J.P. Morgan estimates
Ibiden: SAP capacity
(non-Intel capacity 24/9=100)
Ibiden: ABF substrate revenue by customer
Ibiden: Factory by customer
0
 0
 00
  0
200
2 0
 00
  0
 00
  0
 00
2
2
26 6
2
2
2
 0
 ama
 ell      hilippines   ell   y 2
Non  ntel  apacity
Ibiden: ABF substrate OP by customer
 -
 100,000
 200,000
 300,000
 400,000
 500,000
 600,000
 700,000
 800,000
 900,000
 1,000,000
 FY3/2021 FY3/2022 FY3/2023 FY3/2024 FY3/2025 FY3/2026 FY3/2027E FY3/2028E FY3/2029E FY3/2030E FY3/2031E
JPY mn
 Intel
 Intel EMIB-T
 Nvidia
 AMD
 Others
 -
 50,000
 100,000
 150,000
 200,000
 250,000
 300,000
 350,000
 400,000
 FY3/2021 FY3/2022 FY3/2023 FY3/2024 FY3/2025 FY3/2026 FY3/2027E FY3/2028E FY3/2029E FY3/2030E FY3/2031E
JPY mn
FC-BGA substrate
New 2.5D substrate
Page 33 · Niterra 分部
Niterra (5334)
Sales and OP by segment
Note: All J.P. Morgan estimates are as of July 2026.
Source: Company data, J.P. Morgan estimates
Page 34 · Niterra 汽车
Automotive business earnings trend
Automotive business sales by product
OP margin trend by product
Automotive business OP by product
Note: All J.P. Morgan estimates are as of July 2026.
Source: Company data, J.P. Morgan estimates
0
100,000
200,000
300,000
400,000
500,000
600,000
700,000
800,000
JPY mn
Plugs
Sensors
0
20000
40000
60000
80000
100000
120000
140000
160000
180000
JPY mn
Plugs
Sensors
0%
5%
10%
15%
20%
25%
30%
35%
JPY mn
Total OPM
Plugs OPM
Sensors OPM
Page 35 · Niterra 非汽车
0
50,000
100,000
150,000
200,000
250,000
JPY mn
Cutting Tools
Industrial Ceramics/Nitride Silicon
SPE
Medical
Ceramic Package
Fuel Cells
Others
Non Automotive - Sales (JPY mn)
FY3/2020
FY3/2021
FY3/2022
FY3/2023
FY3/2024
FY3/2025
FY3/2026
FY3/2027E
FY3/2028E
FY3/2029E
Cutting Tools
12,700
9,800
11,835
12,783
600
0
0
0
0
0
Industrial Ceramics/Nitride Silicon
5,800
6,200
6,507
7,419
7,000
1,600
23,000
31,000
36,000
39,600
SPE
17,811
22,915
29,448
40,638
35,200
44,300
52,000
68,975
86,219
103,463
Medical
20,671
24,805
25,579
29,415
38,700
40,000
37,500
37,510
35,960
35,960
Ceramic Package
16,501
15,330
20,055
18,534
13,310
15,211
17,000
18,600
18,972
19,351
Fuel Cells
0
0
0
0
0
400
500
2,000
4,000
6,000
Others
3,658
9,884
10,534
9,790
14,321
12,588
13,702
12,000
12,000
12,000
Total Sales
77,141
88,934
103,958
118,579
109,131
114,099
143,702
170,085
193,151
216,374
Non Automotive - Operating profits (JPY mn)
FY3/2020
FY3/2021
FY3/2022
FY3/2023
FY3/2024
FY3/2025
FY3/2026
FY3/2027E
FY3/2028E
FY3/2029E
Cutting Tools
300
-400
980
800
1,500
300
0
0
0
0
Industrial Ceramics/Nitride Silicon
-900
-300
-900
0
-600
-1,700
-3,600
-5,500
-3,200
-1,760
SPE
-506
2,549
6,450
15,300
7,100
6,100
11,000
21,190
28,088
34,985
Medical
-427
-1,184
8,550
-2,600
-5,000
-7,300
-9,800
-2,000
-1,200
-400
Ceramic Package
35
-890
-397
-2,495
-3,591
-3,100
-1,500
-800
0
0
Fuel Cells
0
0
0
0
0
-300
-200
-200
200
400
Others
-3,061
-8,976
-13,513
-15,046
-13,063
-5,196
6,956
0
0
0
Total OP
-4,559
-9,201
1,170
-4,041
-13,654
-11,196
2,856
12,690
23,888
33,225
-30,000
-20,000
-10,000
0
10,000
20,000
30,000
40,000
JPY mn
Cutting Tools
Industrial Ceramics/Nitride Silicon
SPE
Medical
Ceramic Package
Fuel Cells
Others
Total OP
Niterra: Earnings trend for non-automotive
Note: All J.P. Morgan estimates are as of July 2026.
Source: Company data, J.P. Morgan estimates
Non-automotive business sales
Non-automotive business OP
Page 36 · MinebeaMitsumi
MinebeaMitsumi (6479)
Sales and OP by segment
Note: All J.P. Morgan estimates are as of July 2026.
Page 37 · Nidec
Nidec (6594)
Sales and OP by segment
Note: All J.P. Morgan estimates are as of Dec 2025.
Page 38 · Wacom
Wacom (6727)
Sales and OP by segment
Note: All J.P. Morgan estimates are as of July 2026.
Page 39 · TDK 分部
TDK (6762)
Sales and OP by segment
Note: All J.P. Morgan estimates are as of Sep 2026.
Page 40 · TDK 分部预测
TDK: OP forecast by segment, sensor, battery, magnetic application
sales breakdown
OP forecast by segment
Sensor business – Sales forecast by application
Battery business – Sales forecast by application
Note: All J.P. Morgan estimates are as of Sep 2026.
Source: Company data, J.P. Morgan estimates
Magnetic business – Sales forecast by application
-200,000
-100,000
0
100,000
200,000
300,000
400,000
500,000
600,000
700,000
FY15 FY16 FY17 FY18 FY19 FY20 FY21 FY22 FY23 FY24 FY25 FY26EFY27EFY28E
JPY mn
Passive Components
Sensor Applied Products
Magnetic Applicaton Products
Energy Application Products
Film Application
Other (-FY3/18)
Other (FY3/19-)
Elimination
Total Operaing Profit
 -
 200,000
 400,000
 600,000
 800,000
 1,000,000
 1,200,000
 1,400,000
 1,600,000
 1,800,000
 2,000,000
FY15 FY16 FY17 FY18 FY19 FY20 FY21 FY22 FY23 FY24 FY25 FY26EFY27EFY28E
JPY mn
Small cells - Smartphonbe
Small cells - NBPC/Tablet
Small cells - Others
Mid cells
 -
 50,000
 100,000
 150,000
 200,000
 250,000
 300,000
FY15 FY16 FY17 FY18 FY19 FY20 FY21 FY22 FY23 FY24 FY25 FY26EFY27EFY28E
JPY mn
Tempreture and Pressure Sensor
Magnetic Sensor
MEMS products
 -
 100,000
 200,000
 300,000
 400,000
 500,000
 600,000
FY15 FY16 FY17 FY18 FY19 FY20 FY21 FY22 FY23 FY24 FY25 FY26EFY27EFY28E
JPY mn
HDD head
HDD suspension
Magnet
Others
Page 41 · Alps Alpine
Alps Alpine (6770)
Sales and OP by segment
Note: All J.P. Morgan estimates are as of July 2026.
Page 42 · Hirose 按应用
Hirose Electric (6806)
Sales by application
Note: All J.P. Morgan estimates are as of Sep 2026.
Page 43 · Hirose 明细
Hirose Electric: Sales by application and sales breakdown
for telecom equipment
Note: All J.P. Morgan estimates are as of Sep 2026.
Source: Company data, J.P. Morgan estimates
Sales forecast by application
Sales forecast for telecom equipment
0
50,000
100,000
150,000
200,000
250,000
300,000
350,000
FY3/2016
FY3/2017
FY3/2018
FY3/2019
FY3/2020
FY3/2021
FY3/2022
FY3/2023
FY3/2024
FY3/2025
FY3/2026
FY3/2027E
FY3/2028E
FY3/2029E
JPY mn
Connector -- Industrial
Connector -- Automotive
Connector -- Smartphone
Connector -- Consumer Mobile
Connector -- Others
Others
0
2000
4000
6000
8000
10000
12000
14000
16000
18000
20000
FY3/2025
FY3/2026
FY3/2027E
FY3/2028E
FY3/2029E
JPY mn
Non AI
AI Server
Page 44 · JAE
Japan Aviation Electronics (6807)
Sales and OP by segment
Note: All J.P. Morgan estimates are as of Sep 2026.
Page 45 · Rohm 分部
Rohm (6963)
Sales and OP by segment
Note: All J.P. Morgan estimates are as of July 2026.
Page 46 · 分立器件份额
2023
2024
2023
2024
Discrete Total
Sales (mn$) Sales (mn$)
Share
Share
Infineon
7,855

7,060

20.7%
20.2%
Onsemi
3,824

3,335

10.1%
9.5%
STMicroelectronics
3,092

2,465

8.2%
7.0%
Nexperia
1,761

1,673

4.6%
4.8%
Mitsubishi Electric
1,638

1,598

4.3%
4.6%
Fuji Electric
1,386

1,245

3.7%
3.6%
ROHM
1,322

1,175

3.5%
3.4%
Vishay
1,302

1,125

3.4%
3.2%
Hangzhou Silan Microelectonics
982

1,056

2.6%
3.0%
BYD
657

980

1.7%
2.8%
Toshiba
1,113

935

2.9%
2.7%
Others
12,956

12,383

34.2%
35.3%
Total
37,888

35,030

100.0%
100.0%
Rohm + Toshiba
2,435

2,110

6.4%
6.0%
Rohm + Toshiba + Mitsubishi Elec.
4,073

3,588

10.8%
10.2%
2023
2024
2023
2024
Small Signal Discretes
Sales (mn$) Sales (mn$)
Share
Share
Nexperia
637

687

16.1%
19.0%
Onsemi
654

502

16.6%
13.9%
ROHM
406

353

10.3%
9.8%
Diodes
336

260

8.5%
7.2%
Vishay
274

237

6.9%
6.6%
STMicroelectronics
228

221

5.8%
6.1%
Infineon
193

178

4.9%
4.9%
China Resources Microelectronics
180

176

4.6%
4.9%
Semtech
167

167

4.2%
4.6%
Toshiba
202

162

5.1%
4.5%
Others
673

673

17.0%
18.6%
Total
3,950

3,616

100.0%
100.0%
Rohm + Toshiba
608

515

15.4%
14.2%
Rohm + Toshiba + Mitsubishi Elec.
693

629

17.5%
17.4%
2023
2024
2023
2024
Power Discretes
Sales (mn$) Sales (mn$)
Share
Share
Infineon
7,399

6,617

24.6%
23.9%
Onsemi
3,166

2,829

10.5%
10.2%
STMicroelectronics
2,798

2,216

9.3%
8.0%
Mitsubishi Electric
1,553

1,484

5.2%
5.4%
Fuji Electric
1,386

1,245

4.6%
4.5%
Hangzhou Silan Microelectonics
967

1,040

3.2%
3.8%
BYD
657

980

2.2%
3.5%
Vishay
1,028

888

3.4%
3.2%
Nexperia
956

831

3.2%
3.0%
ROHM
913

819

3.0%
3.0%
Toshiba
905

769

3.0%
2.8%
Others
622

655

2.1%
2.4%
Total
30,102

27,722

100.0%
100.0%
Rohm + Toshiba
1,818

1,588

6.0%
5.7%
Rohm + Toshiba + Mitsubishi Elec.
3,371

3,072

11.2%
11.1%
0
500
1,000
1,500
2,000
2,500
3,000
3,500
$mn
Rohm
Rohm+Toshia
Rohm+Toshiba+Mitsubishi Elec.
0
500
1,000
1,500
2,000
2,500
3,000
Automotive
Wired
Communication
Wireless
Communication
Cosumer
Electronics
Computer
Storage
Industrial, others
$mn
Rohm
Rohm + Toshiba
Rohm+Toshiba+Mitsubishi Elec.
Discrete semiconductor market share, Rohm/Toshiba/Mitsubishi Electric (power
semi) revenue by application and product
Source: Omdia, Gartner® and J.P. Morgan
Discrete semiconductor market share
Rohm/Toshiba/revenue by product and application
FY3/27 earnings level
•
Rohm sales ¥560bn/OP ¥63bn
•
Toshiba (semiconductor) sales ¥420-440bn/OP ¥20-30bn
2 company total sales roughly ¥1trn/OP ¥90bn in FY3/27
•
Mitsubishi Elec (power semi) sales ¥215bn/OP ¥25bn
3 company total sales ¥1.22trn/OP ¥115bn
Page 47 · 服务器电源器件
Server Power Device (incl. DrMOS) Industry outlook


Source: Company data (ROHM estimates)
Page 48 · Kyocera 销售额
Kyocera (6971)
Sales by segment
Note: All J.P. Morgan estimates are as of July 2026.
Page 49 · Kyocera OP
Kyocera (6971)
OP by segment
Note: All J.P. Morgan estimates are as of July 2026.
Source: Company data, J.P. Morgan estimates
Page 50 · 太阳诱电
Taiyo Yuden (6976)
Sales by segment
Page 51 · Murata 分部
Murata Mfg. (6981)
Sales and OP by segment
Note: All J.P. Morgan estimates are as of Sep 2026.
Page 52 · Nichicon
Nichicon (6996)
Sales and OP by segment
Note: All J.P. Morgan estimates are as of Sep 2026.
Page 53 · Nippon Chemi-con
Nippon Chemi-con (6997)
Sales and OP by segment
Note: All J.P. Morgan estimates are as of Sep 2026.
Source: Company data, J.P. Morgan estimates
Page 54 · NISSHA
NISSHA (7915)
Sales and OP by segment
Note: All J.P. Morgan estimates are as of July 2026.